Paper I — Q1
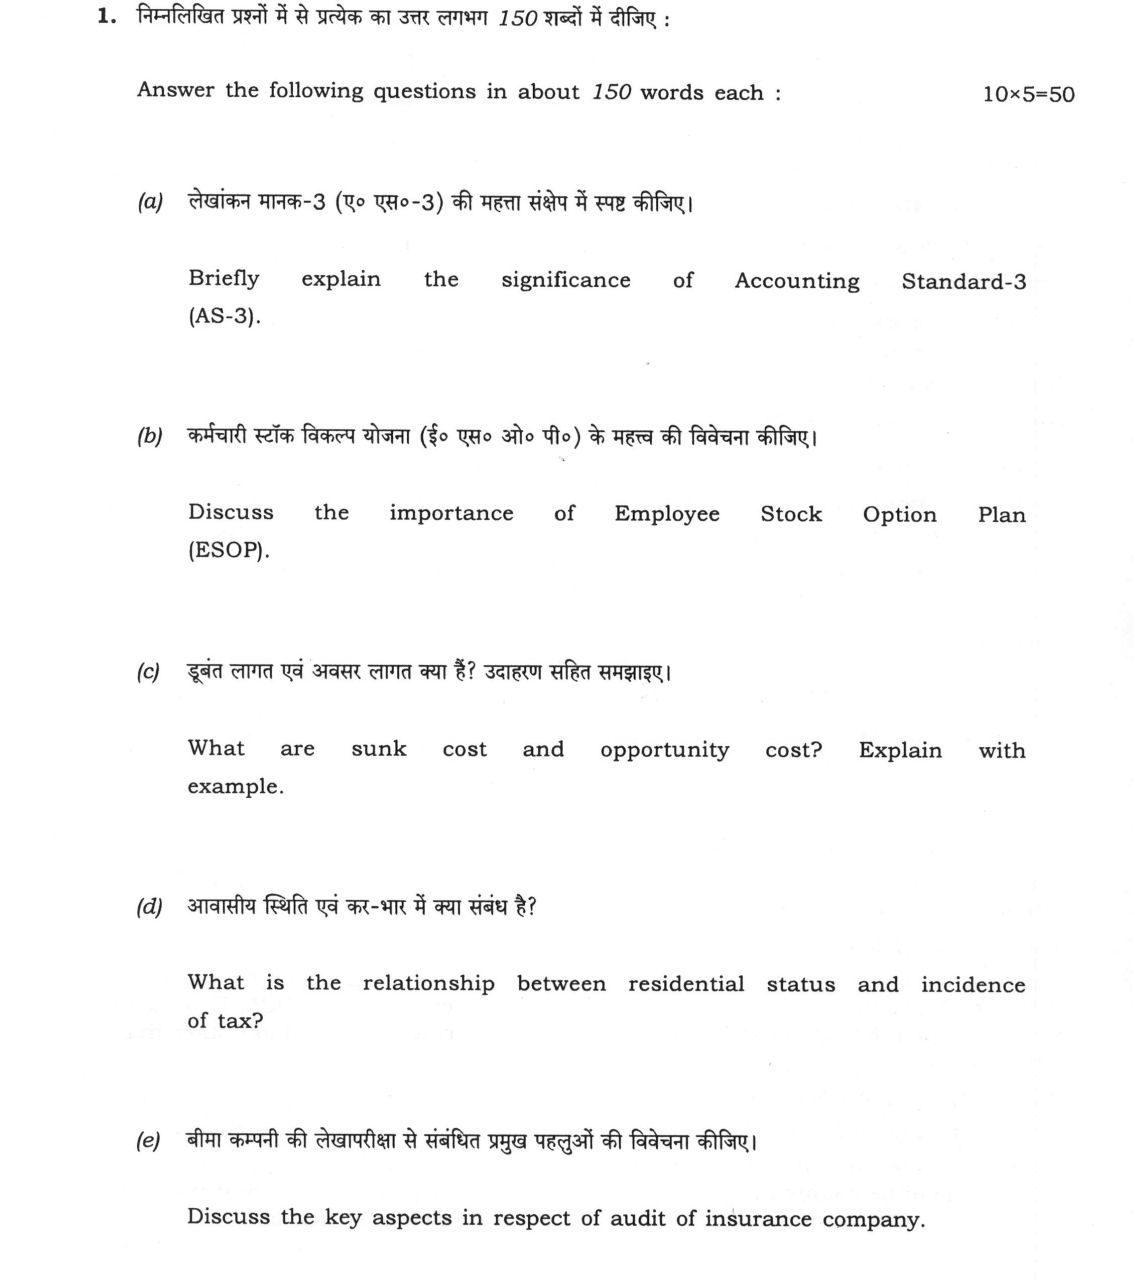
(a) Briefly explain the significance of Accounting Standard-3 (AS-3). (10 marks) (b) Discuss the importance of Employee Stock…
Answer the following questions in about 150 words each:
Briefly explain the significance of Accounting Standard-3 (AS-3). 10 marks
Discuss the importance of Employee Stock Option Plan (ESOP). 10 marks
What are sunk cost and opportunity cost? Explain with example. 10 marks
What is the relationship between residential status and incidence of tax? 10 marks
Discuss the key aspects in respect of audit of insurance company. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए :
लेखांकन मानक-3 (ए० एस०-3) की महत्ता संक्षेप में स्पष्ट कीजिए। (10 अंक)
कर्मचारी स्टॉक विकल्प योजना (ई० एस० ओ० पी०) के महत्व की विवेचना कीजिए। (10 अंक)
डूबंत लागत एवं अवसर लागत क्या हैं? उदाहरण सहित समझाइए। (10 अंक)
आवासीय स्थिति एवं कर-भार में क्या संबंध है? (10 अंक)
बीमा कंपनी की लेखापरीक्षा से संबंधित प्रमुख पहलुओं की विवेचना कीजिए। (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Significance of Accounting Standard-3 (AS-3)
AS-3 (Cash Flow Statements), issued by the ICAI, requires an enterprise to report its cash flows during a period, classified under operating, investing and financing activities. Its significance lies in showing what a profit and loss account cannot: the real movement of cash.
- It reconciles accrual profit with cash by removing non-cash items such as depreciation and provisions, so users can judge the quality of earnings.
- It helps creditors, investors and management assess liquidity, solvency, the ability to pay debt and dividends, and the need for external finance.
- It permits comparison across enterprises through a uniform format, with the direct or indirect method for operating activities and a separate disclosure of cash and cash equivalents.
- The statement is part of the financial statements under Section 2(40) of the Companies Act, 2013. Companies following Ind AS use Ind AS 7 instead.
(b) Importance of Employee Stock Option Plan (ESOP)
An ESOP gives employees the option, not the obligation, to buy the company's shares at a fixed exercise price after a vesting period. It is governed by Section 62(1)(b) of the Companies Act, 2013 with Rule 12 of the Share Capital and Debentures Rules, 2014, and, for listed companies, the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021.
- It aligns employee and shareholder interests, because employees gain when the share value rises.
- Vesting periods retain key talent and cut attrition.
- It lets cash-constrained firms, such as start-ups, attract talent by offering equity in place of high salaries.
- It builds a sense of ownership and long-term commitment.
- For the company, the cost is recognised as an employee expense over the vesting period, and for the employee the perquisite at exercise is taxed as salary. Exercise dilutes existing shareholders.
(c) Sunk cost and opportunity cost
A sunk cost is a cost already incurred in the past that cannot be recovered or changed by any present or future decision, so it is irrelevant to the decision. For example, ₹50 crore spent on the development of a drug that failed trials is sunk and should not justify more spending on it.
An opportunity cost is the benefit lost by giving up the next best alternative when a choice is made. It is not recorded in the books but is relevant to decisions. For example, a firm that uses its own building for its factory instead of leasing it for ₹12 lakh a year bears an opportunity cost of ₹12 lakh.
(d) Residential status and incidence of tax
Under Section 5 of the Income-tax Act, 1961, the scope of taxable income depends on the residential status fixed by Section 6, not on citizenship.
- A resident and ordinarily resident (ROR) is taxed on global income: income received or accruing in India and also income accruing outside India.
- A resident but not ordinarily resident (RNOR) is taxed on Indian income and on foreign income only if it comes from a business controlled in, or a profession set up in, India.
- A non-resident is taxed only on income received or accruing in India, or deemed to do so.
An individual is resident if present in India for 182 days in the year, or for 60 days in the year and 365 days in the preceding four years (the 60-day limit becomes 120 days for those with Indian income over ₹15 lakh who are citizens or persons of Indian origin). The status also governs DTAA relief and compliance.
(e) Key aspects of the audit of an insurance company
Audit follows the Insurance Act, 1938, the IRDA Act, 1999 and the IRDAI (Preparation of Financial Statements and Auditors' Report of Insurance Companies) Regulations, 2002, which prescribe the formats of the accounts. Insurers have joint auditors, and the auditor relies on the appointed actuary's certificate for the following.
- Technical liabilities: outstanding claims, IBNR and IBNER provisions, reserve for unexpired risk, and policy liability in life insurance.
- Premium income, with the testing of recognition, coinsurance and commission.
- Reinsurance: treaties, cessions, recoveries and retention limits.
- Investments: custody, valuation, the approved investment pattern and fund-wise segregation of policyholders' funds.
- Solvency margin and statutory compliance, with checks on internal controls and IT systems.
How this answer will be evaluated
Framework: null
What earns full marks: Precise definitions, correct statutory references (AS-3, Sec 62, IT Act), and clear, distinct examples for every part.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Significance of Accounting Standard-3 (AS-3) regarding cash flow statements. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Identifies AS-3 as the standard for Cash Flow Statements
- Explains the three categories: Operating, Investing, Financing
- Mentions the benefit of assessing liquidity and solvency
- Notes the requirement for direct or indirect method
Loses marks
- Confusing AS-3 with AS-2 (Inventories) or AS-10 (Property, Plant and Equipment)
- Failing to distinguish between cash and cash equivalents
Earns more
- Notes that Ind AS 7 applies instead of AS-3 for companies following Ind AS
- Highlights the utility for creditors and investors
Extra mark
- References the specific ICAI notification or date of AS-3
- (b) Importance of Employee Stock Option Plan (ESOP) for companies and employees. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Defines ESOP as a long-term incentive scheme
- Explains the benefit of aligning employee and shareholder interests
- Mentions the role in retaining key talent
- Notes the tax benefits or accounting treatment (expense)
Loses marks
- Treating ESOP as a short-term cash bonus
- Ignoring the 'option' nature (right to buy, not obligation)
Earns more
- Mentions the Companies Act, 2013 provisions (Sec 62)
- Discusses the dilution of existing shareholders
Extra mark
- Cites a specific company example (e.g., TCS, Infosys) using ESOPs
- (c) Definitions and examples of sunk cost and opportunity cost. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Defines sunk cost as a past cost that cannot be recovered
- Defines opportunity cost as the value of the next best alternative
- Provides a clear example for sunk cost (e.g., R&D spent)
- Provides a clear example for opportunity cost (e.g., foregone rent)
Loses marks
- Confusing sunk cost with fixed cost
- Failing to provide the requested examples
Earns more
- Explains why sunk costs are irrelevant to future decisions
- Mentions opportunity cost in the context of capital budgeting
Extra mark
- References the 'sunk cost fallacy' in behavioral economics
- (d) Relationship between residential status and the incidence of tax. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Defines the statuses: resident and ordinarily resident, resident but not ordinarily resident, and non-resident (not 'NRI')
- Explains that Residents are taxed on Global Income
- Explains that NRIs are taxed only on India-sourced income
- Mentions the impact on tax liability and compliance
Loses marks
- Confusing 'Resident' with 'Citizen' status
- Failing to link status to the scope of income (Global vs India)
Earns more
- Mentions the Income Tax Act, 1961 Section 6 (Residency)
- Discusses the impact on Double Taxation Avoidance Agreements (DTAA)
Extra mark
- Mentions the specific day count (182/120 days) for residency
- (e) Key aspects of the audit of an insurance company. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Mentions the role of the IRDAI (Insurance Regulatory and Development Authority of India) and the Insurance Act, 1938
- Highlights the audit of actuarial liabilities and reserves
- Discusses the verification of investment portfolios
- Notes the IRDAI (Preparation of Financial Statements and Auditors' Report) Regulations, 2002 formats and the actuary's certificate
Loses marks
- Treating it as a standard corporate audit without insurance specifics
- Ignoring the regulatory (IRDAI) framework
Earns more
- Mentions the audit of reinsurance arrangements
- Discusses the going concern assumption in the insurance context
Extra mark
- References the specific IRDAI audit guidelines or circulars
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q1 Answer the following questions in about 150 words each: (a) Briefly explain the significa…
- Q2 (a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to ama…
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…