Paper I — Q4
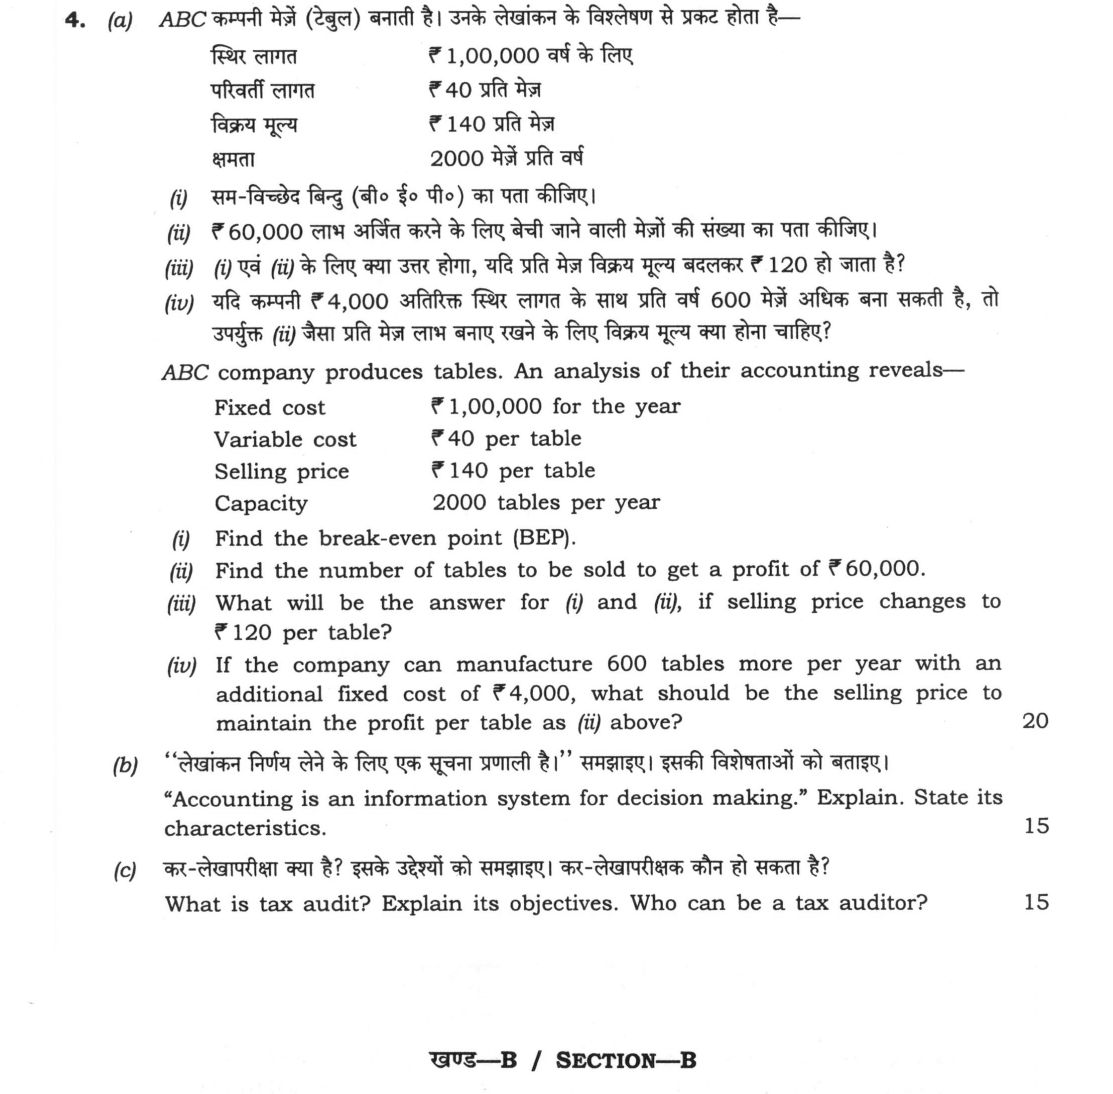
(a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,00,000 for the year Variable cost ₹40 per…
ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,00,000 for the year Variable cost ₹40 per table Selling price ₹140 per table Capacity 2000 tables per year
Find the break-even point (BEP).
Find the number of tables to be sold to get a profit of ₹60,000.
What will be the answer for (i) and (ii), if selling price changes to ₹120 per table?
If the company can manufacture 600 tables more per year with an additional fixed cost of ₹4,000, what should be the selling price to maintain the profit per table as (ii) above? 20 marks
"Accounting is an information system for decision making." Explain. State its characteristics. 15 marks
What is tax audit? Explain its objectives. Who can be a tax auditor? 15 marks
हिंदी में प्रश्न पढ़ें
ABC कम्पनी मेजें (टेबल) बनाती है। उनके लेखांकन के विश्लेषण से प्रकट होता है— स्थिर लागत ₹1,00,000 वर्ष के लिए परिवर्ती लागत ₹40 प्रति मेज विक्रय मूल्य ₹140 प्रति मेज क्षमता 2000 मेजें प्रति वर्ष
सम-विच्छेद बिन्दु (बी० ई० पी०) का पता कीजिए।
₹60,000 लाभ अर्जित करने के लिए बेची जाने वाली मेजों की संख्या का पता कीजिए।
(i) एवं (ii) के लिए क्या उत्तर होगा, यदि प्रति मेज विक्रय मूल्य बदलकर ₹120 हो जाता है?
यदि कम्पनी ₹4,000 अतिरिक्त स्थिर लागत के साथ प्रति वर्ष 600 मेजें अधिक बना सकती है, तो उपर्युक्त (ii) जैसा प्रति मेज लाभ बनाए रखने के लिए विक्रय मूल्य क्या होना चाहिए? (20 अंक)
"लेखांकन निर्णय लेने के लिए एक सूचना प्रणाली है।" समझाइए। इसकी विशेषताओं को बताइए। (15 अंक)
कर-लेखापरीक्षा क्या है? इसके उद्देश्यों को समझाइए। कर-लेखापरीक्षक कौन हो सकता है? (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Break-even analysis for ABC company
Contribution per table = 140 − 40 = ₹100.
- (i) BEP = fixed cost ÷ contribution per table = 1,00,000 ÷ 100 = 1,000 tables (sales ₹1,40,000).
- (ii) Tables for a profit of ₹60,000 = (1,00,000 + 60,000) ÷ 100 = 1,600 tables (sales ₹2,24,000), within capacity.
- (iii) At ₹120, contribution = 120 − 40 = ₹80. BEP = 1,00,000 ÷ 80 = 1,250 tables (sales ₹1,50,000). Tables for ₹60,000 profit = 1,60,000 ÷ 80 = 2,000 tables (sales ₹2,40,000), exactly at capacity.
- (iv) Profit per table in (ii) = 60,000 ÷ 1,600 = ₹37.50. New capacity = 2,000 + 600 = 2,600 tables and new fixed cost = 1,00,000 + 4,000 = ₹1,04,000, assuming all 2,600 tables are sold. Required profit = 2,600 × 37.50 = ₹97,500. Required sales = 1,04,000 + 2,600 × 40 + 97,500 = ₹3,05,500, so the selling price = 3,05,500 ÷ 2,600 = ₹117.50 per table.
Check: fixed cost per table = 1,04,000 ÷ 2,600 = ₹40, so price = 40 (variable) + 40 (fixed) + 37.50 (profit) = ₹117.50.
(b) Accounting as an information system and its characteristics
Accounting collects raw financial data about transactions, processes it by recording, classifying and summarising, and communicates it as financial statements and reports to users. This input, processing and output cycle turns data into information that reduces uncertainty in decisions. Management uses it for planning, control, pricing and investment, investors and lenders for investment and credit decisions, and the government for taxation and regulation.
Its characteristics are:
- It is systematic, following double entry and the accounting standards.
- It measures only events that can be expressed in money, mainly past events.
- It serves internal and external users, so it is both financial and management accounting.
- Its output must be relevant, reliable, timely, comparable and understandable.
- It rests on assumptions such as going concern, accrual, consistency and materiality.
- It is subject to legal and standards compliance (Companies Act, 2013, Ind AS/AS).
- It has limits: it leaves out qualitative factors, relies on estimates and is based on historical cost.
(c) Tax audit
A tax audit is an audit of a taxpayer's accounts by a Chartered Accountant under Section 44AB of the Income-tax Act, 1961, to check that income, deductions and tax have been correctly reported (the provision is carried into the Income-tax Act, 2025). It differs from a statutory audit, which gives a true and fair view for shareholders. It is required when business turnover exceeds ₹1 crore (₹10 crore if cash receipts and payments are 5% or less), when professional receipts exceed ₹50 lakh, and in certain presumptive-tax cases. The report is filed in Form 3CA or 3CB with the particulars in Form 3CD, and non-compliance attracts a penalty of 0.5% of turnover, up to ₹1.5 lakh (Section 271B).
Objectives:
- To check that proper books are kept and that they support the return.
- To verify that income, deductions, exemptions and tax liability are correctly computed.
- To check compliance with TDS, TCS and other provisions.
- To deter evasion and help the assessing officer with reliable, reported data.
Who can be a tax auditor: a Chartered Accountant within the meaning of the Chartered Accountants Act, 1949, holding a certificate of practice, or a firm of Chartered Accountants. The auditor should be independent of the assessee, and the ICAI caps the number of tax audits at 60 per CA per year.
How this answer will be evaluated
What earns full marks: Precise calculations with full workings; clear, structured theory with statutory references.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute BEP, sales for target profit, and revised price for new capacity. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- BEP formula: Fixed Cost / Contribution per unit
- Sales for profit: (Fixed Cost + Profit) / Contribution per unit
- Recalculate BEP and sales for profit with new selling price
- Derive new selling price to maintain profit per table
Loses marks
- Final figures without working notes
- Incorrect formula for break-even point
- Failure to adjust fixed cost in part (iv)
Earns more
- Explicit calculation of contribution per unit
- Step-by-step substitution of values
- Clear labeling of each sub-part (i) to (iv)
Extra mark
- Statement of margin of safety
- (b) Explain accounting as an information system and state its characteristics. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Definition of accounting as an information system
- Explanation of its role in decision making
- List of key characteristics (e.g., systematic, monetary)
- Connection between data processing and user needs
Loses marks
- Vague generalities without specific characteristics
- Failure to link to decision making
- Confusing accounting with bookkeeping
Earns more
- Mention of stakeholders (internal/external)
- Distinction between financial and management accounting
- Reference to qualitative characteristics (relevance, reliability)
Extra mark
- Reference to specific accounting standards (Ind AS)
- (c) Define tax audit, explain its objectives, and identify who can be a tax auditor. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Definition of tax audit under the Income Tax Act
- Explanation of objectives (e.g., verifying income, compliance)
- Identification of eligible tax auditors (Chartered Accountants)
- Mention of the statutory requirement for tax audit
Loses marks
- Confusing tax audit with GST audit
- Failure to name the specific professional (CA)
- Vague objectives without statutory context
Earns more
- Reference to Section 44AB of the Income Tax Act
- Distinction between tax audit and statutory audit
- Mention of the report format (Form 3CA/3CB)
Extra mark
- Reference to specific penalties for non-compliance
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q1 Answer the following questions in about 150 words each: (a) Briefly explain the significa…
- Q2 (a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to ama…
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…
- Q6 (a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. The…
- Q7 (a) XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the followin…