Paper I — Q6
(a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. These are mutually exclusive. Project X…
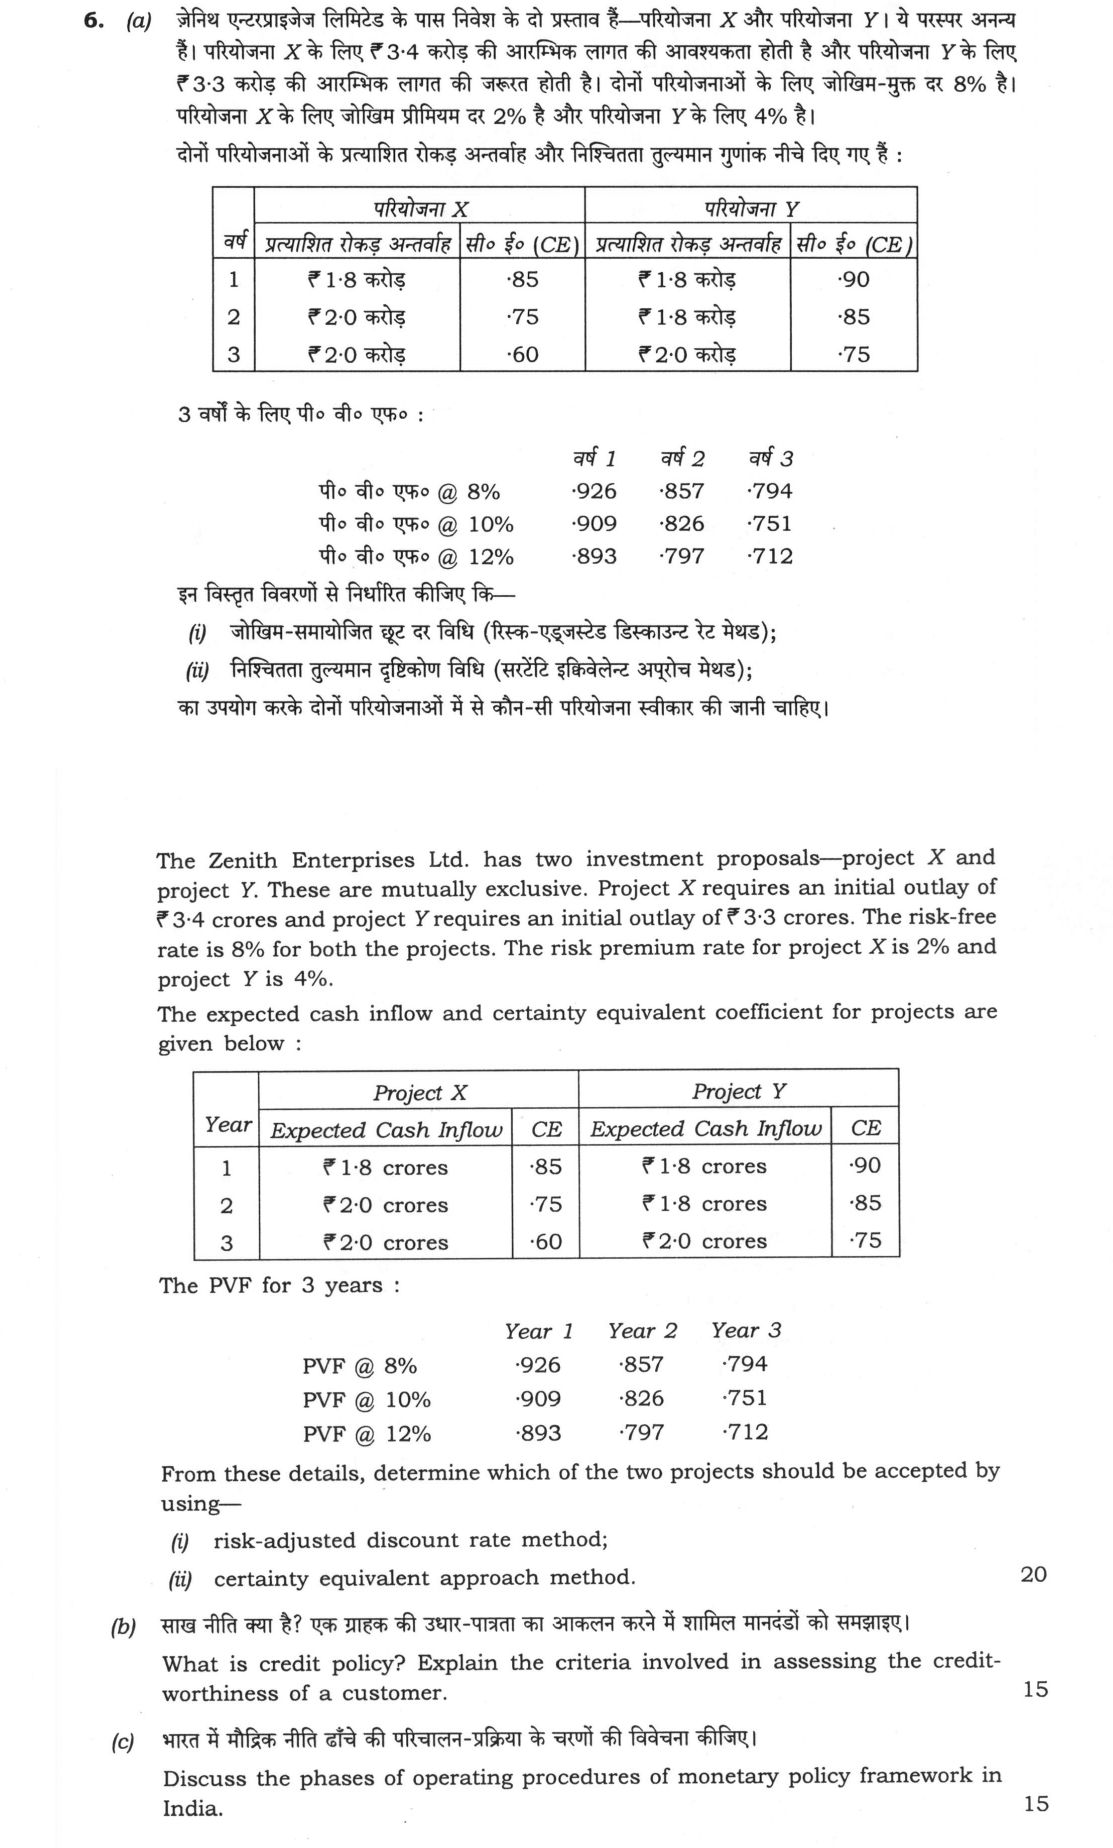
The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. These are mutually exclusive. Project X requires an initial outlay of ₹3·4 crores and project Y requires an initial outlay of ₹3·3 crores. The risk-free rate is 8% for both the projects. The risk premium rate for project X is 2% and project Y is 4%.
The expected cash inflow and certainty equivalent coefficient for projects are given below:
| Year | Project X | Project Y | ||
|---|---|---|---|---|
| Expected Cash Inflow | CE | Expected Cash Inflow | CE | |
| 1 | ₹1·8 crores | ·85 | ₹1·8 crores | ·90 |
| 2 | ₹2·0 crores | ·75 | ₹1·8 crores | ·85 |
| 3 | ₹2·0 crores | ·60 | ₹2·0 crores | ·75 |
The PVF for 3 years:
| Year 1 | Year 2 | Year 3 | |
|---|---|---|---|
| PVF @ 8% | ·926 | ·857 | ·794 |
| PVF @ 10% | ·909 | ·826 | ·751 |
| PVF @ 12% | ·893 | ·797 | ·712 |
From these details, determine which of the two projects should be accepted by using— risk-adjusted discount rate method;
certainty equivalent approach method. 20 marks
What is credit policy? Explain the criteria involved in assessing the credit-worthiness of a customer. 15 marks
Discuss the phases of operating procedures of monetary policy framework in India. 15 marks
हिंदी में प्रश्न पढ़ें
जैनिथ एंटरप्राइजेज लिमिटेड के पास निवेश के दो प्रस्ताव हैं—परियोजना X और परियोजना Y। ये परस्पर अन्य हैं। परियोजना X के लिए ₹ 3·4 करोड़ की आरंभिक लागत की आवश्यकता होती है और परियोजना Y के लिए ₹ 3·3 करोड़ की आरंभिक लागत की जरूरत होती है। दोनों परियोजनाओं के लिए जोखिम-मुक्त दर 8% है। परियोजना X के लिए जोखिम प्रीमियम दर 2% है और परियोजना Y के लिए 4% है।
दोनों परियोजनाओं के प्रत्याशित रोकड़ अंतर्वाह और निश्चितता तुल्यमान गुणांक नीचे दिए गए हैं :
3 वर्षों के लिए पी. वी. एफ. :
वर्ष 1 वर्ष 2 वर्ष 3 पी. वी. एफ. @ 8% ·926 ·857 ·794 पी. वी. एफ. @ 10% ·909 ·826 ·751 पी. वी. एफ. @ 12% ·893 ·797 ·712
इन विस्तृत विवरणों से निर्धारित कीजिए कि— जोखिम-समायोजित छूट दर विधि (रिस्क-एडजस्टेड डिस्काउंट रेट मेथड);
निश्चितता तुल्यमान दृष्टिकोण विधि (सर्टेन्टी इक्विवेलेंट अप्रोच मेथड); का उपयोग करके दोनों परियोजनाओं में से कौन-सी परियोजना स्वीकार की जानी चाहिए। (20 अंक)
साख नीति क्या है? एक ग्राहक की उधार-पात्रता का आकलन करने में शामिल मानदंडों को समझाइए। (15 अंक)
भारत में मौद्रिक नीति ढांचे की परिचालन-प्रक्रिया के चरणों की विवेचना कीजिए। (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Table 1 (The expected cash inflow and certainty equivalent coefficient for projects): Year | Project X Expected Cash Inflow | Project X CE | Project Y Expected Cash Inflow | Project Y CE 1 | ₹ 1.8 crores | .85 | ₹ 1.8 crores | .90 2 | ₹ 2.0 crores | .75 | ₹ 1.8 crores | .85 3 | ₹ 2.0 crores | .60 | ₹ 2.0 crores | .75
Table 2 (The PVF for 3 years): Rate | Year 1 | Year 2 | Year 3 PVF @ 8% | .926 | .857 | .794 PVF @ 10% | .909 | .826 | .751 PVF @ 12% | .893 | .797 | .712
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Choice between mutually exclusive projects X and Y
Cash inflows are taken at year end. All figures are in ₹ crore.
(i) Risk-adjusted discount rate (RADR) method. RADR = risk-free rate + risk premium: X = 8% + 2% = 10%; Y = 8% + 4% = 12%. Expected inflows are discounted at the project's own RADR.
- Project X at 10%: 1.8 × 0.909 = 1.6362; 2.0 × 0.826 = 1.6520; 2.0 × 0.751 = 1.5020. PV = 4.7902. NPV = 4.7902 − 3.4 = 1.3902.
- Project Y at 12%: 1.8 × 0.893 = 1.6074; 1.8 × 0.797 = 1.4346; 2.0 × 0.712 = 1.4240. PV = 4.4660. NPV = 4.4660 − 3.3 = 1.1660.
NPV of X is higher, so X is chosen by this method.
(ii) Certainty equivalent (CE) method. Each expected inflow is multiplied by its CE coefficient and the certain flows are discounted at the risk-free rate of 8%.
- Project X: 1.8 × 0.85 = 1.530 × 0.926 = 1.4168; 2.0 × 0.75 = 1.500 × 0.857 = 1.2855; 2.0 × 0.60 = 1.200 × 0.794 = 0.9528. PV = 3.6551. NPV = 3.6551 − 3.4 = 0.2551.
- Project Y: 1.8 × 0.90 = 1.620 × 0.926 = 1.5001; 1.8 × 0.85 = 1.530 × 0.857 = 1.3112; 2.0 × 0.75 = 1.500 × 0.794 = 1.1910. PV = 4.0023. NPV = 4.0023 − 3.3 = 0.7023.
NPV of Y is higher, so Y is chosen by this method.
The two methods conflict. RADR puts all risk into the rate and so penalises later cash flows more, whereas the CE method treats risk in the cash flows and time value separately. As CE coefficients are management's direct estimates of risk for each year, Y, which has the higher NPV by CE, is the better choice if those estimates are accepted.
(b) Credit policy and assessing a customer's credit-worthiness
A credit policy is the set of rules by which a firm decides whom to give credit, on what terms and how to collect. It has four parts: credit standards, credit terms (period and cash discount), credit analysis and collection policy. It balances higher sales and profit against the cost of funds locked in receivables and the risk of bad debts.
The credit-worthiness of a customer is assessed through the five Cs:
- Character: willingness to pay, judged from payment record, trade and bank references and reputation.
- Capacity: ability to pay from cash flows, judged from earnings, liquidity, order book and debt-service cover.
- Capital: financial strength, judged from net worth, capital structure and profitability.
- Collateral: security that can be realised if the customer defaults.
- Conditions: the state of the economy and industry, competition and regulation.
These are supported by credit ratings, the CIBIL score, ratio analysis, ageing of past dues and references. Credit is extended only when the profit on the additional sales exceeds the cost of funds, collection and expected default loss.
(c) Phases of operating procedures of India's monetary policy framework
- Monetary targeting (to 1997–98): broad money (M3) was the intermediate target and reserve money the operating target. The tools were CRR, SLR, administered interest rates and selective credit controls. Financial liberalisation weakened the money-income link.
- Multiple indicator approach (1998–99 to 2013–14): the RBI watched interest rates, credit, output, inflation, the exchange rate and capital flows. The Liquidity Adjustment Facility (repo and reverse repo, from 2000) became the main operating tool, with open market operations, the Marginal Standing Facility (from 2011) and CRR.
- Flexible inflation targeting (from 2015–16, statutory in 2016 by the RBI Act amendment): the Monetary Policy Committee fixes the policy repo rate to meet a CPI inflation target of 4% with a ±2% band (retained for April 2026 to March 2031). The operating target is the weighted average call money rate, kept within a corridor bounded by the Standing Deposit Facility rate (floor, since 2022) and the MSF rate (ceiling), using LAF, variable-rate repos and OMOs.
How this answer will be evaluated
Framework: Risk-Adjusted Discount Rate (RADR) and Certainty Equivalent (CE) Approach
What earns full marks: All calculations correct with clear workings; comprehensive theory with examples; precise policy discussion with current context
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Determine project acceptance using RADR and CE methods. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Calculate RADR (8% + risk premium) for each project
- Compute NPV for both projects using RADR method
- Compute NPV for both projects using CE method
- State the decision under each method (X by RADR, Y by CE) and comment on the conflict
Loses marks
- Uses wrong discount rate for either project
- Fails to apply CE coefficients to cash flows
- Ignores initial outlay in NPV calculation
Earns more
- Correctly identifies mutually exclusive nature
- Uses provided PVF table accurately
- Shows step-by-step discounting calculations
- Compares NPVs of both methods
Extra mark
- Mentions IRR as alternative check
- Notes sensitivity to risk premium assumptions
- (b) Define credit policy and explain credit-worthiness criteria. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Define credit policy as a set of guidelines
- List 5C's or similar credit assessment criteria
- Explain each criterion with brief context
- Link criteria to customer risk assessment
Loses marks
- Confuses credit policy with credit terms
- Lists criteria without explaining their relevance
- Ignores the 'customer' aspect of credit-worthiness
Earns more
- Mention specific credit scoring models
- Reference legal/regulatory framework for credit
- Give example of credit policy application
- Discuss impact of credit policy on business
Extra mark
- Cites specific credit rating agency methodology
- References RBI guidelines on credit assessment
- (c) Discuss phases of India's monetary policy operating procedures. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Identify key phases of monetary policy implementation
- Explain role of RBI in each phase
- Mention tools used (repo rate, CRR, SLR, OMOs)
- Name the operating target (weighted average call rate) and the policy corridor (SDF, repo, MSF)
Loses marks
- Confuses monetary policy with fiscal policy
- Ignores the 'operating procedures' aspect
- Fails to mention RBI's central role
Earns more
- References MPC (Monetary Policy Committee) decisions
- Mentions inflation targeting framework
- Discusses liquidity management techniques
- Notes coordination with fiscal policy
Extra mark
- Cites specific RBI circulars or policy statements
- References historical monetary policy shifts
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…
- Q6 (a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. The…
- Q7 (a) XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the followin…
- Q8 (a) A company has a capital of ₹ 100 crores with shares of ₹ 100 each. The shares are cur…