Paper I — Q3
(a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaining to the year ending 31st March…
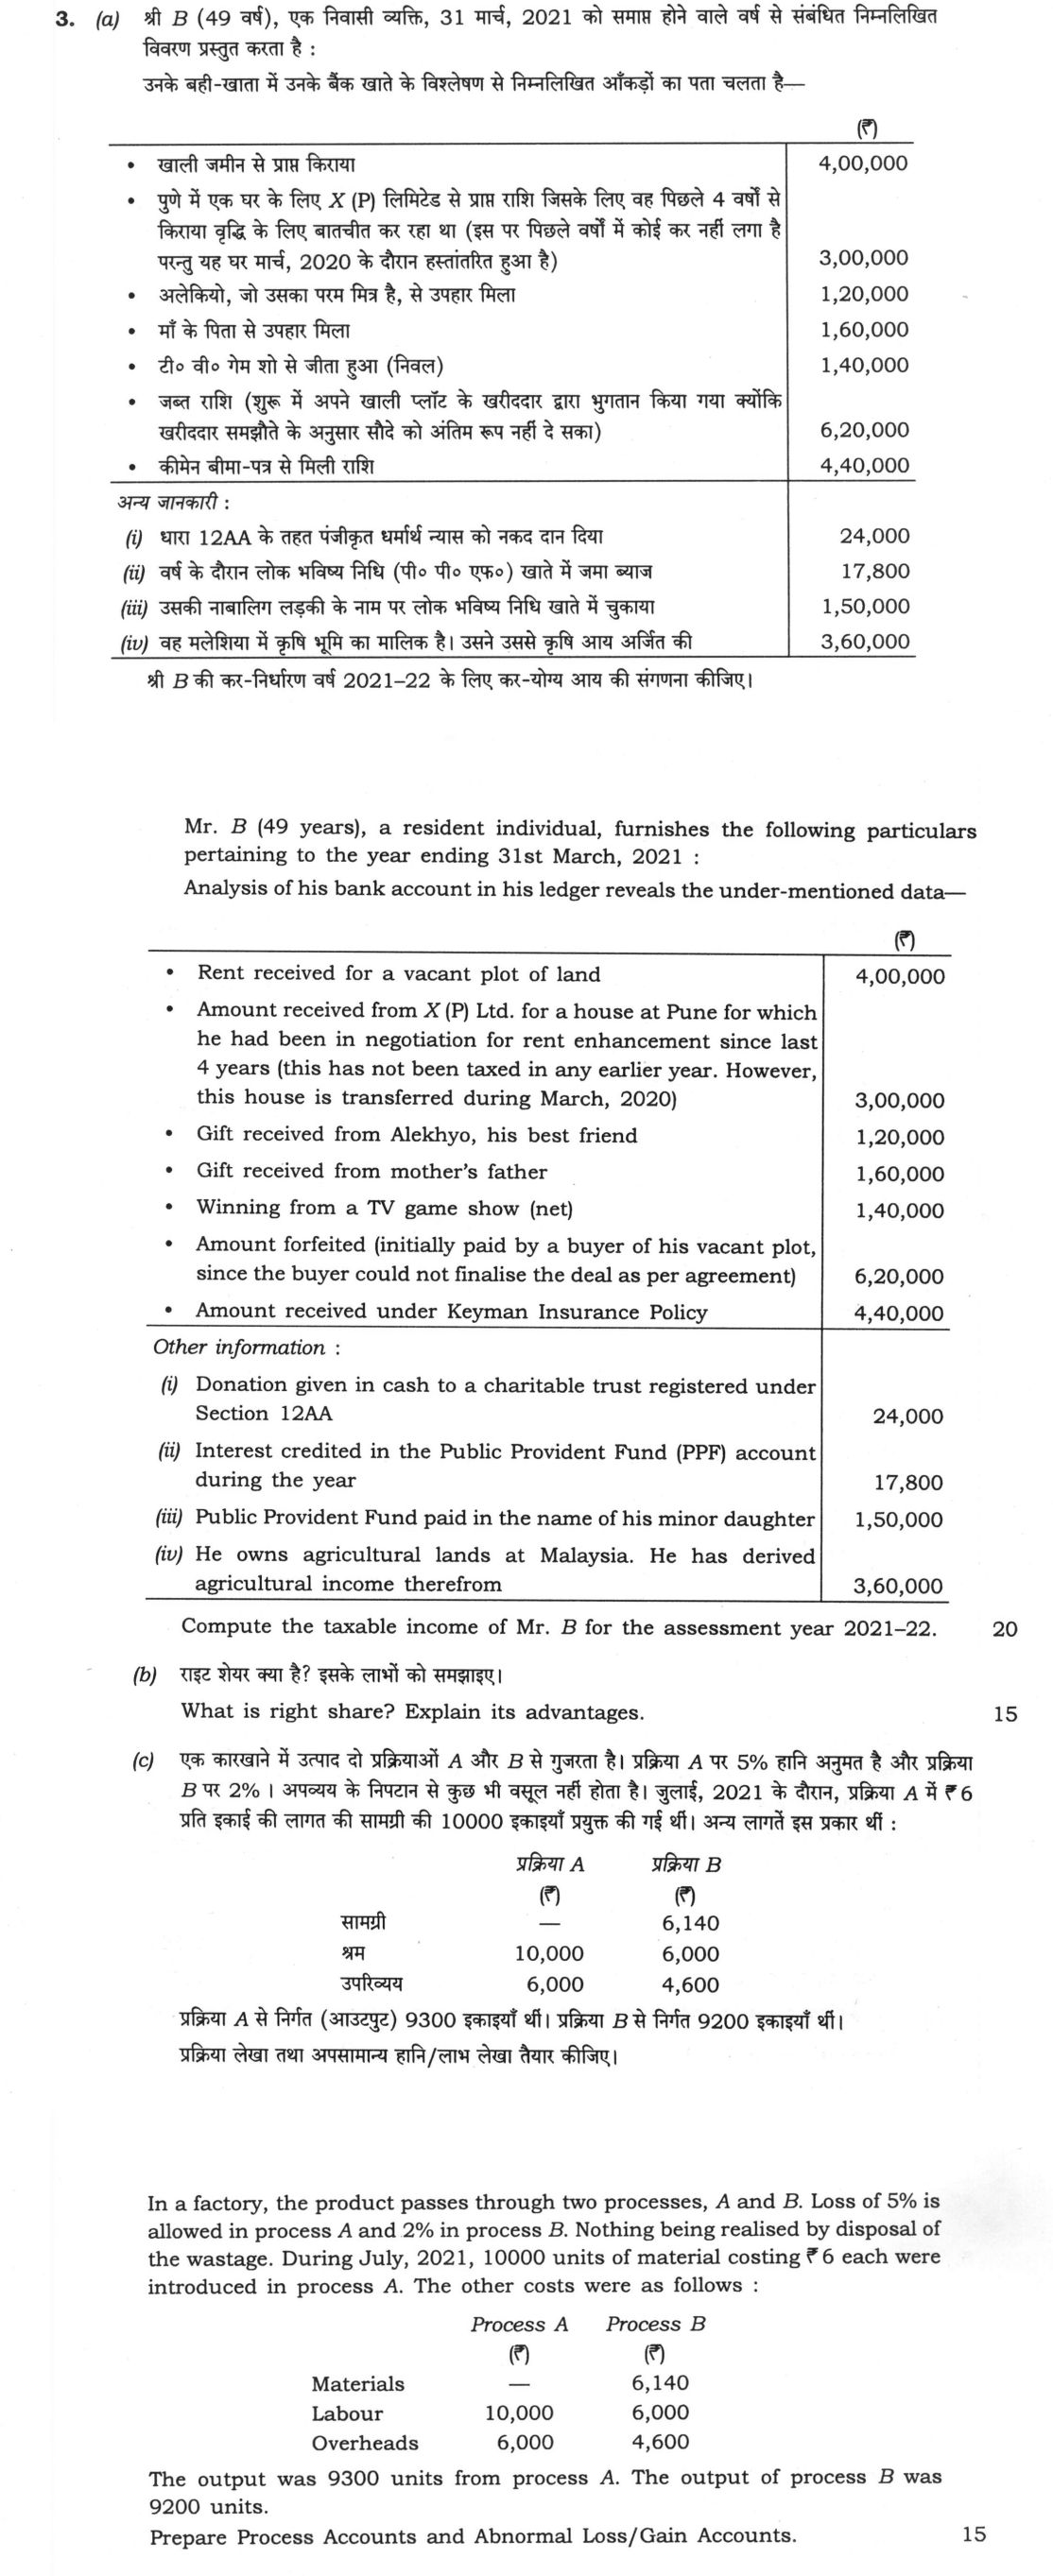
Mr. B (49 years), a resident individual, furnishes the following particulars pertaining to the year ending 31st March, 2021:
Analysis of his bank account in his ledger reveals the under-mentioned data—(₹) • Rent received for a vacant plot of land 4,00,000 • Amount received from X (P) Ltd. for a house at Pune for which he had been in negotiation for rent enhancement since last 4 years (this has not been taxed in any earlier year. However, this house is transferred during March, 2020) 3,00,000 • Gift received from Alekhyo, his best friend 1,20,000 • Gift received from mother's father 1,60,000 • Winning from a TV game show (net) 1,40,000 • Amount forfeited (initially paid by a buyer of his vacant plot, since the buyer could not finalise the deal as per agreement) 6,20,000 • Amount received under Keyman Insurance Policy 4,40,000
Other information: Donation given in cash to a charitable trust registered under Section 12AA 24,000
Interest credited in the Public Provident Fund (PPF) account during the year 17,800
Public Provident Fund paid in the name of his minor daughter 1,50,000
He owns agricultural lands at Malaysia. He has derived agricultural income therefrom 3,60,000
Compute the taxable income of Mr. B for the assessment year 2021–22. 20 marks
What is right share? Explain its advantages. 15 marks
In a factory, the product passes through two processes, A and B. Loss of 5% is allowed in process A and 2% in process B. Nothing being realised by disposal of the wastage. During July, 2021, 10000 units of material costing ₹6 each were introduced in process A. The other costs were as follows:
Process A Process B (₹) (₹) Materials — 6,140 Labour 10,000 6,000 Overheads 6,000 4,600
The output was 9300 units from process A. The output of process B was 9200 units.
Prepare Process Accounts and Abnormal Loss/Gain Accounts. 15 marks
हिंदी में प्रश्न पढ़ें
श्री B (49 वर्ष), एक निवासी व्यक्ति, 31 मार्च, 2021 को समाप्त होने वाले वर्ष से संबंधित निम्नलिखित विवरण प्रस्तुत करता है:
उनके बही-खाता में उनके बैंक खाते के विवरणों से निम्नलिखित आँकड़ों का पता चलता है—(₹) • खाली जमीन से प्राप्त किराया 4,00,000 • पुणे में एक घर के लिए X (P) लिमिटेड से प्राप्त राशि जिसके लिए वह पिछले 4 वर्षों से किराया वृद्धि के लिए बातचीत कर रहा था (इस पर पिछले वर्षों में कोई कर नहीं लगा है परंतु यह घर मार्च, 2020 के दौरान हस्तांतरित हुआ है) 3,00,000 • अलैकियो, जो उसका परम मित्र है, से उपहार मिला 1,20,000 • माँ के पिता से उपहार मिला 1,60,000 • टी० वी० गेम शो से जीता हुआ (निवल) 1,40,000 • जब्त राशि (शुक्ल ने अपने खाली प्लॉट के खरीददार द्वारा भुगतान किया गया क्योंकि खरीददार समझौते के अनुसार सौदे को अंतिम रूप नहीं दे सका) 6,20,000 • कीमेन बीमा-पत्र से मिली राशि 4,40,000
अन्य जानकारी: धारा 12AA के तहत पंजीकृत धर्मार्थ न्यास को नकद दान दिया 24,000
वर्ष के दौरान लोक भविष्य निधि (पी० पी० एफ०) खाते में जमा ब्याज 17,800
उसकी नाबालिग लड़की के नाम पर लोक भविष्य निधि खाते में चुकाया 1,50,000
वह मलेशिया में कृषि भूमि का मालिक है। उसने उससे कृषि आय अर्जित की 3,60,000
श्री B की कर-निर्धारण वर्ष 2021-22 के लिए कर-योग्य आय की संगणना कीजिए। (20 अंक)
राइट शेयर क्या है? इसके लाभों को समझाइए। (15 अंक)
एक कारखाने में उत्पाद दो प्रक्रियाओं A और B से गुजरता है। प्रक्रिया A पर 5% हानि अनुमत है और प्रक्रिया B पर 2%। अपव्यय के निपटान से कुछ भी वसूल नहीं होता है। जुलाई, 2021 के दौरान, प्रक्रिया A में ₹6 प्रति इकाई की लागत की सामग्री की 10000 इकाइयाँ प्रयुक्त की गई थीं। अन्य लागतें इस प्रकार थीं:
प्रक्रिया A प्रक्रिया B (₹) (₹) सामग्री — 6,140 श्रम 10,000 6,000 उपरिव्यय 6,000 4,600
प्रक्रिया A से निर्गत (आउटपुट) 9300 इकाइयाँ थीं। प्रक्रिया B से निर्गत 9200 इकाइयाँ थीं।
प्रक्रिया लेखा तथा अपसामान्य हानि/लाभ लेखा तैयार कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Taxable income of Mr. B for AY 2021–22
Assumptions: a resident individual aged 49 under the old regime; the plot is a capital asset; no expenses are claimed on rent; the game-show winnings are net of 30% TDS.
- Rent from the vacant plot, ₹4,00,000: vacant land is not a building, so it is not house property; it is taxed under income from other sources, ₹4,00,000.
- ₹3,00,000 from X (P) Ltd.: arrears of rent received, not taxed earlier, are charged as house property income in the year of receipt, even though the house was sold earlier (Section 25A). Less 30%: ₹2,10,000.
- Gift from friend, ₹1,20,000: not from a relative and above ₹50,000, so wholly taxable under Section 56(2)(x): ₹1,20,000.
- Gift from mother's father, ₹1,60,000: a lineal ascendant is a relative, so exempt.
- Game-show winnings: gross = 1,40,000 × 100/70 = ₹2,00,000, taxed at a flat 30% under Section 115BB, with no deduction; TDS of ₹60,000 is credited (Section 194B).
- Forfeited advance, ₹6,20,000: taxable under Section 56(2)(ix), as the negotiation for transfer of the plot failed: ₹6,20,000.
- Keyman policy, ₹4,40,000: Section 10(10D) excludes Keyman policies, so it is taxable under Section 56(2)(iv): ₹4,40,000.
- Agricultural income in Malaysia, ₹3,60,000: Section 10(1) exempts only income from land in India, so it is taxable, here under other sources: ₹3,60,000.
- PPF interest, ₹17,800: exempt under Section 10(11).
Gross total income = 2,10,000 + 4,00,000 + 1,20,000 + 2,00,000 + 6,20,000 + 4,40,000 + 3,60,000 = ₹23,50,000.
Deductions: Section 80C for PPF in the minor daughter's name, ₹1,50,000 (a child's account qualifies up to the limit). The cash donation of ₹24,000 earns no Section 80G deduction, because cash above ₹2,000 does not qualify.
Taxable income = ₹22,00,000, of which ₹2,00,000 (winnings) is taxed at 30%.
(b) Right share and its advantages
A right share is a new equity share offered by a company to its existing equity shareholders in proportion to their holding, usually below the market price. Under Section 62(1)(a) of the Companies Act, 2013, the offer is open for 15 to 30 days, and a shareholder may accept it, renounce it in favour of another person, or let it lapse; listed companies also follow the SEBI (ICDR) Regulations.
Advantages to the company:
- It raises equity quickly and cheaply, with no prospectus or underwriting, and so costs less than a public issue.
- It keeps control with existing shareholders.
- It lowers the debt-equity ratio and raises borrowing capacity.
- It needs only a small marketing effort, as a loyal shareholder base is already there.
Advantages to shareholders:
- They keep their proportionate ownership, voting power and share in reserves.
- They can buy at a discount to market price.
- They can renounce the right and sell it, which has a market value.
- There is no tax on receiving the right; tax arises only on sale or renunciation.
(c) Process accounts
Process A (units, ₹). Cost = materials 10,000 × 6 = 60,000 + labour 10,000 + overheads 6,000 = 76,000. Normal loss is 5% of 10,000 = 500 units with nil value, so normal output is 9,500 and cost per unit is 76,000/9,500 = ₹8. Actual output of 9,300 gives an abnormal loss of 200 units, valued at 200 × 8 = ₹1,600.
- Debit side: materials 10,000 units 60,000; labour 10,000; overheads 6,000. Total 76,000.
- Credit side: normal loss 500 units nil; abnormal loss 200 units 1,600; transferred to Process B 9,300 units 74,400. Total 76,000.
Process B. Cost = 74,400 + 6,140 + 6,000 + 4,600 = 91,140. Normal loss is 2% of 9,300 = 186 units, so normal output is 9,114 and cost per unit is 91,140/9,114 = ₹10. Actual output of 9,200 gives an abnormal gain of 86 units, valued at ₹860.
- Debit side: from Process A 9,300 units 74,400; materials 6,140; labour 6,000; overheads 4,600; abnormal gain 86 units 860. Total 92,000.
- Credit side: normal loss 186 units nil; finished goods 9,200 units 92,000. Total 92,000.
Abnormal Loss A/c: debit Process A ₹1,600 and credit costing profit and loss ₹1,600 (scrap nil). Abnormal Gain A/c: debit costing profit and loss ₹860 and credit Process B ₹860.
How this answer will be evaluated
Framework: Income Tax Act, 1961 (AY 2021-22) & Cost Accounting (Process Costing)
What earns full marks: All parts fully answered with correct calculations, proper format, and all required elements present
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute taxable income of Mr. B for AY 2021-22 with working notes. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Classify each receipt under the correct head (house property, other sources) or exempt
- Apply Sec 56(2)(x) for gifts from non-relatives
- Tax Keyman policy proceeds under Section 56(2)(iv), since Section 10(10D) excludes them
- Compute final taxable income with correct deductions
Loses marks
- Treating Keyman insurance proceeds as exempt
- Treating foreign agricultural income as exempt
- Failing to apply Sec 56(2)(x) to gifts
Earns more
- Correct treatment of forfeited amount as OI
- Include foreign agricultural income, as Section 10(1) exempts only income from land in India
- Allow no Section 80G deduction for the cash donation above ₹2,000
- Treat PPF interest as exempt (Section 10(11))
Extra mark
- Section 25A treatment of arrears of rent (₹3,00,000 less 30%) and gross-up of net winnings (Sections 194B, 115BB)
- Clear tabular presentation of income computation
- (b) Define right share and explain its advantages. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Define right share as pre-emptive right to existing shareholders
- Explain the mechanism of issuing rights issue
- List at least 3-4 advantages of right share
- Provide brief context of Companies Act provisions
Loses marks
- Confusing right share with bonus share
- Failing to explain pre-emptive nature
- Listing only 1-2 advantages without explanation
Earns more
- Mentioning Sec 62(1) of Companies Act, 2013
- Explaining dilution of ownership protection
- Comparing with public issue advantages
- Mentioning pricing mechanism (discount to market)
Extra mark
- Citing specific Companies Act section number
- Providing numerical example of rights issue calculation
- (c) Prepare Process Accounts and Abnormal Loss/Gain Accounts for A and B. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Prepare Process A account with all cost elements
- Prepare Process B account with all cost elements
- Prepare the Abnormal Loss and Abnormal Gain accounts
- Calculate cost per unit for each process
Loses marks
- Incorrect calculation of abnormal loss/gain units
- Failing to prepare separate Abnormal Loss/Gain accounts
- Wrong cost per unit calculation
Earns more
- Process A: normal loss 500 units and abnormal loss 200 units
- Process B: normal loss 186 units and abnormal gain 86 units
- Proper transfer of abnormal loss/gain to respective accounts
- Accurate cost per unit calculation
Extra mark
- Clear T-format presentation of accounts
- Showing all working calculations separately
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q1 Answer the following questions in about 150 words each: (a) Briefly explain the significa…
- Q2 (a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to ama…
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…
- Q6 (a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. The…