Paper I — Q5
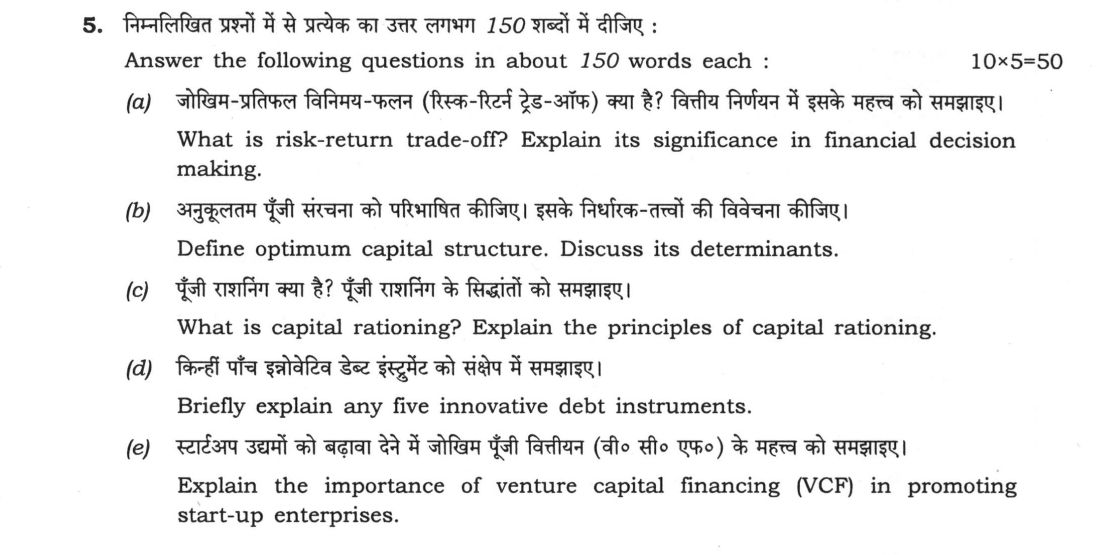
(a) What is risk-return trade-off? Explain its significance in financial decision making. (10 marks) (b) Define optimum capital…
Answer the following questions in about 150 words each: What is risk-return trade-off? Explain its significance in financial decision making. 10 marks
Define optimum capital structure. Discuss its determinants. 10 marks
What is capital rationing? Explain the principles of capital rationing. 10 marks
Briefly explain any five innovative debt instruments. 10 marks
Explain the importance of venture capital financing (VCF) in promoting start-up enterprises. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए : जोखिम-प्रतिफल विनिमय-फलन (रिस्क-रिटर्न ट्रेड-ऑफ) क्या है? वित्तीय निर्णयन में इसके महत्व को समझाइए। (10 अंक)
अनुकूलतम पूँजी संरचना को परिभाषित कीजिए। इसके निर्धारक-तत्वों की विवेचना कीजिए। (10 अंक)
पूँजी राशनिंग क्या है? पूँजी राशनिंग के सिद्धांतों को समझाइए। (10 अंक)
किन्हीं पाँच इनोवेटिव डेट इंस्ट्रूमेंट को संक्षेप में समझाइए। (10 अंक)
स्टार्टअप उद्यमों को बढ़ावा देने में जोखिम पूँजी वित्तियन (वी. सी. एफ.) के महत्व को समझाइए। (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Risk-return trade-off and its significance
The risk-return trade-off states that a higher expected return can be earned only by bearing more risk. Investors are risk averse, so they accept extra risk only for a higher risk premium, and a risk-free asset such as a government security earns the lowest return.
Significance in financial decisions:
- In investment choices, it links the required return to the risk of the asset: through the CAPM, the required return is the risk-free rate plus beta times the market premium.
- In capital budgeting, riskier projects must clear a higher, risk-adjusted discount rate.
- In portfolio selection (Markowitz), diversification gives the best return for a given risk along the efficient frontier.
- In financing, more debt raises the expected return to equity but also its risk, so the mix must balance both and maximise share value.
(b) Optimum capital structure and its determinants
The optimum capital structure is the debt-equity mix that gives the lowest weighted average cost of capital and so the highest value of the firm and of the share. Its determinants are:
- The tax shield, because interest is deductible and reduces the cost of debt.
- The cost of capital: debt is cheaper than equity up to a point beyond which the cost of both rises.
- The risk of financial distress and bankruptcy costs, which rise with debt, as the trade-off theory shows.
- Business risk and the stability of earnings and cash flow, which decide how much fixed interest the firm can carry.
- Financial flexibility and a debt-servicing capacity measured by interest cover and DSCR.
- Control, agency costs, the nature of assets (tangible assets support more debt), industry norms, market conditions and the pecking order of internal funds, then debt, then equity.
(c) Capital rationing and its principles
Capital rationing is the situation where a firm has a limit on the funds for investment and cannot take up all projects with a positive NPV. It is internal (soft) when management sets the budget, and external (hard) when the market or lenders limit the funds.
The principles are:
- Maximise the total NPV within the budget, not just spend it.
- For divisible projects, rank by profitability index (PV of inflows ÷ outlay) and fund in that order until the budget is exhausted.
- For indivisible projects, compare all feasible combinations, or use integer programming, to find the combination with the highest total NPV.
- Where the budget extends over several periods, use linear programming.
- Do not rank by IRR alone, since IRR can mislead for mutually exclusive projects.
(d) Five innovative debt instruments
- Zero-coupon or deep-discount bonds: issued at a large discount, with no interest, the return being the gain at redemption.
- Convertible debentures: they can be converted into equity shares on set terms, giving a lower coupon to the issuer and upside to the investor.
- Floating-rate bonds: the coupon is linked to a benchmark such as the T-bill or MIBOR yield, protecting against interest-rate swings.
- Masala bonds: rupee-denominated bonds sold overseas, so the investor, not the issuer, bears the exchange-rate risk.
- Green bonds: raised to fund environmentally sustainable projects, regulated by SEBI's debt-securities framework.
Others include inflation-indexed bonds, callable and puttable bonds and asset-backed securities.
(e) Importance of venture capital financing for start-ups
Venture capital financing is long-term, high-risk equity funding to young, innovative firms that cannot get bank loans because they lack collateral and track record. It matters to start-ups because it:
- supplies seed, early-stage and growth capital as risk capital without a debt-servicing burden;
- brings management advice, networks, hiring support and governance as well as money;
- helps develop technology, create jobs and scale new business models;
- rewards the investor through exits by an IPO, an acquisition or a buy-back, which encourages risk-taking.
In India, venture funds are registered with SEBI as Category I Alternative Investment Funds, and the Fund of Funds for Startups supports them under the Startup India programme.
How this answer will be evaluated
Framework: Finance Theory
What earns full marks: Precise definitions, clear structure, relevant examples, covers all points.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Define risk-return trade-off and its role in financial decisions. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Define risk-return trade-off
- Explain significance in decision making
- Mention risk aversion
- Link to investment choices
Loses marks
- Confusing risk with uncertainty
- Ignoring the 'trade-off' aspect
Earns more
- Mention CAPM or beta
- Example of high risk asset
- Reference to utility theory
Extra mark
- Reference to Markowitz portfolio theory
- (b) Define optimum capital structure and its determinants. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Define optimum capital structure
- List key determinants
- Mention cost of capital
- Mention tax shield
Loses marks
- Defining it as just 'debt ratio'
- Ignoring the 'optimum' (max value) aspect
Earns more
- Reference to Modigliani-Miller
- Mention financial flexibility
- Mention agency costs
Extra mark
- Reference to pecking order theory
- (c) Define capital rationing and its principles. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Define capital rationing
- Distinguish hard vs soft rationing
- Explain principles of allocation
- Mention NPV ranking
Loses marks
- Confusing with working capital
- Ignoring the 'rationing' (limitation) aspect
Earns more
- Mention linear programming
- Mention internal capital rationing
- Mention external capital rationing
Extra mark
- Example of a specific allocation method
- (d) Briefly explain five innovative debt instruments. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Name five distinct instruments
- Briefly explain each
- Mention convertible bonds
- Mention zero-coupon bonds
Loses marks
- Listing only standard instruments
- Failing to explain the 'innovative' feature
Earns more
- Mention asset-backed securities
- Mention callable bonds
- Mention inflation-indexed bonds
Extra mark
- Mention specific market examples
- (e) Explain importance of VCF in promoting start-ups. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Define VCF
- Explain role in start-up promotion
- Mention equity financing
- Mention mentorship/networking
Loses marks
- Confusing with bank loans
- Ignoring the 'start-up' specific context
Earns more
- Mention stages of funding (Seed, Series A)
- Mention risk capital nature
- Mention exit strategies
Extra mark
- Reference to specific VCF funds
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q2 (a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to ama…
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…
- Q6 (a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. The…
- Q7 (a) XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the followin…
- Q8 (a) A company has a capital of ₹ 100 crores with shares of ₹ 100 each. The shares are cur…