Paper I — Q7
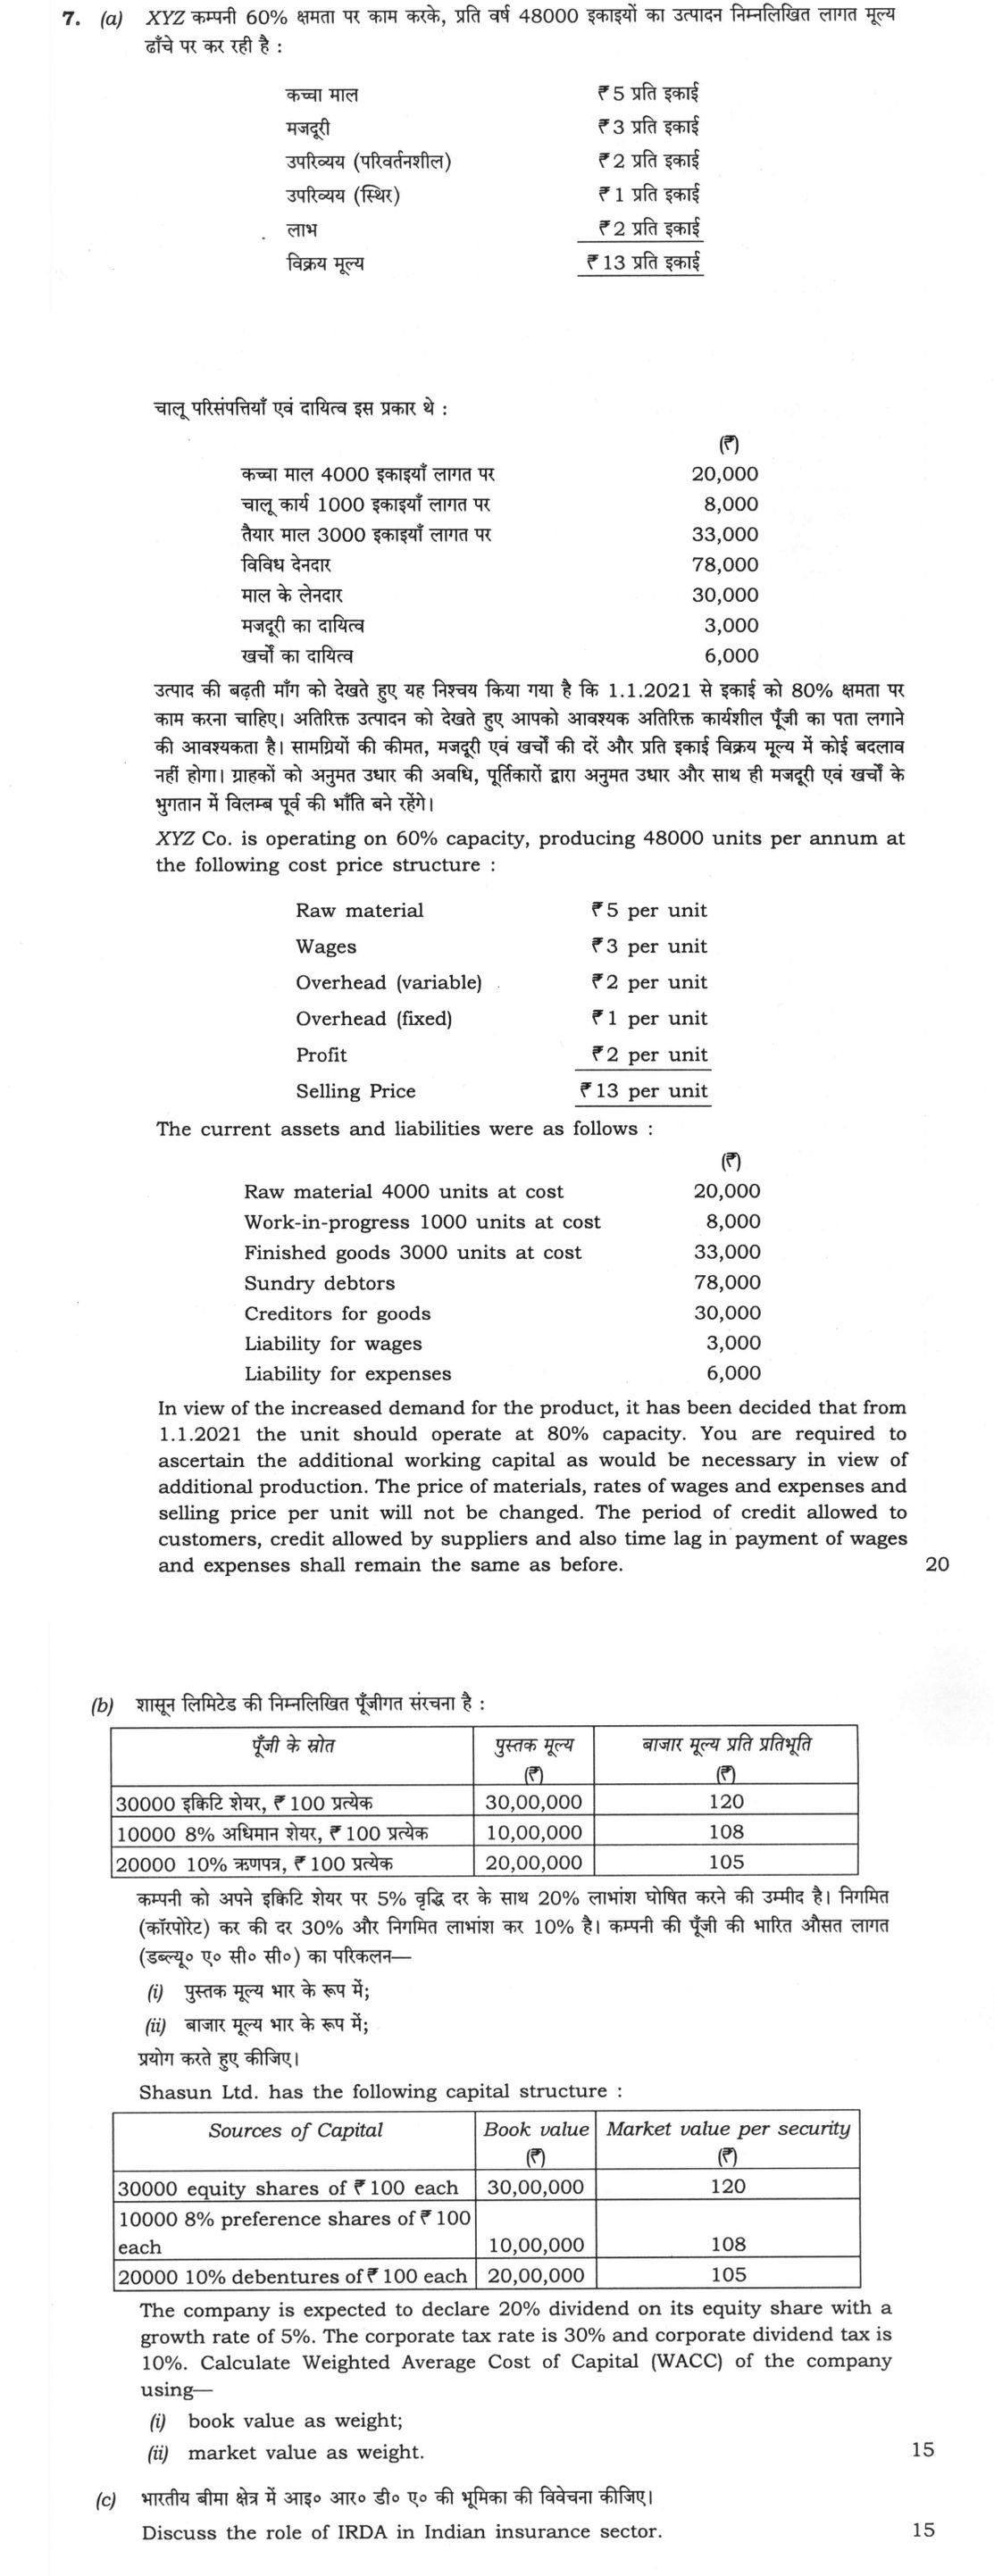
(a) XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the following cost price structure: Raw material ₹5…
XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the following cost price structure:
Raw material ₹5 per unit Wages ₹3 per unit Overhead (variable) ₹2 per unit Overhead (fixed) ₹1 per unit Profit ₹2 per unit Selling Price ₹13 per unit
The current assets and liabilities were as follows:
(₹) Raw material 4000 units at cost 20,000 Work-in-progress 1000 units at cost 8,000 Finished goods 3000 units at cost 33,000 Sundry debtors 78,000 Creditors for goods 30,000 Liability for wages 3,000 Liability for expenses 6,000
In view of the increased demand for the product, it has been decided that from 1.1.2021 the unit should operate at 80% capacity. You are required to ascertain the additional working capital as would be necessary in view of additional production. The price of materials, rates of wages and expenses and selling price per unit will not be changed. The period of credit allowed to customers, credit allowed by suppliers and also time lag in payment of wages and expenses shall remain the same as before. 20 marks
Shasun Ltd. has the following capital structure:
| Sources of Capital | Book value (₹) | Market value per security (₹) |
|---|---|---|
| 30000 equity shares of ₹100 each | 30,00,000 | 120 |
| 10000 8% preference shares of ₹100 each | 10,00,000 | 108 |
| 20000 10% debentures of ₹100 each | 20,00,000 | 105 |
The company is expected to declare 20% dividend on its equity share with a growth rate of 5%. The corporate tax rate is 30% and corporate dividend tax is 10%. Calculate Weighted Average Cost of Capital (WACC) of the company using—
book value as weight;
market value as weight. 15 marks
Discuss the role of IRDA in Indian insurance sector. 15 marks
हिंदी में प्रश्न पढ़ें
XYZ कम्पनी 60% क्षमता पर काम करके, प्रति वर्ष 48000 इकाइयों का उत्पादन निम्नलिखित लागत मूल्य ढांचे पर कर रही है :
कच्चा माल ₹5 प्रति इकाई मजदूरी ₹3 प्रति इकाई उपरिव्यय (परिवर्तनशील) ₹2 प्रति इकाई उपरिव्यय (स्थिर) ₹1 प्रति इकाई लाभ ₹2 प्रति इकाई विक्रय मूल्य ₹13 प्रति इकाई
चालू परिसम्पतियाँ एवं दायित्व इस प्रकार थे :
(₹) कच्चा माल 4000 इकाइयाँ लागत पर 20,000 चालू कार्य 1000 इकाइयाँ लागत पर 8,000 तैयार माल 3000 इकाइयाँ लागत पर 33,000 विविध देनदार 78,000 माल के लेनदार 30,000 मजदूरी का दायित्व 3,000 खर्चों का दायित्व 6,000
उत्पाद की बढ़ती माँग को देखते हुए यह निश्चय किया गया है कि 1.1.2021 से इकाई को 80% क्षमता पर काम करना चाहिए। अतिरिक्त उत्पादन को देखते हुए आपको आवश्यक अतिरिक्त कार्यशील पूँजी का पता लगाने की आवश्यकता है। सामग्रियों की कीमत, मजदूरी एवं खर्चों की दरें और प्रति इकाई विक्रय मूल्य में कोई बदलाव नहीं होगा। ग्राहकों को अनुमत उधार की अवधि, पूर्तिकारों द्वारा अनुमत उधार और साथ ही मजदूरी एवं खर्चों के भुगतान में विलम्ब पूर्व की भाँति बने रहेंगे। 20 अंक
शासुन लिमिटेड की निम्नलिखित पूँजीगत संरचना है :
| पूँजी के स्रोत | पुस्तक मूल्य (₹) | बाजार मूल्य प्रति प्रतिभूति (₹) |
|---|---|---|
| 30000 इकिटी शेयर, ₹ 100 प्रत्येक | 30,00,000 | 120 |
| 10000 8% अधिमान शेयर, ₹ 100 प्रत्येक | 10,00,000 | 108 |
| 20000 10% ऋणपत्र, ₹ 100 प्रत्येक | 20,00,000 | 105 |
कम्पनी को अपने इकिटी शेयर पर 5% वृद्धि दर के साथ 20% लाभांश घोषित करने की उम्मीद है। निगमित (कॉरपोरेट) कर की दर 30% और निगमित लाभांश कर 10% है। कम्पनी की पूँजी की भारित औसत लागत (डब्ल्यू० ए० सी० सी०) का परिकलन—
पुस्तक मूल्य भार के रूप में;
बाजार मूल्य भार के रूप में;
प्रयोग करते हुए कीजिए। 15 अंक
भारतीय बीमा क्षेत्र में आई० आर० डी० ए० की भूमिका की विवेचना कीजिए। 15 अंक
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Additional working capital at 80% capacity
Full capacity = 48,000/0.60 = 80,000 units, so 80% capacity = 64,000 units (a rise of 4/3 over the present output). Fixed overhead is taken as constant at 48,000 × ₹1 = ₹48,000, so at 64,000 units it falls to ₹0.75 per unit.
Holding periods implied by the present figures:
- Raw material 4,000/48,000 = 1 month; work in progress 1,000/48,000 = 0.25 month; finished goods 3,000/48,000 = 0.75 month.
- Debtors 78,000/(48,000 × 13) = 1.5 months (at selling price); creditors 30,000/(48,000 × 5) = 1.5 months.
- Wages lag 3,000/(48,000 × 3) = 0.25 month; expenses lag 6,000/(48,000 × 3) = 0.5 month.
Current assets at 80%:
- Raw material: 64,000 × 5 × 1/12 = ₹26,667
- Work in progress (material and wages, ₹8 per unit): 64,000 × 8 × 1/48 = ₹10,667
- Finished goods (5 + 3 + 2 + 0.75 = ₹10.75 per unit): 64,000 × 10.75 × 1/16 = ₹43,000
- Debtors: 64,000 × 13 × 1/8 = ₹1,04,000
Total = ₹1,84,333.
Current liabilities at 80%:
- Creditors: 64,000 × 5 × 1/8 = ₹40,000
- Wages: 64,000 × 3 × 1/48 = ₹4,000
- Expenses (variable 1,28,000 + fixed 48,000 = 1,76,000) × 1/24 = ₹7,333
Total = ₹51,333.
Working capital needed = 1,84,333 − 51,333 = ₹1,33,000. Present working capital = 1,39,000 − 39,000 = ₹1,00,000.
Additional working capital = ₹33,000. (If the fixed overhead rate of ₹1 per unit were held instead, the answer would be ₹33,333.)
(b) Weighted average cost of capital of Shasun Ltd.
Component costs use market prices, and the 10% corporate dividend tax (CDT, as stated in the question) is added to dividends.
- Equity: Ke = D₁(1 + 0.10)/P₀ + g = 20 × 1.10/120 + 0.05 = 0.1833 + 0.05 = 23.33%.
- Preference: Kp = 8 × 1.10/108 = 8.80/108 = 8.15%.
- Debentures: Kd = 10 × (1 − 0.30)/105 = 7/105 = 6.67%.
(i) Book value weights (equity ₹30 lakh, preference ₹10 lakh, debentures ₹20 lakh; total ₹60 lakh): 0.5, 0.1667, 0.3333.
WACC = 0.5 × 23.33 + 0.1667 × 8.15 + 0.3333 × 6.67 = 11.67 + 1.36 + 2.22 = 15.25%.
(ii) Market value weights (equity 30,000 × 120 = ₹36 lakh; preference 10,000 × 108 = ₹10.8 lakh; debentures 20,000 × 105 = ₹21 lakh; total ₹67.8 lakh): 0.5310, 0.1593, 0.3097.
WACC = 0.5310 × 23.33 + 0.1593 × 8.15 + 0.3097 × 6.67 = 12.39 + 1.30 + 2.06 = 15.75%.
Market weights are preferred, as they reflect current investor values. CDT was abolished from 1 April 2020.
(c) Role of IRDA in the Indian insurance sector
The Insurance Regulatory and Development Authority of India (IRDAI) is the statutory regulator under the IRDA Act, 1999, set up to protect policyholders, regulate the industry and promote its orderly growth. Its roles are:
- Regulatory: registering and licensing insurers, brokers, agents, surveyors and other intermediaries, and framing regulations under the Insurance Act, 1938.
- Protective: laying down claim-settlement time limits, grievance redressal, fair disclosure and the insurance ombudsman, and checking unfair practices.
- Prudential: supervising solvency margins, capital, investment norms, reserves and the formats of accounts and audit.
- Product and pricing oversight, including approval or file-and-use of products and regulation of premium and commission.
- Developmental: promoting competition, rural and social-sector cover, microinsurance, and health, crop and pension products, and spreading awareness.
- Supervisory and enforcement: inspection, directions, penalties, and action against defaulting insurers.
- Advisory: guiding the government and coordinating with the RBI and SEBI.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Complete workings with correct final figures; clear structure; all components addressed
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Calculate additional working capital required for 80% capacity operation. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Determine production volume at 80% capacity (64,000 units)
- Calculate current assets at 80% capacity
- Calculate current liabilities at 80% capacity
- Compute difference between 80% and 60% working capital
Loses marks
- Fails to scale all items to 80% capacity
- Ignores fixed overheads in finished goods valuation
- Changes credit periods without justification
Earns more
- Correctly identifies fixed vs variable overheads
- Maintains same credit periods as given
- Shows working notes for each component
- Presents final statement clearly
Extra mark
- Notes assumption about fixed overheads remaining constant
- Provides summary table of changes
- (b) Calculate WACC using book value and market value weights. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Cost of equity = D₁(1 + CDT)/P₀ + g = 22/120 + 5% = 23.33%
- Cost of preference shares = 8.80/108 = 8.15% (dividend grossed up for CDT)
- Calculate after-tax cost of debentures (10% × 0.7)
- Compute WACC using both book and market value weights
Loses marks
- Forgets to adjust debenture cost for tax
- Uses wrong weights in WACC calculation
- Confuses book and market value calculations
Earns more
- Shows separate working for each component cost
- Presents WACC calculation in tabular form
- Clearly distinguishes between the two methods
- States final WACC for both approaches
Extra mark
- Notes that market value WACC is more relevant
- Provides interpretation of the difference
- (c) Discuss the role of IRDA in Indian insurance sector. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Define IRDA and its statutory basis
- Explain regulatory functions (licensing, standards)
- Describe protective functions (policyholder interests)
- Mention developmental role (market growth, innovation)
Loses marks
- Vague generalities without specific functions
- Ignores protective role for policyholders
- No structure or logical flow
Earns more
- References IRDA Act 1999
- Gives specific examples of regulations
- Balances regulatory and developmental aspects
- Concludes with current relevance
Extra mark
- Mentions specific recent initiatives (e.g., IRDAI reforms)
- References specific sections of IRDA Act
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…
- Q6 (a) The Zenith Enterprises Ltd. has two investment proposals—project X and project Y. The…
- Q7 (a) XYZ Co. is operating on 60% capacity, producing 48000 units per annum at the followin…
- Q8 (a) A company has a capital of ₹ 100 crores with shares of ₹ 100 each. The shares are cur…