Paper I — Q2
(a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to amalgamate and a new company XY Ltd. is to…
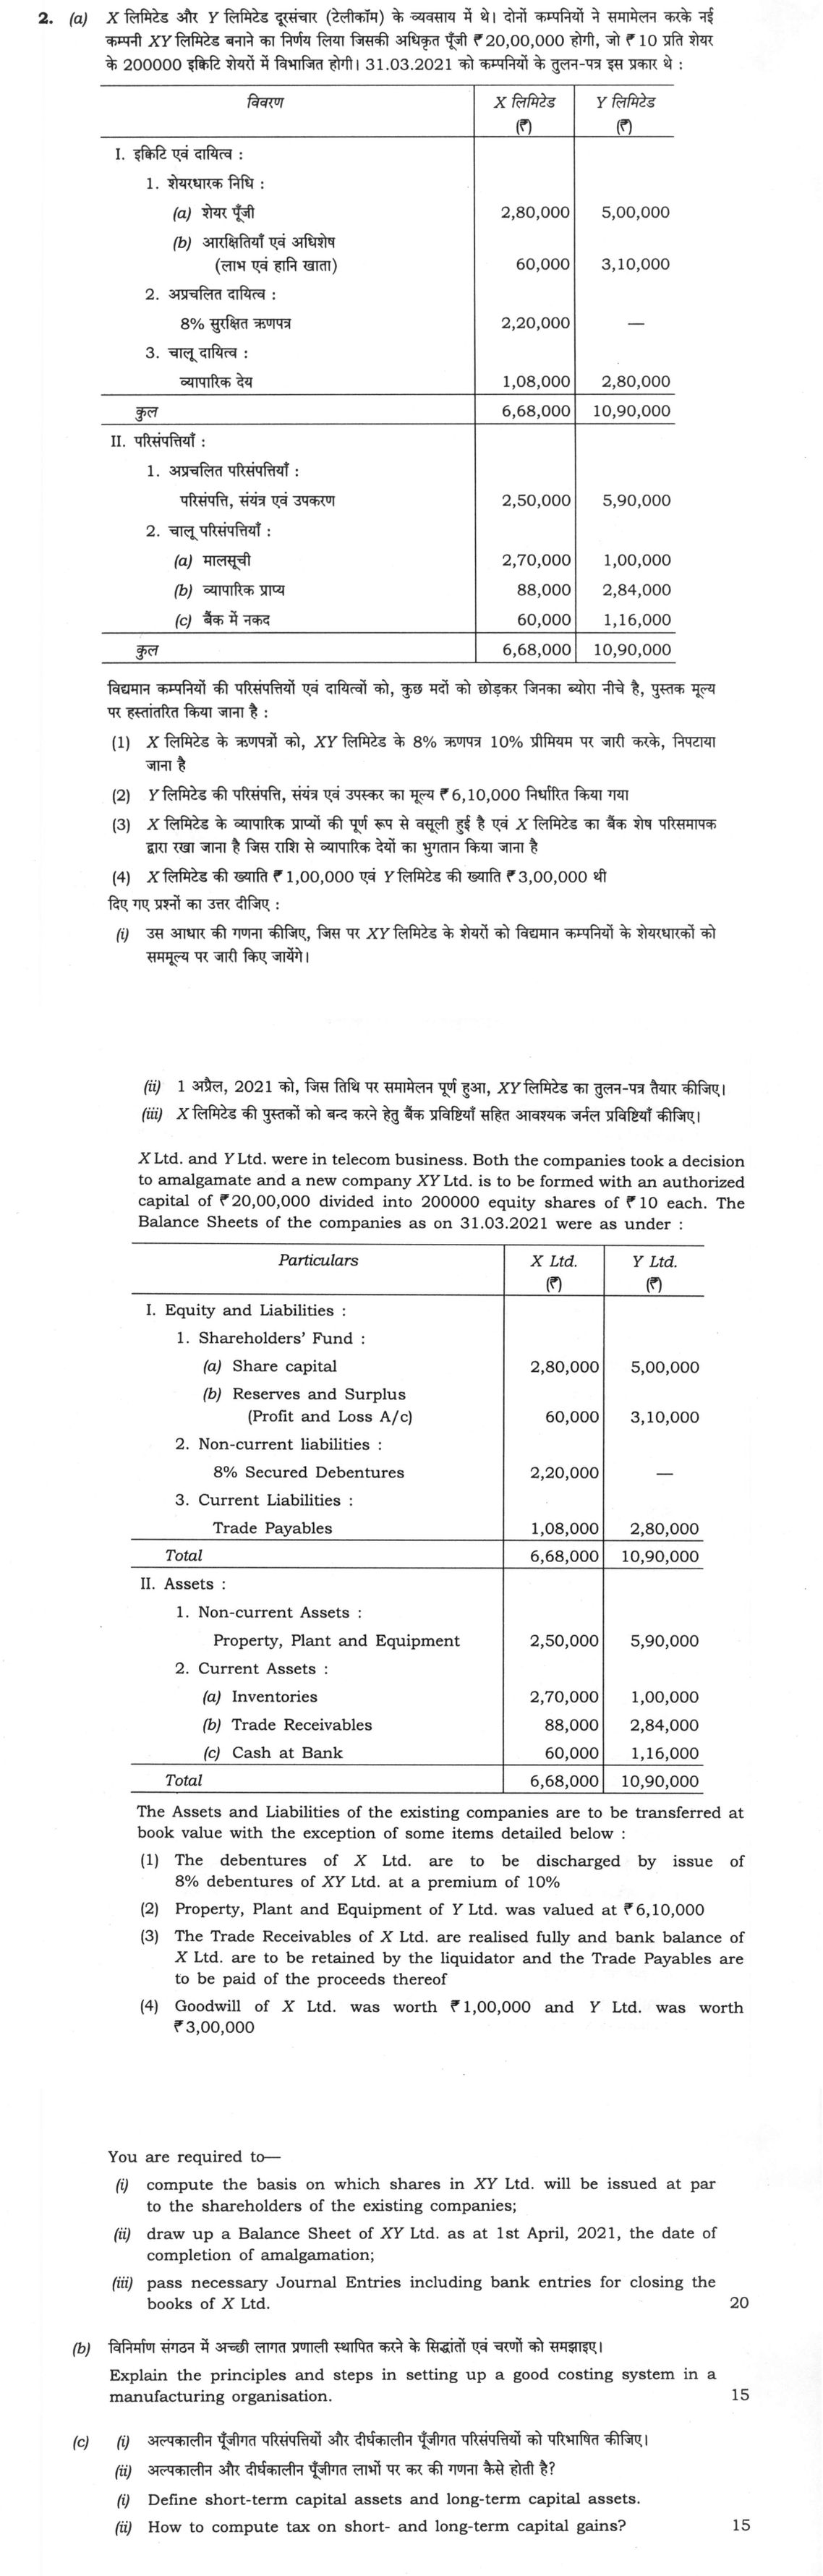
X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to amalgamate and a new company XY Ltd. is to be formed with an authorized capital of ₹ 20,00,000 divided into 200000 equity shares of ₹ 10 each. The Balance Sheets of the companies as on 31.03.2021 were as under :
Particulars | X Ltd. (₹) | Y Ltd. (₹) I. Equity and Liabilities : 1. Shareholders' Fund :
Share capital | 2,80,000 | 5,00,000
Reserves and Surplus (Profit and Loss A/c) | 60,000 | 3,10,000 2. Non-current liabilities : 8% Secured Debentures | 2,20,000 | — 3. Current Liabilities : Trade Payables | 1,08,000 | 2,80,000 Total | 6,68,000 | 10,90,000 II. Assets : 1. Non-current Assets : Property, Plant and Equipment | 2,50,000 | 5,90,000 2. Current Assets :
Inventories | 2,70,000 | 1,00,000
Trade Receivables | 88,000 | 2,84,000
Cash at Bank | 60,000 | 1,16,000 Total | 6,68,000 | 10,90,000
The Assets and Liabilities of the existing companies are to be transferred at book value with the exception of some items detailed below : (1) The debentures of X Ltd. are to be discharged by issue of 8% debentures of XY Ltd. at a premium of 10% (2) Property, Plant and Equipment of Y Ltd. was valued at ₹ 6,10,000 (3) The Trade Receivables of X Ltd. are realised fully and bank balance of X Ltd. are to be retained by the liquidator and the Trade Payables are to be paid of the proceeds thereof (4) Goodwill of X Ltd. was worth ₹ 1,00,000 and Y Ltd. was worth ₹ 3,00,000
You are required to— compute the basis on which shares in XY Ltd. will be issued at par to the shareholders of the existing companies;
draw up a Balance Sheet of XY Ltd. as at 1st April, 2021, the date of completion of amalgamation;
pass necessary Journal Entries including bank entries for closing the books of the books of X Ltd. 20 marks
Explain the principles and steps in setting up a good costing system in a manufacturing organisation. 15 marks
Define short-term capital assets and long-term capital assets.
How to compute tax on short- and long-term capital gains? 15 marks
हिंदी में प्रश्न पढ़ें
X लिमिटेड और Y लिमिटेड दूरसंचार (टेलीकॉम) के व्यवसाय में थे। दोनों कंपनियों ने समामेलन करके नई कम्पनी XY लिमिटेड बनाने का निर्णय लिया जिसकी अधिकृत पूँजी ₹ 20,00,000 होगी, जो ₹ 10 प्रति शेयर के 200000 इक्विटी शेयरों में विभाजित होगी। 31.03.2021 को कम्पनियों के तुलन-पत्र इस प्रकार थे :
विवरण | X लिमिटेड (₹) | Y लिमिटेड (₹) I. इक्विटी एवं दायित्व : 1. शेयरधारक निधि :
शेयर पूँजी | 2,80,000 | 5,00,000
आरक्षितियाँ एवं अधिशेष (लाभ एवं हानि खाता) | 60,000 | 3,10,000 2. अप्रचलित दायित्व : 8% सुरक्षित कर्णप्रत्र | 2,20,000 | — 3. चालू दायित्व : व्यापारिक देय | 1,08,000 | 2,80,000 कुल | 6,68,000 | 10,90,000 II. परिसंपत्तियाँ : 1. अप्रचलित परिसंपत्तियाँ : परिसंपत्ति, संयंत्र एवं उपकरण | 2,50,000 | 5,90,000 2. चालू परिसंपत्तियाँ :
मालसूची | 2,70,000 | 1,00,000
व्यापारिक प्राय | 88,000 | 2,84,000
बैंक में नकद | 60,000 | 1,16,000 कुल | 6,68,000 | 10,90,000
विद्यमान कम्पनियों की परिसंपत्तियों एवं दायित्वों को, कुछ मदों को छोड़कर जिनका व्योरा नीचे है, पुस्तक मूल्य पर हस्तांतरित किया जाना है : (1) X लिमिटेड के कर्णप्रत्रों को, XY लिमिटेड के 8% कर्णप्रत्र 10% प्रीमियम पर जारी करके, निपटाना जाना है (2) Y लिमिटेड की परिसंपत्ति, संयंत्र एवं उपकरण का मूल्य ₹ 6,10,000 निर्धारित किया गया (3) X लिमिटेड के व्यापारिक प्रायों की पूर्ण रूप से वसूली हुई है एवं X लिमिटेड का बैंक शेयर परिसमापक द्वारा रखा जाना है जिस राशि से व्यापारिक देयों का भुगतान किया जाना है (4) X लिमिटेड की ख्याति ₹ 1,00,000 एवं Y लिमिटेड की ख्याति ₹ 3,00,000 थी
दिए गए प्रश्नों का उत्तर दीजिए : उस आधार की गणना कीजिए, जिस पर XY लिमिटेड के शेयरों को विद्यमान कम्पनियों के शेयरधारकों को सममूल्य पर जारी किए जाएँगे।
1 अप्रैल, 2021 को, जिस तिथि पर समामेलन पूर्ण हुआ, XY लिमिटेड का तुलन-पत्र तैयार कीजिए।
X लिमिटेड की पुस्तकों को बंद करने हेतु बैंक प्रविष्टियाँ सहित आवश्यक जर्नल प्रविष्टियाँ कीजिए। (20 अंक)
विनिर्माण संगठन में अच्छी लागत प्रणाली स्थापित करने के सिद्धांतों एवं चरणों को समझाइए। (15 अंक)
अल्पकालीन पूँजीगत परिसंपत्तियों और दीर्घकालीन पूँजीगत परिसंपत्तियों को परिभाषित कीजिए।
अल्पकालीन और दीर्घकालीन पूँजीगत लाभों पर कर की गणना कैसे होती है? (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Table: Balance Sheets of X Limited and Y Limited as on 31.03.2021
Header Row: Details | X Limited (₹) | Y Limited (₹)
Section: I. Equity and Liabilities: Sub-section: 1. Shareholders' Funds: Row: (a) Share Capital | 2,80,000 | 5,00,000 Row: (b) Reserves and Surplus (Profit and Loss Account) | 60,000 | 3,10,000 Sub-section: 2. Non-current Liabilities: Row: 8% Secured Debentures | 2,20,000 | —
Table: Balance Sheets of X Limited and Y Limited as on 31.03.2021
Header: Details | X Limited (₹) | Y Limited (₹)
I. Equity and Liabilities:
- Shareholders' Funds: (a) Share Capital | 2,80,000 | 5,00,000 (b) Reserves and Surplus (Profit and Loss Account) | 60,000 | 3,10,000
- Non-current Liabilities: 8% Secured Debentures | 2,20,000 | —
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Amalgamation of X Ltd. and Y Ltd. into XY Ltd.
The revaluation of assets and the recognition of goodwill show an amalgamation in the nature of purchase. X's receivables, bank balance and trade payables stay with its liquidator. The 10% debenture premium is taken as part of the ₹2,20,000 discharge value.
(i) Purchase consideration and shares at par
- X: PPE 2,50,000 + inventories 2,70,000 + goodwill 1,00,000 = 6,20,000, less debentures 2,20,000 = ₹4,00,000, so 40,000 shares of ₹10.
- Debentures: XY issues 8% debentures of ₹2,00,000 face value at a 10% premium (₹2,20,000), discharging X's ₹2,20,000.
- Y: PPE 6,10,000 + inventories 1,00,000 + receivables 2,84,000 + bank 1,16,000 + goodwill 3,00,000 = 14,10,000, less payables 2,80,000 = ₹11,30,000, so 1,13,000 shares.
- Total 1,53,000 shares (₹15,30,000), within the authorised ₹20,00,000.
(ii) Balance Sheet of XY Ltd. at 1.4.2021
- Equity and liabilities: share capital ₹15,30,000; 8% debentures ₹2,00,000; securities premium ₹20,000; trade payables ₹2,80,000. Total ₹20,30,000.
- Assets: PPE ₹8,60,000; goodwill ₹4,00,000; inventories ₹3,70,000; trade receivables ₹2,84,000; cash at bank ₹1,16,000. Total ₹20,30,000.
(iii) Journal entries in the books of X Ltd. (₹)
- Realisation A/c Dr 6,08,000; to PPE 2,50,000, Inventories 2,70,000, Trade receivables 88,000.
- 8% Debentures A/c Dr 2,20,000 and Trade payables A/c Dr 1,08,000; to Realisation A/c 3,28,000.
- XY Ltd. A/c Dr 4,00,000; to Realisation A/c 4,00,000.
- Bank A/c Dr 88,000; to Realisation A/c 88,000 (receivables realised).
- Realisation A/c Dr 1,08,000; to Bank A/c 1,08,000 (payables paid).
- Shares in XY Ltd. A/c Dr 4,00,000; to XY Ltd. A/c 4,00,000.
- Realisation A/c Dr 1,00,000; to Equity shareholders' A/c 1,00,000 (profit); and Share capital Dr 2,80,000, Profit and loss Dr 60,000; to Equity shareholders' A/c 3,40,000.
- Equity shareholders' A/c Dr 4,40,000; to Shares in XY Ltd. 4,00,000 and Bank 40,000 (60,000 + 88,000 − 1,08,000).
(b) Principles and steps of a good costing system
A costing system records, classifies and assigns manufacturing cost to products so that it can be controlled and used for pricing and decisions. Its principles are:
- It must suit the nature of the business and be simple, flexible and economical.
- Cost must be classified consistently (material, labour, overheads; direct and indirect; fixed and variable).
- Responsibility must be fixed through cost centres, with cost data tied to the financial accounts.
- Records must be accurate, prompt and verifiable, with a reconciliation to the financial accounts.
- Management and workers should accept it, and it should report cost against standards.
The steps are:
- Study the products, process flow, organisation and information needs.
- Choose the method: job, batch, process or standard costing.
- Define cost centres and cost units, then design the documents and codes: material requisition, job card, time sheet.
- Select methods for pricing material issues and for absorbing overheads.
- Set standards and the variance and cost reports.
- Integrate with stores and the financial accounts, train staff, run a pilot, then review.
(c) Short-term and long-term capital assets, and tax on gains
(i) Definition. A capital asset is short-term if held for not more than the specified period and long-term if held for longer. The period is 12 months for listed securities and units of equity-oriented funds, and 24 months for other assets such as land, buildings and unlisted shares. Gains on unlisted bonds, debentures and specified debt funds are always short-term.
(ii) Tax computation.
- Short-term gain = sale consideration − (cost of acquisition + improvement + transfer expenses). Listed equity sold through a recognised exchange with STT is taxed at 20% (Section 111A of the 1961 Act); other short-term gains are added to income and taxed at slab rates.
- Long-term gain = sale consideration − the same deductions, without indexation after 23 July 2024. Listed equity gains above ₹1,25,000 are taxed at 12.5% (Section 112A) and other long-term gains at 12.5% (Section 112). Resident individuals and HUFs may use 20% with indexation on land or buildings acquired before 23 July 2024.
- Surcharge (capped at 15% on these gains) and cess apply, and exemptions such as Sections 54, 54F and 54EC reduce the tax.
For the year of the paper (AY 2021–22) the rates were 15% (short-term, STT paid), 10% above ₹1 lakh (listed equity) and 20% with indexation (others). These provisions are now carried into the Income-tax Act, 2025.
How this answer will be evaluated
Framework: CBSE/UPSC Commerce Accountancy Paper 1
What earns full marks: Complete workings, correct formats, precise statutory references, and clear logical flow.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute share basis, draw XY Ltd. Balance Sheet, and pass X Ltd. closing journal entries. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Purchase consideration: X ₹4,00,000 (40,000 shares) and Y ₹11,30,000 (1,13,000 shares) with working notes
- Balance Sheet of XY Ltd. as at 1.4.2021
- Journal entries for X Ltd. liquidation
- Debentures: ₹2,00,000 face value plus ₹20,000 premium discharges the ₹2,20,000 liability
Loses marks
- Final figures without working notes
- Incorrect share exchange ratio calculation
- Omission of debenture premium entry
Earns more
- Correct valuation of Y Ltd. PPE
- Proper treatment of X Ltd. trade receivables
- Cash of ₹40,000 left with the liquidator after paying creditors (60,000 + 88,000 − 1,08,000)
Extra mark
- Explicit mention of Goodwill valuation
- (b) Explain principles and steps for setting up a costing system in manufacturing. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Definition of costing system
- Key principles (e.g., cost control, accuracy)
- Step-by-step implementation process
- Relevance to manufacturing context
Loses marks
- Generic theory without manufacturing focus
- Missing implementation steps
- No mention of principles
Earns more
- Mention of specific costing methods (Job/Process)
- Example of cost center identification
- Linkage to management decision making
Extra mark
- Reference to the ICMAI Cost Accounting Standards
- (c) Define short/long-term capital assets and compute tax on gains. 15 marks
define— precise definition → the distinguishing feature → one example
Must cover
- Definition of short-term capital assets
- Definition of long-term capital assets
- Computation method for STCG tax
- Computation method for LTCG tax
Loses marks
- Confusing holding period definitions
- Omitting tax rate computation
- Ignoring indexation where the answer is framed under the law as it stood in 2021
Earns more
- Mention of holding period criteria
- Reference to indexation: available in 2021, and now only as the option for land or buildings acquired before 23 July 2024
- Distinction between listed/unlisted assets
Extra mark
- Citation of specific Income Tax Act sections
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2021 Paper I
- Q1 Answer the following questions in about 150 words each: (a) Briefly explain the significa…
- Q2 (a) X Ltd. and Y Ltd. were in telecom business. Both the companies took a decision to ama…
- Q3 (a) Mr. B (49 years), a resident individual, furnishes the following particulars pertaini…
- Q4 (a) ABC company produces tables. An analysis of their accounting reveals— Fixed cost ₹1,0…
- Q5 Answer the following questions in about 150 words each: (a) What is risk-return trade-off…