Paper I — Q8
(a) X Limited has its present annual sales amounting to ₹ 60 lakhs at ₹ 24 per unit. Variable costs are ₹ 16 per unit and fixed…
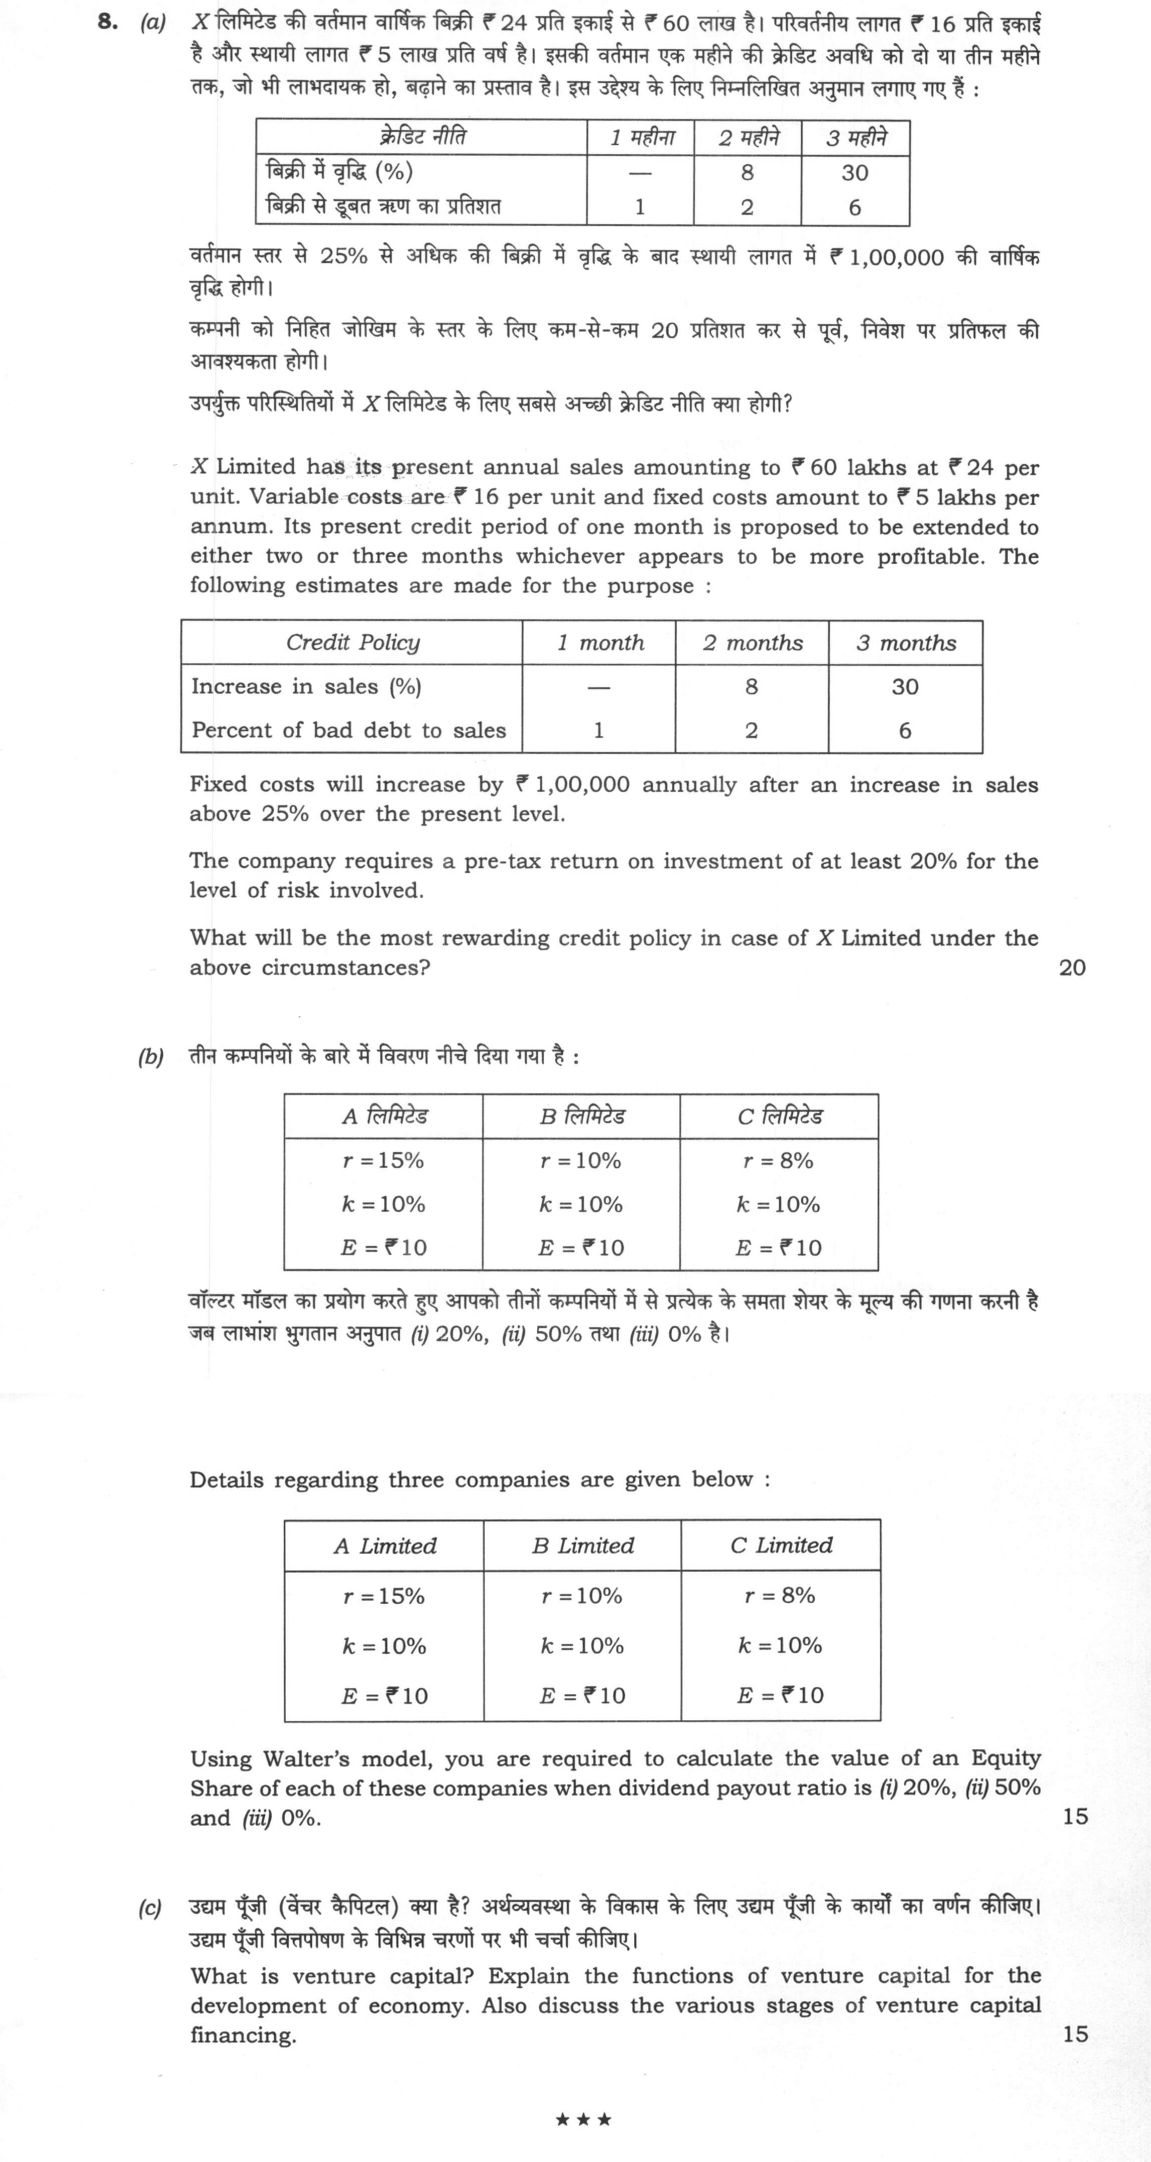
X Limited has its present annual sales amounting to ₹ 60 lakhs at ₹ 24 per unit. Variable costs are ₹ 16 per unit and fixed costs amount to ₹ 5 lakhs per annum. Its present credit period of one month is proposed to be extended to either two or three months whichever appears to be more profitable. The following estimates are made for the purpose :
Fixed costs will increase by ₹ 1,00,000 annually after an increase in sales above 25% over the present level.
The company requires a pre-tax return on investment of at least 20% for the level of risk involved.
What will be the most rewarding credit policy in case of X Limited under the above circumstances? 20 marks
Details regarding three companies are given below :
| A Limited | B Limited | C Limited |
|---|---|---|
| r = 15% | r = 10% | r = 8% |
| k = 10% | k = 10% | k = 10% |
| E = ₹10 | E = ₹10 | E = ₹10 |
Using Walter's model, you are required to calculate the value of an Equity Share of each of these companies when dividend payout ratio is (i) 20%, (ii) 50% and (iii) 0%. 15 marks
What is venture capital? Explain the functions of venture capital for the development of economy. Also discuss the various stages of venture capital financing. 15 marks
हिंदी में प्रश्न पढ़ें
X लिमिटेड की वर्तमान वार्षिक बिक्री ₹ 24 प्रति इकाई से ₹ 60 लाख है। परिवर्तनीय लागत ₹ 16 प्रति इकाई है और स्थायी लागत ₹ 5 लाख प्रति वर्ष है। इसकी वर्तमान एक महीने की क्रेडिट अवधि को दो या तीन महीने तक, जो भी लाभदायक हो, बढ़ाने का प्रस्ताव है। इस उद्देश्य के लिए निम्नलिखित अनुमान लगाए गए हैं :
वर्तमान स्तर से 25% से अधिक की बिक्री में वृद्धि के बाद स्थायी लागत में ₹ 1,00,000 की वार्षिक वृद्धि होगी।
कंपनी को निहित जोखिम के स्तर के लिए कम-से-कम 20 प्रतिशत कर से पूर्व, निवेश पर प्रतिफल की आवश्यकता होगी।
उपर्युक्त परिस्थितियों में X लिमिटेड के लिए सबसे अच्छी क्रेडिट नीति क्या होगी? 20 अंक
तीन कंपनियों के बारे में विवरण नीचे दिया गया है :
वॉल्टर मॉडल का प्रयोग करते हुए आपको तीनों कंपनियों में से प्रत्येक के समता शेयर के मूल्य की गणना करनी है जब लाभांश भुगतान अनुपात (i) 20%, (ii) 50% तथा (iii) 0% है। 15 अंक
उद्यम पूँजी (वेंचर कैपिटल) क्या है? अर्थव्यवस्था के विकास के लिए उद्यम पूँजी के कार्यों का वर्णन कीजिए। उद्यम पूँजी वित्तपोषण के विभिन्न चरणों पर भी चर्चा कीजिए। 15 अंक
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Table with header row: Credit Policy, 1 month, 2 months, 3 months. Row 1: Increase in sales (%), -, 8, 30. Row 2: Percent of bad debt to sales, 1, 2, 6.
(b) Table with three columns labeled A Limited, B Limited, and C Limited. The rows contain the following values: Row 1: r = 15%, r = 10%, r = 8% Row 2: k = 10%, k = 10%, k = 10% Row 3: E = ₹ 10, E = ₹ 10, E = ₹ 10
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Best credit policy for X Limited
Present units = 60,00,000 ÷ 24 = 2,50,000. Contribution per unit = 24 − 16 = ₹8. All figures are in ₹ lakh. Investment in receivables is taken at total cost (variable plus fixed) for the credit period, since that is the money actually tied up; the required return is 20% of it.
1 month (present policy). Sales 60.00; units 2,50,000; contribution 20.00; fixed cost 5.00; bad debts 1% × 60.00 = 0.60. Profit before required return = 20.00 − 5.00 − 0.60 = 14.40. Total cost = variable 40.00 + fixed 5.00 = 45.00; receivables = 45.00 × 1/12 = 3.75; required return 20% = 0.75. Net reward = 14.40 − 0.75 = 13.65.
2 months. Sales = 60.00 × 1.08 = 64.80; units 2,70,000; contribution 21.60. The rise of 8% does not exceed 25%, so fixed cost stays 5.00. Bad debts 2% × 64.80 = 1.296. Profit before required return = 21.60 − 5.00 − 1.296 = 15.304. Total cost = variable 43.20 + fixed 5.00 = 48.20; receivables = 48.20 × 2/12 = 8.033; required return = 1.607. Net reward = 15.304 − 1.607 = 13.697.
3 months. Sales = 60.00 × 1.30 = 78.00; units 3,25,000; contribution 26.00. The rise of 30% exceeds 25%, so fixed cost = 5.00 + 1.00 = 6.00. Bad debts 6% × 78.00 = 4.68. Profit before required return = 26.00 − 6.00 − 4.68 = 15.32. Total cost = variable 52.00 + fixed 6.00 = 58.00; receivables = 58.00 × 3/12 = 14.50; required return = 2.90. Net reward = 15.32 − 2.90 = 12.42.
Net rewards are 13.65, 13.70 and 12.42 lakh, so the most rewarding policy is two months' credit, though its advantage over the present policy is small (about ₹4,700 a year). Three months' credit should be rejected because the extra bad debts and fixed cost outweigh the added contribution. Taking variable cost only for receivables gives the same ranking. If receivables were taken at sales value, the present policy would come first, but funds are locked in at cost, so cost is the sounder base.
(b) Value of an equity share under Walter's model
Walter's model: P = [D + (r/k)(E − D)] / k, where D is dividend per share, E earnings per share, r the return on retained earnings and k the cost of capital. It assumes all financing is from retained earnings, r and k are constant and the firm has an infinite life. Here E = ₹10 and k = 10%.
Payout 20%: D = ₹2. A (r/k = 1.5): P = [2 + 1.5 × 8] / 0.10 = 14 / 0.10 = ₹140. B (r/k = 1): P = [2 + 8] / 0.10 = ₹100. C (r/k = 0.8): P = [2 + 0.8 × 8] / 0.10 = 8.4 / 0.10 = ₹84.
Payout 50%: D = ₹5. A: P = [5 + 1.5 × 5] / 0.10 = 12.5 / 0.10 = ₹125. B: P = [5 + 5] / 0.10 = ₹100. C: P = [5 + 0.8 × 5] / 0.10 = 9 / 0.10 = ₹90.
Payout 0%: D = 0. A: P = [0 + 1.5 × 10] / 0.10 = ₹150. B: P = 10 / 0.10 = ₹100. C: P = [0 + 0.8 × 10] / 0.10 = ₹80.
Interpretation: A is a growth firm (r > k), so value falls as payout rises and is highest at zero payout. B has r = k, so value stays at ₹100 at any payout. C has r < k, so value rises with payout and would be ₹100 at full payout.
(c) Venture capital
Venture capital is long-term risk capital, mostly equity or equity-linked, provided to new and fast-growing enterprises with high potential and high risk, usually along with management guidance, in return for a share of ownership and an exit through a public issue or sale. In India, venture capital funds are registered as Category I Alternative Investment Funds under the SEBI (Alternative Investment Funds) Regulations, 2012.
Functions in economic development: it mobilises savings into innovative ventures that banks would not finance; it creates new firms, jobs and entrepreneurs; it brings in technology, professional management and market links; it supports sectors such as software, biotechnology and clean energy, and so exports and competitiveness; and it builds an exit-led ecosystem of incubators, angels and professional advisers.
Stages of financing:
- Seed stage: small funds for an idea, research and a prototype; the risk is highest.
- Start-up or early stage: funds for product development, initial operations and first customers.
- Expansion or growth stage: funds to scale up production, marketing and capacity as revenues appear.
- Bridge or pre-IPO stage: short-term finance to prepare for a public issue or acquisition.
- Later or mezzanine stage: funds for large projects or restructuring, close to the exit, often convertible debt.
How this answer will be evaluated
Framework: Walter's Model
What earns full marks: Complete workings for all calculations, correct application of Walter's Model, and a well-structured theoretical answer with clear definitions and stages.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Determine the most rewarding credit policy for X Limited. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Contribution ₹8 per unit: 20.00, 21.60 and 26.00 lakh for 1, 2 and 3 months
- Bad debts 0.60, 1.296 and 4.68 lakh; fixed cost 6.00 lakh for 3 months as sales rise above 25%
- Investment in receivables at cost and 20% required return
- Net reward 13.65, 13.697 and 12.42 lakh; choose 2 months
Loses marks
- Missing the extra fixed cost for the 3-month plan or ignoring the required return.
Earns more
- Marks for contribution, costs, bad debts, cost of receivables and the decision.
Extra mark
- Stating the assumption on the basis of receivables and noting the narrow margin.
- (b) Calculate the value of an equity share of the three companies under Walter's model. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Formula P = [D + (r/k)(E − D)] / k with D as payout ratio × E
- 20% payout: A 140, B 100, C 84
- 50% payout: A 125, B 100, C 90; 0% payout: A 150, B 100, C 80
- Interpretation: growth, normal and declining firm
Loses marks
- Using the wrong formula or treating D as 20% of price.
Earns more
- Marks for the formula, each computed value and the interpretation.
Extra mark
- Stating the model assumptions and the optimal payout for each firm.
- (c) Explain venture capital, its functions in economic development and its stages of financing. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Long-term risk capital for new high-growth firms, with management support
- Functions: mobilises savings, creates enterprises, brings technology and management
- Stages: seed, start-up, expansion, bridge and later stage
- Regulated as Category I AIF under SEBI AIF Regulations, 2012
Loses marks
- Listing stages without explaining what each finances.
Earns more
- Marks for the meaning, functions and each stage.
Extra mark
- An example of the risk and return or the exit routes.
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…
- Q6 (a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company i…
- Q7 (a) The following Balance Sheet is given as on 31st March, 2022 : Particulars Amount ₹ I.…
- Q8 (a) X Limited has its present annual sales amounting to ₹ 60 lakhs at ₹ 24 per unit. Vari…