Paper I — Q6
(a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company is evaluating a project to install a…
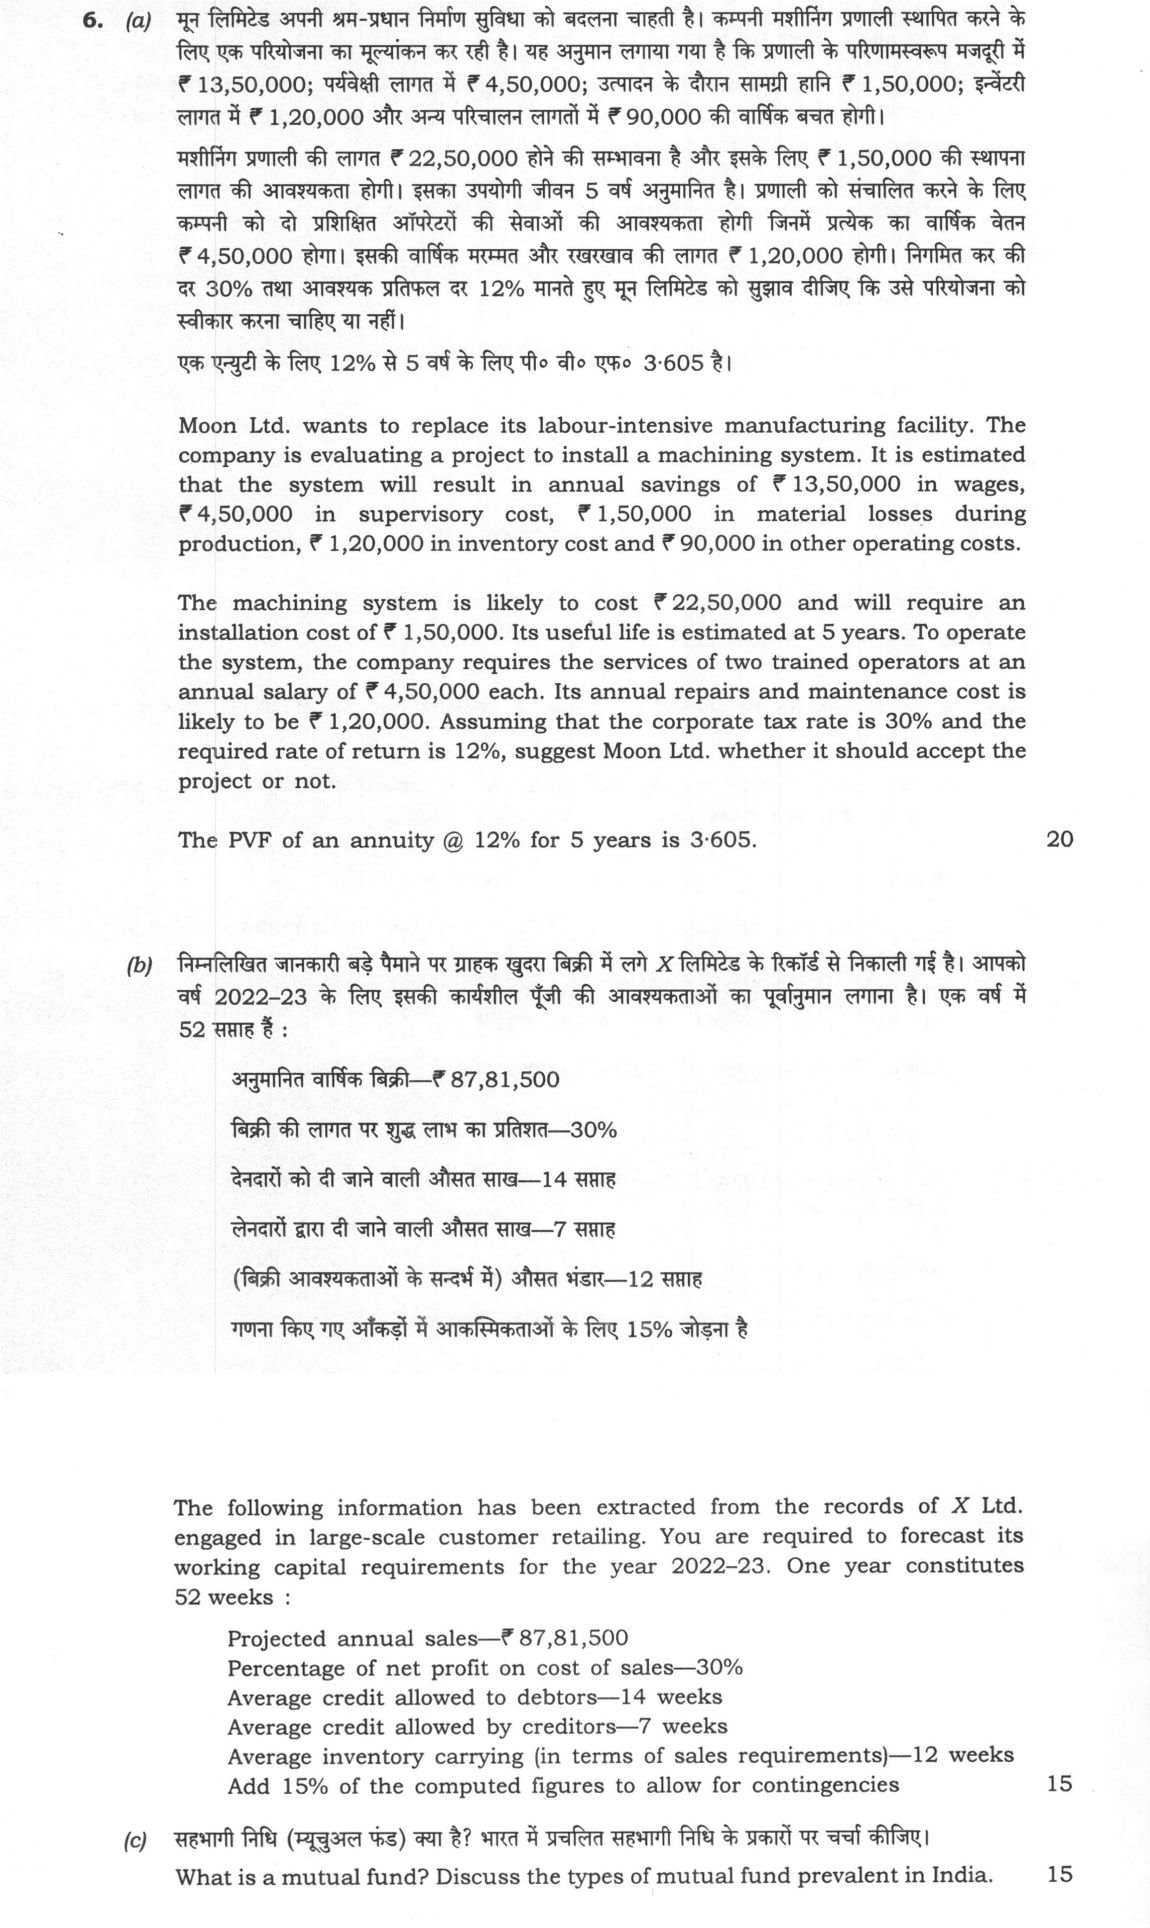
Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company is evaluating a project to install a machining system. It is estimated that the system will result in annual savings of ₹ 13,50,000 in wages, ₹ 4,50,000 in supervisory cost, ₹ 1,50,000 in material losses during production, ₹ 1,20,000 in inventory cost and ₹ 90,000 in other operating costs.
The machining system is likely to cost ₹ 22,50,000 and will require an installation cost of ₹ 1,50,000. Its useful life is estimated at 5 years. To operate the system, the company requires the services of two trained operators at an annual salary of ₹ 4,50,000 each. Its annual repairs and maintenance cost is likely to be ₹ 1,20,000. Assuming that the corporate tax rate is 30% and the required rate of return is 12%, suggest Moon Ltd. whether it should accept the project or not.
The PVF of an annuity @ 12% for 5 years is 3·605. 20 marks
The following information has been extracted from the records of X Ltd. engaged in large-scale customer retailing. You are required to forecast its working capital requirements for the year 2022-23. One year constitutes 52 weeks:
Projected annual sales—₹ 87,81,500 Percentage of net profit on cost of sales—30% Average credit allowed to debtors—14 weeks Average credit allowed by creditors—7 weeks Average inventory carrying (in terms of sales requirements)—12 weeks Add 15% of the computed figures to allow for contingencies 15 marks
What is a mutual fund? Discuss the types of mutual fund prevalent in India. 15 marks
हिंदी में प्रश्न पढ़ें
मून लिमिटेड अपनी श्रम-प्रधान निर्माण सुविधा को बदलना चाहती है। कम्पनी मशीनींग प्रणाली स्थापित करने के लिए एक परियोजना का मूल्यांकन कर रही है। यह अनुमान लगाया गया है कि प्रणाली के परिणामस्वरूप मजदूरी में ₹ 13,50,000; पर्यवेक्षी लागत में ₹ 4,50,000; उत्पादन के दौरान सामग्री हानि ₹ 1,50,000; इन्वेंट्री लागत में ₹ 1,20,000 और अन्य परिचालन लागतों में ₹ 90,000 की वार्षिक बचत होगी।
मशीनींग प्रणाली की लागत ₹ 22,50,000 होने की सम्भावना है और इसके लिए ₹ 1,50,000 की स्थापना लागत की आवश्यकता होगी। इसका उपयोगी जीवन 5 वर्ष अनुमानित है। प्रणाली को संचालित करने के लिए कम्पनी को दो प्रशिक्षित ऑपरेटरों की सेवाओं की आवश्यकता होगी जिनमें प्रत्येक का वार्षिक वेतन ₹ 4,50,000 होगा। इसकी वार्षिक मरम्मत और रखरखाव की लागत ₹ 1,20,000 होगी। निगमित कर की दर 30% तथा आवश्यक प्रतिफल दर 12% मानते हुए मून लिमिटेड को सुझाव दीजिए कि उसे परियोजना को स्वीकार करना चाहिए या नहीं।
एक एन्युटी के लिए 12% से 5 वर्ष के लिए पी० वी० एफ० 3·605 है। (20 अंक)
निम्नलिखित जानकारी बड़े पैमाने पर ग्राहक खुदरा विक्री में लगे X लिमिटेड के रिकॉर्ड से निकाली गई है। आपको वर्ष 2022-23 के लिए इसकी कार्यशील पूँजी की आवश्यकताओं का पूर्वानुमान लगाना है। एक वर्ष में 52 सप्ताह हैं :
अनुमानित वार्षिक विक्री—₹ 87,81,500 विक्री की लागत पर शुद्ध लाभ का प्रतिशत—30% देनदारों को दी जाने वाली औसत साख—14 सप्ताह लेनदारों द्वारा दी जाने वाली औसत साख—7 सप्ताह (विक्री आवश्यकताओं के संदर्भ में) औसत भण्डार—12 सप्ताह गणना किए गए आँकड़ों में आकस्मिकताओं के लिए 15% जोड़ना है (15 अंक)
सहभागी निधि (म्युचुअल फंड) क्या है? भारत में प्रचलित सहभागी निधि के प्रकारों पर चर्चा कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Machining system: accept or reject
Annual savings = 13,50,000 + 4,50,000 + 1,50,000 + 1,20,000 + 90,000 = ₹21,60,000.
Additional annual costs = two operators 2 × 4,50,000 = 9,00,000, plus repairs and maintenance 1,20,000 = ₹10,20,000.
Net pre-tax saving = 21,60,000 − 10,20,000 = ₹11,40,000.
Initial outlay = machine 22,50,000 + installation 1,50,000 = ₹24,00,000. Installation is capitalised, as it brings the asset to working condition. Assuming nil salvage value, straight-line depreciation = 24,00,000 / 5 = ₹4,80,000 a year.
Profit before tax = 11,40,000 − 4,80,000 = 6,60,000. Tax at 30% = 1,98,000. Profit after tax = 4,62,000. Annual cash inflow after tax = 4,62,000 + 4,80,000 (depreciation added back) = ₹9,42,000.
Present value of inflows = 9,42,000 × 3.605 = ₹33,95,910.
NPV = 33,95,910 − 24,00,000 = ₹9,95,910. As the NPV is positive, the project earns more than the 12% required return, and Moon Ltd. should accept it. The decision is based on the stated estimates; it would change only if savings fell sharply, so the firm should check the wage and material-loss savings before committing.
(b) Working capital forecast for 2022-23
The profit is 30% on cost of sales, so sales = 130% of cost. Cost of sales = 87,81,500 × 100/130 = ₹67,55,000.
Weekly sales = 87,81,500 / 52 = ₹1,68,875. Weekly cost of sales = 67,55,000 / 52 = ₹1,29,904 (taking purchases as equal to cost of sales, with no change in stock).
Current assets: inventory (12 weeks, valued at cost) = 12 × 1,29,904 = ₹15,58,846. Debtors (14 weeks, valued at sales) = 14 × 1,68,875 = ₹23,64,250. Total current assets = ₹39,23,096.
Current liabilities: creditors (7 weeks at cost) = 7 × 1,29,904 = ₹9,09,327.
Net working capital = 39,23,096 − 9,09,327 = ₹30,13,769.
Contingency at 15% = ₹4,52,065.
Working capital required = ₹34,65,835 (worked on unrounded figures).
(c) Mutual fund and its types in India
A mutual fund is a trust-based, SEBI-regulated pool of money from many investors. The asset management company invests it in securities such as shares, bonds and money-market instruments through a fund manager; investors hold units and share the gains, losses and expenses in proportion. Funds are regulated by SEBI (now under the SEBI (Mutual Funds) Regulations, 2026, which replaced the 1996 Regulations) and their units are valued at net asset value (NAV). The main benefits are professional management, diversification, liquidity and small minimum investments.
By structure: open-ended funds sell and redeem units continuously at NAV; close-ended funds have a fixed maturity and units are traded on an exchange; interval funds open for purchase and redemption only at set intervals.
By objective, SEBI's categorisation groups schemes as equity funds (large-cap, mid-cap, small-cap, ELSS and others), debt funds (liquid, corporate bond, gilt and others), hybrid funds that mix both, solution-oriented funds for goals such as retirement or children's education, and other funds such as index funds and ETFs.
By investment style, funds may also be actively managed or passively track an index. Each type suits a different risk appetite and time horizon, so the choice depends on the investor's goals.
How this answer will be evaluated
Framework: CBSE/UPSC Commerce Accountancy Paper 1
What earns full marks: Shows complete, accurate calculations with clear working notes; provides well-structured, comprehensive answers with relevant examples and regulatory references.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Advise Moon Ltd. whether to accept the machining project, using NPV. 20 marks
suggest— the problem in one line → implementable measures → who acts → conclusion
Must cover
- Net pre-tax saving 21,60,000 − 10,20,000 = 11,40,000
- Outlay 24,00,000 including installation; depreciation 4,80,000
- After-tax cash flow 9,42,000 (PAT 4,62,000 plus depreciation)
- PV 33,95,910 and NPV 9,95,910, so accept
Loses marks
- Ignoring the depreciation tax shield or leaving out operator salaries.
Earns more
- Marks for savings and cost, cash flow after tax, NPV and the decision.
Extra mark
- Noting the nil salvage assumption and a caution on the estimates.
- (b) Forecast the working capital requirement of X Ltd. for 2022-23. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Cost of sales 67,55,000 from sales 87,81,500 at 130%
- Inventory 15,58,846 at cost and debtors 23,64,250 at sales
- Creditors 9,09,327; net working capital 30,13,769
- 15% contingency 4,52,065; total 34,65,835
Loses marks
- Valuing inventory or creditors at sales value, or adding profit to cost wrongly.
Earns more
- Marks for cost of sales, each current asset and liability, contingency and the total.
Extra mark
- Stating the valuation assumptions for inventory, debtors and creditors.
- (c) Define a mutual fund and discuss the types of mutual funds in India. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Pooled investment vehicle regulated by SEBI, issuing units at NAV
- Structure: open-ended, close-ended and interval funds
- Objective-wise SEBI categories: equity, debt, hybrid, solution-oriented and other
- Benefits such as diversification, professional management and liquidity
Loses marks
- Listing schemes without the structural classification.
Earns more
- Marks for the definition and for each classification with examples.
Extra mark
- Mentioning SEBI (Mutual Funds) Regulations, 2026 and active versus passive funds.
What "Suggest" is asking you to do
Propose measures that attach to the causes the question has just had you identify. Each should name who acts, on what, and why it would work; a measure with no actor behind it is a wish rather than a suggestion.
Structure that answers it
The problem in one line → measure 1 with the cause it addresses → measure 2 → measure 3 → how it would be implemented and what it requires
Where marks are lost
Prescriptions that would fit any question on any subject — awareness campaigns, capacity building, better coordination. The examiner checks whether each measure is traceable to a cause the answer itself named.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q3 (a) From the following information, prepare Process A/cs and calculate the actual profits…
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…
- Q6 (a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company i…
- Q7 (a) The following Balance Sheet is given as on 31st March, 2022 : Particulars Amount ₹ I.…
- Q8 (a) X Limited has its present annual sales amounting to ₹ 60 lakhs at ₹ 24 per unit. Vari…