Paper I — Q4
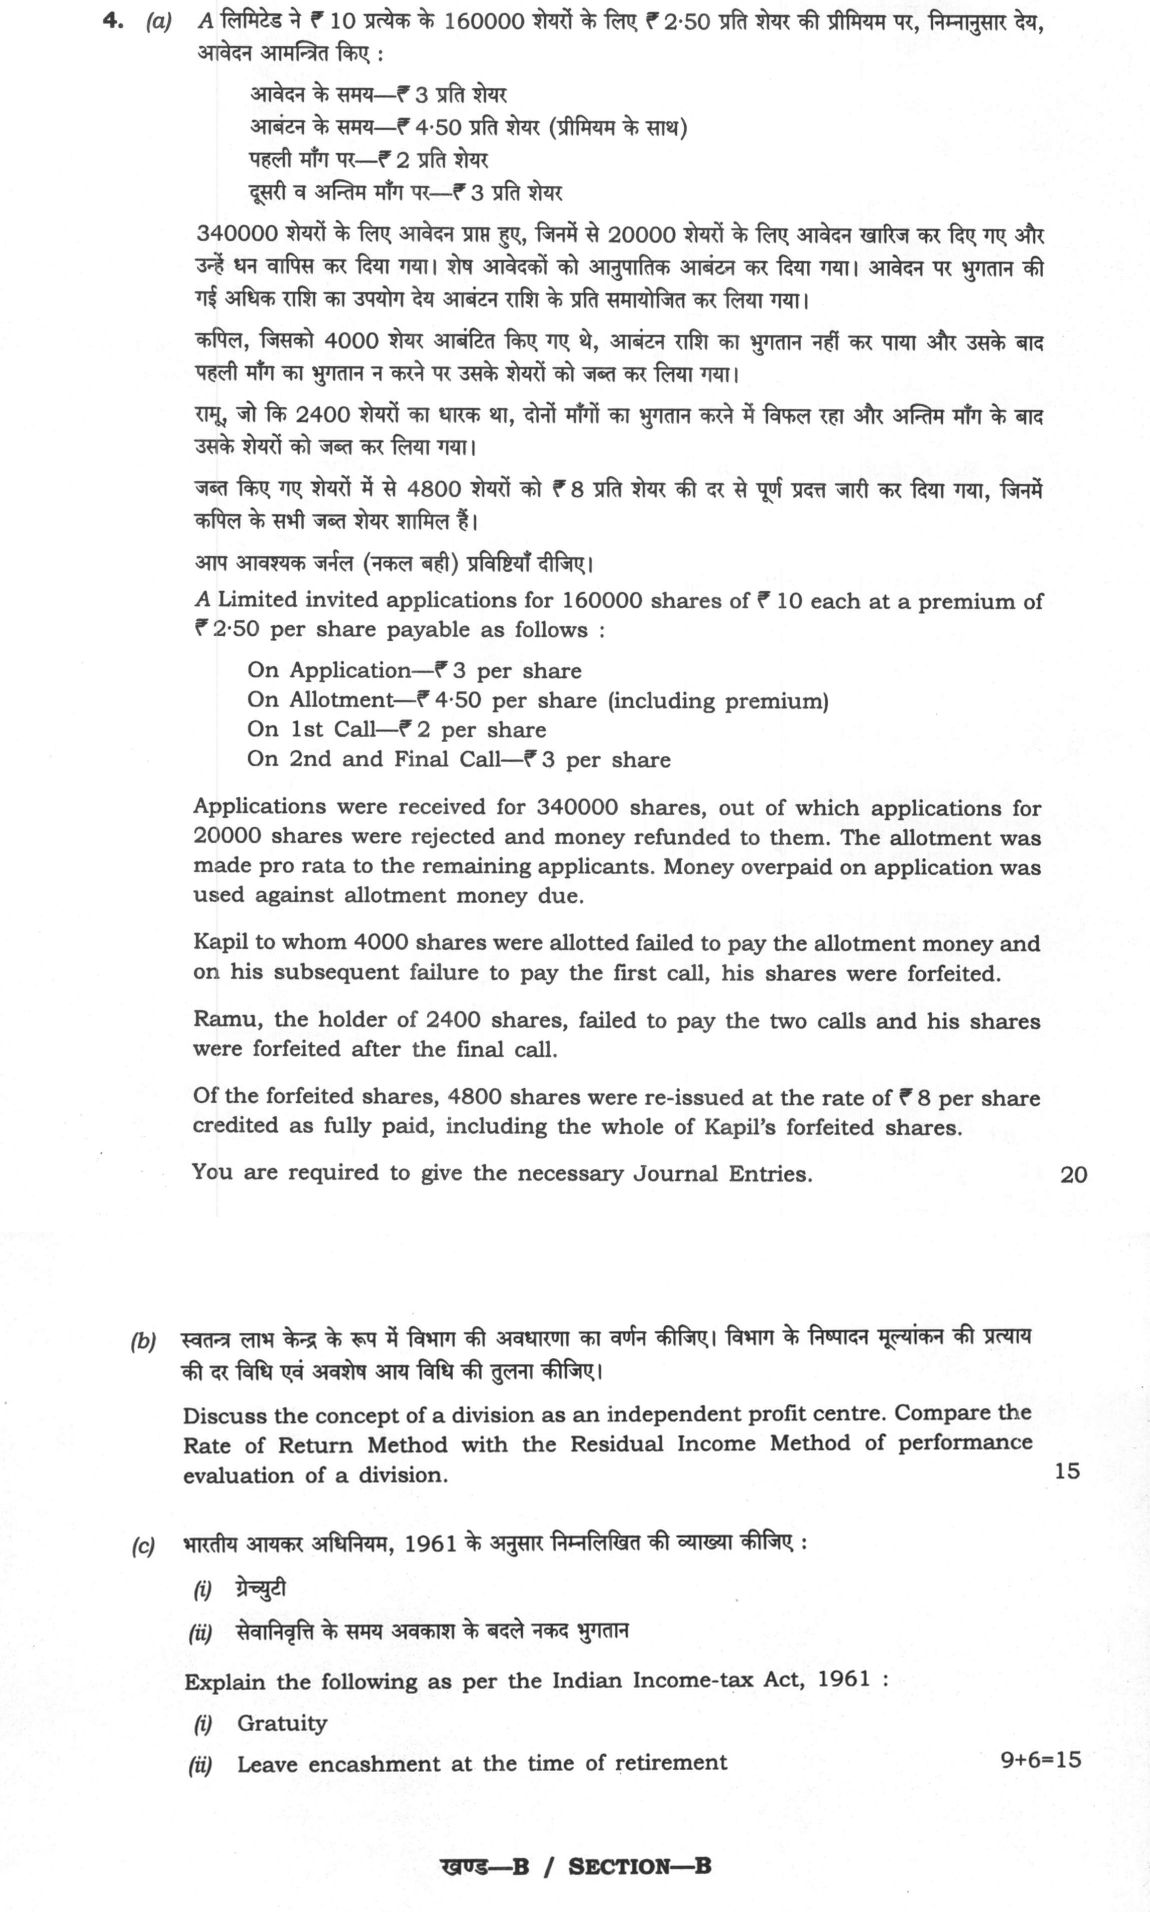
(a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50 per share payable as follows : On…
A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50 per share payable as follows :
On Application—₹ 3 per share On Allotment—₹ 4.50 per share (including premium) On 1st Call—₹ 2 per share On 2nd and Final Call—₹ 3 per share
Applications were received for 340000 shares, out of which applications for 20000 shares were rejected and money refunded to them. The allotment was made pro rata to the remaining applicants. Money overpaid on application was used against allotment money due.
Kapil to whom 4000 shares were allotted failed to pay the allotment money and on his subsequent failure to pay the first call, his shares were forfeited.
Ramu, the holder of 2400 shares, failed to pay the two calls and his shares were forfeited after the final call.
Of the forfeited shares, 4800 shares were re-issued at the rate of ₹ 8 per share credited as fully paid, including the whole of Kapil's forfeited shares.
You are required to give the necessary Journal Entries. 20 marks
Discuss the concept of a division as an independent profit centre. Compare the Rate of Return Method with the Residual Income Method of performance evaluation of a division. 15 marks
Explain the following as per the Indian Income-tax Act, 1961 : Gratuity
Leave encashment at the time of retirement (9+6=15 marks)
हिंदी में प्रश्न पढ़ें
A लिमिटेड ने ₹ 10 प्रत्येक के 160000 शेयरों के लिए ₹ 2.50 प्रति शेयर की प्रीमियम पर, निम्नानुसार देय, आवेदन आमंत्रित किए :
आवेदन के समय—₹ 3 प्रति शेयर आबंटन के समय—₹ 4.50 प्रति शेयर (प्रीमियम के साथ) पहली माँग पर—₹ 2 प्रति शेयर दूसरी व अंतिम माँग पर—₹ 3 प्रति शेयर
340000 शेयरों के लिए आवेदन प्राप्त हुए, जिनमें से 20000 शेयरों के लिए आवेदन खारिज कर दिए गए और उन्हें धन वापिस कर दिया गया। शेष आवेदकों को अनुपातिक आबंटन कर दिया गया। आवेदन पर भुगतान की गई अधिक राशि का उपयोग देय आबंटन राशि के प्रति समायोजित कर लिया गया।
कपिल, जिसको 4000 शेयर आबंटित किए गए थे, आबंटन राशि का भुगतान नहीं कर पाया और उसके बाद पहली माँग का भुगतान न करने पर उसके शेयरों को जब्त कर लिया गया।
रामू, जो कि 2400 शेयरों का धारक था, दोनों माँगों का भुगतान करने में विफल रहा और अंतिम माँग के बाद उसके शेयरों को जब्त कर लिया गया।
जब्त किए गए शेयरों में से 4800 शेयरों को ₹ 8 प्रति शेयर की दर से पूर्ण प्रदत जारी कर दिया गया, जिनमें कपिल के सभी जब्त शेयर शामिल हैं।
आप आवश्यक जर्नल (नकल बही) प्रविष्टियाँ दीजिए। (20 अंक)
स्वतंत्र लाभ केंद्र के रूप में विभाग की अवधारणा का वर्णन कीजिए। विभाग के निष्पादन मूल्यांकन की प्रत्याय की दर विधि एवं अवशेष आय विधि की तुलना कीजिए। (15 अंक)
भारतीय आयकर अधिनियम, 1961 के अनुसार निम्नलिखित की व्याख्या कीजिए : ग्रेच्युटी
सेवानिवृत्ति के समय अवकाश के बदले नकद भुगतान (9+6=15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Journal entries
Working. Applications for 3,40,000 shares at ₹3 = ₹10,20,000. Rejected 20,000 shares: refund ₹60,000. Applicants left: 3,20,000 for 1,60,000 shares, so allotment is 1 for every 2 applied. Application money on allotted shares = 1,60,000 × ₹3 = ₹4,80,000; the other ₹4,80,000 is adjusted against allotment. Allotment due = 1,60,000 × ₹4.50 = ₹7,20,000 (capital ₹2 = 3,20,000; premium ₹2.50 = 4,00,000).
Kapil applied for 8,000 shares and paid ₹24,000; ₹12,000 stays on application and ₹12,000 is adjusted against allotment of ₹18,000, leaving ₹6,000 unpaid. Ramu applied for 4,800 shares and paid ₹14,400; ₹7,200 stays and ₹7,200 is adjusted against allotment of ₹10,800, so he paid ₹3,600 in cash.
- Bank A/c Dr 10,20,000; To Share Application A/c 10,20,000 (application money received).
- Share Application A/c Dr 60,000; To Bank A/c 60,000 (refund to rejected applicants).
- Share Application A/c Dr 9,60,000; To Share Capital A/c 4,80,000; To Share Allotment A/c 4,80,000 (application money applied).
- Share Allotment A/c Dr 7,20,000; To Share Capital A/c 3,20,000; To Securities Premium A/c 4,00,000 (allotment due).
- Bank A/c Dr 2,34,000; Calls-in-Arrears A/c Dr 6,000; To Share Allotment A/c 2,40,000 (net allotment money received; Kapil's ₹6,000 unpaid).
- Share First Call A/c Dr 3,20,000; To Share Capital A/c 3,20,000 (1,60,000 × ₹2).
- Bank A/c Dr 3,07,200; Calls-in-Arrears A/c Dr 12,800; To Share First Call A/c 3,20,000 (Kapil ₹8,000 and Ramu ₹4,800 unpaid).
- Share Capital A/c Dr 28,000; Securities Premium A/c Dr 6,000; To Calls-in-Arrears A/c 14,000; To Share Forfeiture A/c 20,000 (Kapil's 4,000 shares forfeited; capital called ₹7 × 4,000; ₹6,000 of unpaid allotment was premium; he had paid ₹24,000, of which ₹4,000 was premium, so ₹20,000 is forfeited).
- Share Final Call A/c Dr 4,68,000; To Share Capital A/c 4,68,000 (1,56,000 shares × ₹3).
- Bank A/c Dr 4,60,800; Calls-in-Arrears A/c Dr 7,200; To Share Final Call A/c 4,68,000 (Ramu's ₹7,200 unpaid).
- Share Capital A/c Dr 24,000; To Calls-in-Arrears A/c 12,000; To Share Forfeiture A/c 12,000 (Ramu's 2,400 shares forfeited; he paid ₹18,000, of which ₹6,000 was premium).
- Bank A/c Dr 38,400; Share Forfeiture A/c Dr 9,600; To Share Capital A/c 48,000 (4,800 shares reissued at ₹8 as fully paid: Kapil's 4,000 and Ramu's 800).
- Share Forfeiture A/c Dr 14,400; To Capital Reserve A/c 14,400 (Kapil: 20,000 − 8,000 discount = 12,000; Ramu's 800 shares: 4,000 − 1,600 = 2,400).
The balance in Share Forfeiture A/c is ₹8,000 (20,000 + 12,000 − 9,600 − 14,400), relating to Ramu's 1,600 shares not yet reissued.
(b) Division as an independent profit centre: ROI and residual income
A division becomes an independent profit centre when it has the authority to decide on selling prices, output and costs, so that it earns revenue and incurs costs as if it were a separate business. Its manager is held accountable for divisional profit, which motivates initiative, speeds up local decisions and frees top management. It needs clear transfer pricing, uniform policies and guards against sub-optimisation.
Rate of return (ROI) measures divisional profit as a percentage of the investment in the division: ROI = (Divisional profit ÷ Divisional investment) × 100. It is relative, so divisions of different sizes can be compared. But a manager whose ROI is high may reject a project earning more than the cost of capital but less than the current ROI, and may cut investment to lift the ratio, which can harm growth.
Residual income (RI) is divisional profit less a capital charge at the required rate: RI = Profit − (Required rate × Investment). It is an absolute amount. Any project earning above the required rate raises RI, so the manager's aims line up with the company's. Its weaknesses are that it favours large divisions and depends on a fair cost of capital and asset valuation.
So ROI gives a size-neutral measure but can mislead on acceptance of projects, while RI gives better goal congruence but is not comparable between divisions of different scale.
(c) Gratuity and leave encashment under the Income-tax Act, 1961
(i) Gratuity. Gratuity received on retirement, death, resignation or termination is exempt under Section 10(10). Government and local authority employees: fully exempt. Employees covered by the Payment of Gratuity Act, 1972: the least of the gratuity received, ₹20 lakh, and 15 days' salary (last drawn, basic plus dearness allowance) for each completed year of service or part over six months (15/26 × last salary × years). Other employees: the least of the gratuity received, ₹20 lakh, and half a month's average salary of the last 10 months for each completed year. The balance is taxed as salary.
(ii) Leave encashment at retirement. Under Section 10(10AA), government employees are fully exempt. Non-government employees get the least of: the amount received; ₹25 lakh (raised from ₹3 lakh from 1.4.2023); 10 months' average salary of the 10 months before retirement; and the cash equivalent of unavailed leave up to 30 days per year of service. Salary here means basic, dearness allowance forming part of pay, and commission on a fixed turnover. Encashment while in service is fully taxable. The Income-tax Act, 2025 (from 1.4.2026) carries these exemptions forward.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Accurate calculations, clear working notes, precise statutory references, and comprehensive comparison.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Pass the journal entries for issue, pro-rata allotment, calls, forfeiture and reissue of shares. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Application 10,20,000; refund 60,000; 4,80,000 to capital and 4,80,000 adjusted to allotment
- Allotment due 7,20,000 with premium 4,00,000; calls-in-arrears 6,000, 12,800 and 7,200
- Forfeiture of Kapil's shares: capital 28,000, premium 6,000 debited, forfeiture credit 20,000; Ramu's credit 12,000
- Reissue of 4,800 shares at ₹8: bank 38,400, discount 9,600; capital reserve 14,400; balance forfeiture 8,000
Loses marks
- Forfeiting without considering unpaid premium or transferring the whole forfeiture to capital reserve.
Earns more
- Marks for each correct entry with its working.
Extra mark
- Showing Kapil's and Ramu's pro-rata working clearly.
- (b) Discuss a division as an independent profit centre and compare rate of return with residual income. 15 marks
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- Profit centre: authority over price, output and cost; manager accountable for profit
- ROI = profit ÷ investment × 100; relative measure, comparable across sizes
- RI = profit − required rate × investment; absolute and goal-congruent
- Weaknesses: ROI may reject worthwhile projects; RI favours large divisions
Loses marks
- Explaining the two methods separately without contrasting them.
Earns more
- Marks for the concept and a point-by-point comparison.
Extra mark
- Mentioning transfer pricing and sub-optimisation.
- (c) Explain the tax treatment of gratuity and leave encashment at retirement under the Income-tax Act, 1961. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Gratuity under Section 10(10): government employees fully exempt
- Covered employees: least of the amount, ₹20 lakh, 15 days' salary per year
- Leave encashment under Section 10(10AA): government employees fully exempt
- Non-government: least of the amount, ₹25 lakh, 10 months' salary, 30 days per year
Loses marks
- Quoting outdated limits such as ₹3 lakh for leave encashment.
Earns more
- Marks for each section and its limits.
Extra mark
- Noting the limit raised to ₹25 lakh from 1.4.2023 and the 2025 Act carrying it forward.
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q1 Answer the following questions in about 150 words each: (a) What is meant by buyback of s…
- Q2 (a) The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liab…
- Q3 (a) From the following information, prepare Process A/cs and calculate the actual profits…
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…
- Q6 (a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company i…
- Q7 (a) The following Balance Sheet is given as on 31st March, 2022 : Particulars Amount ₹ I.…