Paper I — Q1
(a) What is meant by buyback of shares by companies? Explain the reasons and sources of buyback of shares. (10 marks) (b) "Cost…
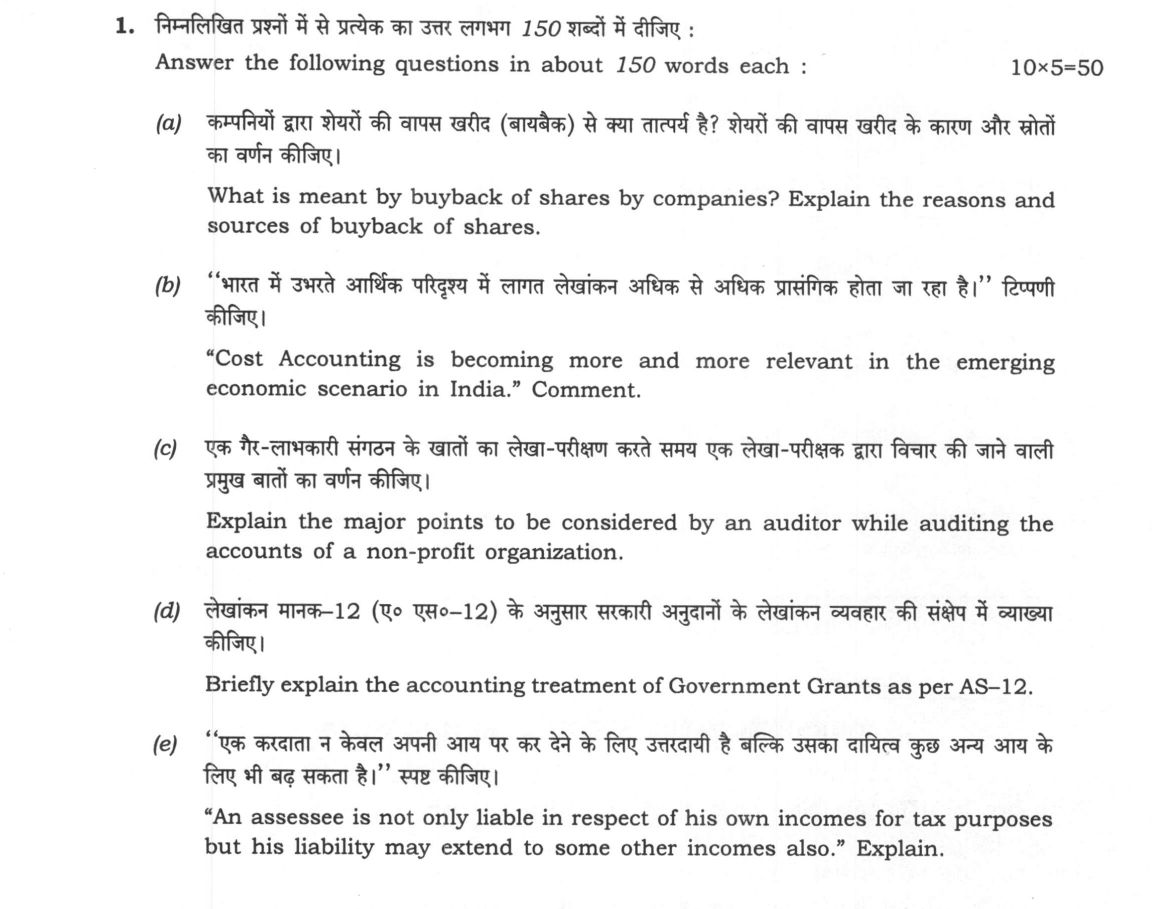
Answer the following questions in about 150 words each:
What is meant by buyback of shares by companies? Explain the reasons and sources of buyback of shares. 10 marks
"Cost Accounting is becoming more and more relevant in the emerging economic scenario in India." Comment. 10 marks
Explain the major points to be considered by an auditor while auditing the accounts of a non-profit organization. 10 marks
Briefly explain the accounting treatment of Government Grants as per AS-12. 10 marks
"An assessee is not only liable in respect of his own incomes for tax purposes but his liability may extend to some other incomes also." Explain. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए :
कम्पनियों द्वारा शेयरों की वापस खरीद (बायबैक) से क्या तात्पर्य है? शेयरों की वापस खरीद के कारण और स्रोतों का वर्णन कीजिए। (10 अंक)
"भारत में उभरते आर्थिक परिदृश्य में लागत लेखांकन अधिक से अधिक प्रासंगिक होता जा रहा है।" टिप्पणी कीजिए। (10 अंक)
एक गैर-लाभकारी संगठन के खातों का लेखा-परीक्षण करते समय एक लेखा-परीक्षक द्वारा विचार की जाने वाली प्रमुख बातों का वर्णन कीजिए। (10 अंक)
लेखांकन मानक-12 (ए० एस०-12) के अनुसार सरकारी अनुदानों के लेखांकन व्यवहार की संक्षेप में व्याख्या कीजिए। (10 अंक)
"एक करदाता न केवल अपनी आय पर कर देने के लिए उत्तरदायी है बल्कि उसका दायित्व कुछ अन्य आय के लिए भी बढ़ सकता है।" स्पष्ट कीजिए। (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Buyback of shares
Buyback is a company purchasing its own fully paid-up shares or other specified securities from its shareholders (Sections 68 to 70 of the Companies Act, 2013). The shares are extinguished, as treasury shares are not allowed, and their nominal value is transferred to the Capital Redemption Reserve.
Reasons: returning surplus cash, improving earnings per share and return on equity, supporting an undervalued share price, resisting a hostile takeover, and adjusting the capital structure.
Sources: free reserves, the securities premium account, or the proceeds of a fresh issue of shares or other specified securities (but not of the same kind as those bought back). The main limits: authorisation by the articles, a ceiling of 25% of paid-up capital and free reserves, and a post-buyback debt-equity ratio of at most 2 : 1. A board resolution suffices up to 10%; beyond that a special resolution is needed. Listed companies also follow the SEBI Buyback Regulations.
(b) Relevance of cost accounting in India
The statement is largely correct. Liberalisation and global competition have squeezed margins, so firms need product-wise costs for pricing, cost reduction and make-or-buy choices. Cost data is needed in regulated pricing such as drugs and power, under GST where input-tax benefits must be passed on to buyers, and in the fast-growing services and MSME sectors. Section 148 of the Companies Act makes cost records and cost audit compulsory for specified industries, and costing tools such as activity-based and target costing, and sustainability costing, guide efficiency.
However, relevance depends on quality. Costing that is a compliance exercise, or an inaccurate overhead allocation, misleads rather than helps. Its value is greatest where it feeds real decisions, so cost accounting is relevant, provided the system is accurate and management uses it.
(c) Audit of a non-profit organisation
The auditor checks that the entity has used its funds for its stated objects and has complied with the law. The main points are:
The governing documents (trust deed or rules) and the minutes, which set the powers to receive and spend funds. Receipts such as donations, subscriptions, entrance fees, legacies and grants are verified against receipt books and bank records, with restricted and endowment funds kept separate and the conditions of grants checked against utilisation certificates. Expenses are checked with vouchers and approvals, and capital and revenue items are separated. Fixed assets, investments and their permitted modes are verified. Compliance is examined for registration (12A/12AB, 80G), application of at least 85% of income, and FCRA for foreign contributions. Finally, the receipts and payments account, income and expenditure account and balance sheet are checked for true and fair presentation.
(d) Government grants under AS-12
A grant is recognised only when there is reasonable assurance that the entity will comply with its conditions and that the grant will be received.
Revenue grants are taken to the profit and loss statement over the periods in which the related costs are incurred, as other income or as a deduction from the expense. Grants for depreciable assets are either deducted from the asset's cost, so that depreciation is charged on the reduced cost, or shown as deferred income and credited to profit and loss in proportion to depreciation. A grant in the nature of a promoter's contribution goes to shareholders' funds as capital reserve and is not income. Non-monetary grants are recorded at fair value or a nominal value.
A refund is first set against any unamortised deferred credit, and the balance is charged to profit and loss; a refund of a capital grant increases the asset's book value, with depreciation revised prospectively. (Ind AS entities follow Ind AS 20.)
(e) Extended tax liability of an assessee
An assessee is taxed mainly on his own income, but the Income-tax Act, 1961 (replaced by the Income-tax Act, 2025 from 1.4.2026, which carries these rules forward under new section numbers) extends his liability in three ways.
Clubbing of income: income transferred without the asset (Section 60), income from revocable transfers (61–63), and certain income of a spouse or minor child, such as a spouse's remuneration from a concern in which the assessee has a substantial interest (Section 64), is added to the assessee's total income to stop avoidance.
Representative assessee: the tax on a non-resident's Indian income may be recovered from his agent, and trustees, guardians and managers are assessed on behalf of minors or persons of unsound mind (Sections 160 to 163).
Successor liability: the legal representative of a deceased person (Section 159) is liable up to the estate inherited, and the partners of a firm are liable for its unpaid tax.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Comprehensive, accurate, well-structured, with specific references to laws/standards.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Explain what buyback of shares is and its reasons and sources. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Buyback is purchase of own shares under Sections 68–70; shares are extinguished
- Reasons: surplus cash, EPS and ROE, share price support, takeover defence
- Sources: free reserves, securities premium, proceeds of a fresh issue of a different kind
- Limits: 25% ceiling, debt-equity 2 : 1, board or special resolution
Loses marks
- Saying that the bought-back shares are held as treasury shares.
Earns more
- Marks for the meaning, reasons, sources and statutory limits.
Extra mark
- Mentioning the Capital Redemption Reserve and SEBI regulations.
- (b) Comment on the growing relevance of cost accounting in India. 10 marks · 150 words
comment— context → arguments both sides → judgment → close
Must cover
- Competition and margin pressure need costing for pricing and cost reduction
- Regulated pricing, GST, services and MSME needs
- Section 148 cost records and cost audit
- Judgement: relevance depends on accuracy and use by management
Loses marks
- Only listing points without taking a position.
Earns more
- Marks for reasons, the statutory basis and a reasoned judgement.
Extra mark
- Citing tools such as activity-based costing.
- (c) Explain the major points an auditor considers in auditing a non-profit organisation. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Governing documents and minutes
- Verification of receipts, donations and grants, with restricted funds
- Expenses, assets and investments
- Compliance: 12A/12AB, 85% application, FCRA; true and fair financial statements
Loses marks
- Treating it as a company audit and ignoring the trust deed.
Earns more
- Marks for documents, receipts, expenditure and compliance points.
Extra mark
- Mentioning utilisation certificates.
- (d) Explain the accounting treatment of government grants under AS-12. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Recognition only with reasonable assurance of compliance and receipt
- Revenue grants credited to profit and loss over the related cost periods
- Capital grants deducted from cost or shown as deferred income
- Promoter's contribution to capital reserve; refund treatment; non-monetary grants
Loses marks
- Crediting all grants to profit and loss immediately.
Earns more
- Marks for recognition, revenue and capital grant treatment, and refund.
Extra mark
- Noting that Ind AS 20 applies to Ind AS entities.
- (e) Explain how an assessee's tax liability can extend to other incomes. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Clubbing under Sections 60–64
- Representative assessee under Sections 160–163
- Successor liability under Section 159 and firm partners
- Reference to the Income-tax Act, 2025 from 1.4.2026
Loses marks
- Confusing clubbing with exemption or set-off.
Earns more
- Marks for clubbing, representative assessee and successor liability.
Extra mark
- Explaining the anti-avoidance purpose.
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q1 Answer the following questions in about 150 words each: (a) What is meant by buyback of s…
- Q2 (a) The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liab…
- Q3 (a) From the following information, prepare Process A/cs and calculate the actual profits…
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…