Paper I — Q3
(a) From the following information, prepare Process A/cs and calculate the actual profits earned by X Ltd. for the month of April…
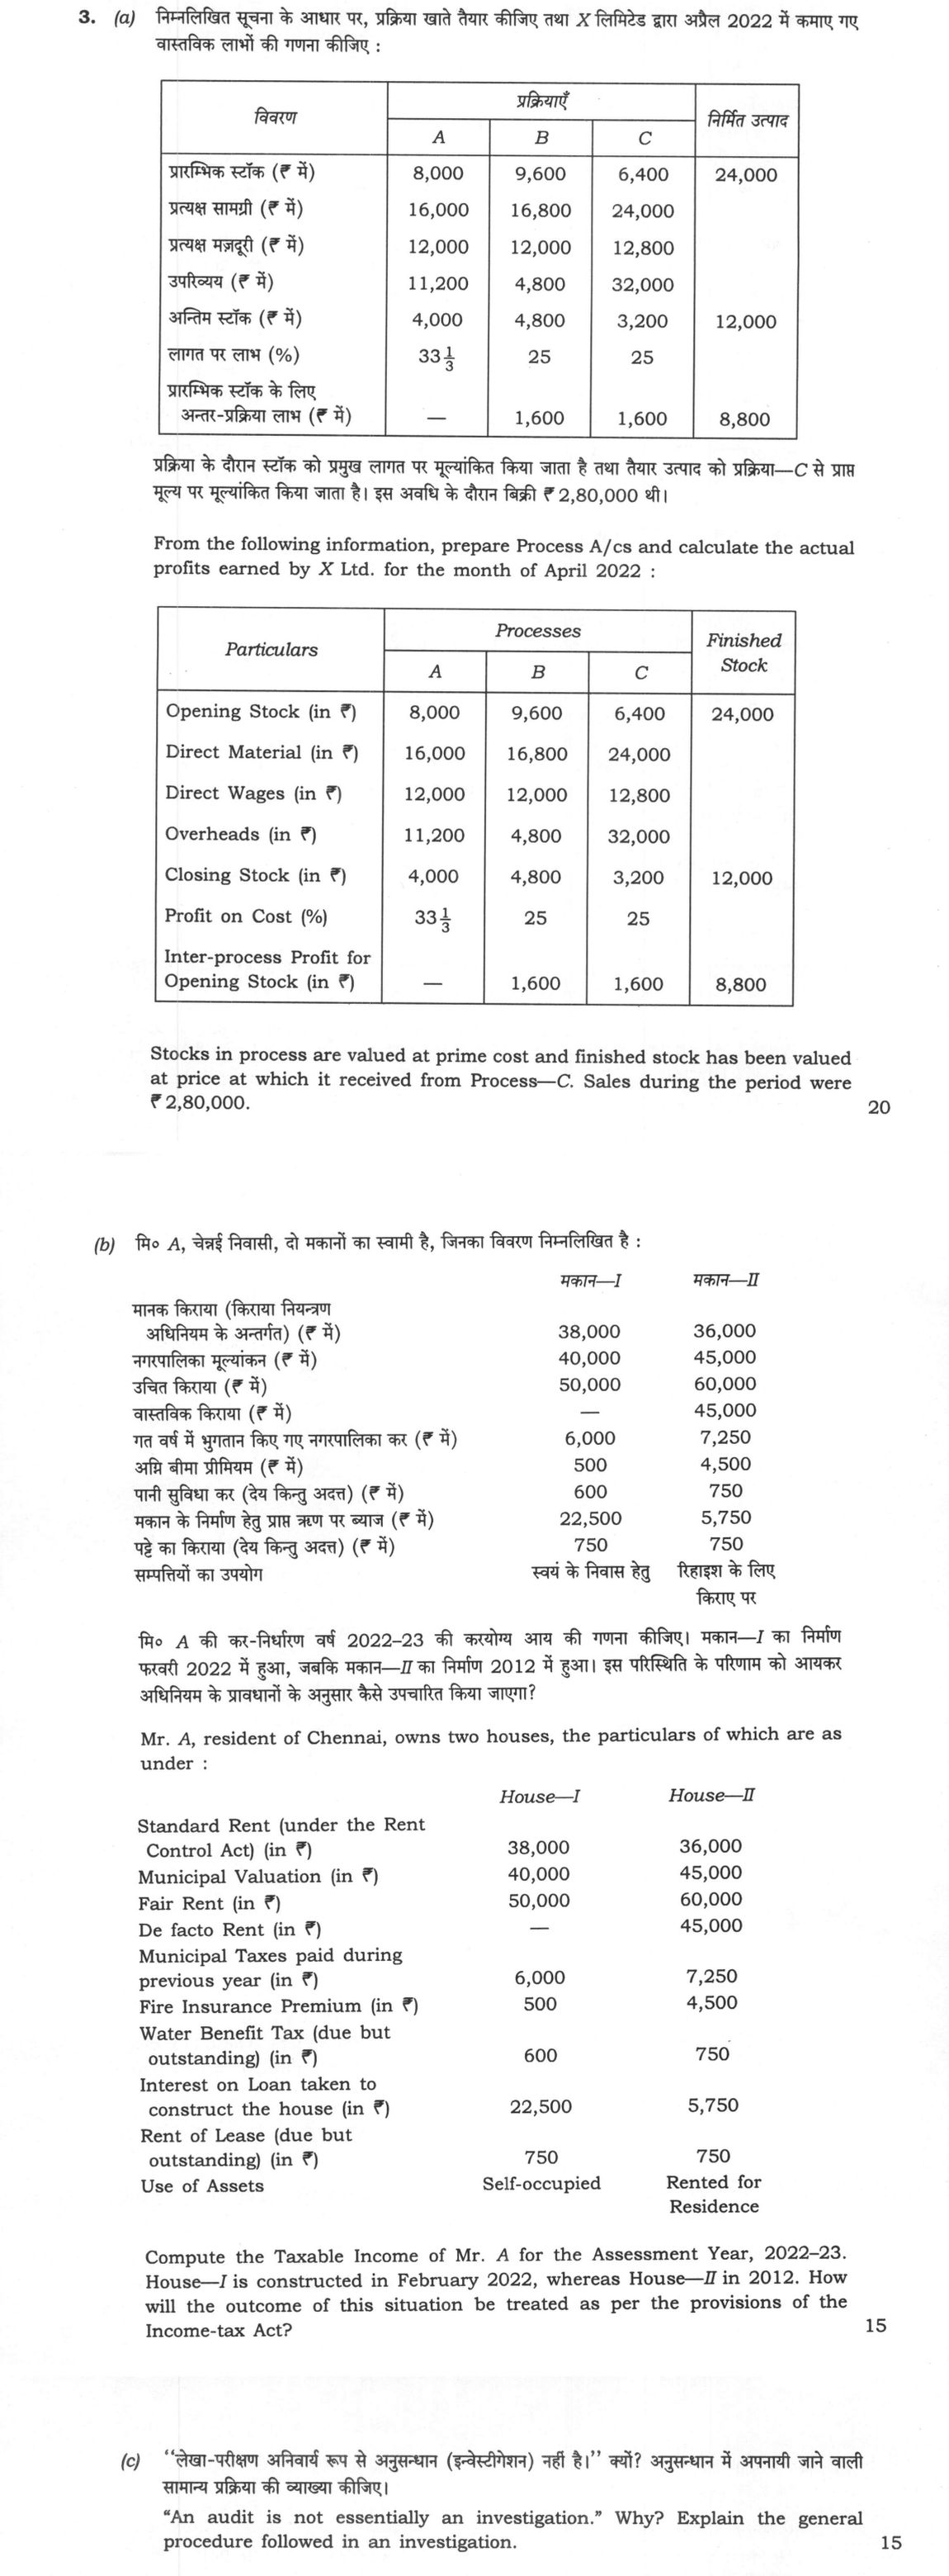
From the following information, prepare Process A/cs and calculate the actual profits earned by X Ltd. for the month of April 2022 (₹): Process A: Opening stock 8,000; Direct material 16,000; Direct wages 12,000; Overheads 11,200; Closing stock 4,000; Profit on cost 33⅓%; Inter-process profit in opening stock —. Process B: Opening stock 9,600; Direct material 16,800; Direct wages 12,000; Overheads 4,800; Closing stock 4,800; Profit on cost 25%; Inter-process profit in opening stock 1,600. Process C: Opening stock 6,400; Direct material 24,000; Direct wages 12,800; Overheads 32,000; Closing stock 3,200; Profit on cost 25%; Inter-process profit in opening stock 1,600. Finished stock: Opening stock 24,000; Closing stock 12,000; Inter-process profit in opening stock 8,800. Stocks in process are valued at prime cost and finished stock has been valued at price at which it received from Process—C. Sales during the period were ₹ 2,80,000. 20 marks
Mr. A, resident of Chennai, owns two houses, the particulars of which are as under (House—I : House—II, in ₹): Standard Rent (under the Rent Control Act) 38,000 : 36,000 Municipal Valuation 40,000 : 45,000 Fair Rent 50,000 : 60,000 De facto Rent — : 45,000 Municipal Taxes paid during previous year 6,000 : 7,250 Fire Insurance Premium 500 : 4,500 Water Benefit Tax (due but outstanding) 600 : 750 Interest on Loan taken to construct the house 22,500 : 5,750 Rent of Lease (due but outstanding) 750 : 750 Use of Assets: House—I Self-occupied; House—II Rented for Residence. Compute the Taxable Income of Mr. A for the Assessment Year, 2022-23. House—I is constructed in February 2022, whereas House—II in 2012. How will the outcome of this situation be treated as per the provisions of the Income-tax Act? 15 marks
"An audit is not essentially an investigation." Why? Explain the general procedure followed in an investigation. 15 marks
हिंदी में प्रश्न पढ़ें
(क) निम्नलिखित सूचना के आधार पर, प्रक्रिया खाते तैयार कीजिए तथा X लिमिटेड द्वारा अप्रैल 2022 में कमाए गए वास्तविक लाभों की गणना कीजिए (₹): प्रक्रिया A: प्रारम्भिक स्टॉक 8,000; प्रत्यक्ष सामग्री 16,000; प्रत्यक्ष मज़दूरी 12,000; उपरिव्यय 11,200; अन्तिम स्टॉक 4,000; लागत पर लाभ 33⅓%; प्रारम्भिक स्टॉक के लिए अन्तर-प्रक्रिया लाभ —। प्रक्रिया B: प्रारम्भिक स्टॉक 9,600; प्रत्यक्ष सामग्री 16,800; प्रत्यक्ष मज़दूरी 12,000; उपरिव्यय 4,800; अन्तिम स्टॉक 4,800; लागत पर लाभ 25%; प्रारम्भिक स्टॉक के लिए अन्तर-प्रक्रिया लाभ 1,600। प्रक्रिया C: प्रारम्भिक स्टॉक 6,400; प्रत्यक्ष सामग्री 24,000; प्रत्यक्ष मज़दूरी 12,800; उपरिव्यय 32,000; अन्तिम स्टॉक 3,200; लागत पर लाभ 25%; प्रारम्भिक स्टॉक के लिए अन्तर-प्रक्रिया लाभ 1,600। निर्मित उत्पाद: प्रारम्भिक स्टॉक 24,000; अन्तिम स्टॉक 12,000; प्रारम्भिक स्टॉक के लिए अन्तर-प्रक्रिया लाभ 8,800। प्रक्रिया के दौरान स्टॉक को प्रमुख लागत पर मूल्यांकित किया जाता है तथा तैयार उत्पाद को प्रक्रिया—C से प्राप्त मूल्य पर मूल्यांकित किया जाता है। इस अवधि के दौरान बिक्री ₹ 2,80,000 थी। (20 अंक)
(ख) मि० A, चेन्नई निवासी, दो मकानों का स्वामी है, जिनका विवरण निम्नलिखित है (मकान—I : मकान—II, ₹ में): मानक किराया (किराया नियन्त्रण अधिनियम के अन्तर्गत) 38,000 : 36,000 नगरपालिका मूल्यांकन 40,000 : 45,000 उचित किराया 50,000 : 60,000 वास्तविक किराया — : 45,000 गत वर्ष में भुगतान किए गए नगरपालिका कर 6,000 : 7,250 अग्नि बीमा प्रीमियम 500 : 4,500 पानी सुविधा कर (देय किन्तु अदत्त) 600 : 750 मकान के निर्माण हेतु प्राप्त ऋण पर ब्याज 22,500 : 5,750 पट्टे का किराया (देय किन्तु अदत्त) 750 : 750 सम्पत्तियों का उपयोग: मकान—I स्वयं के निवास हेतु; मकान—II रिहाइश के लिए किराए पर। मि० A की कर-निर्धारण वर्ष 2022-23 की करयोग्य आय की गणना कीजिए। मकान—I का निर्माण फरवरी 2022 में हुआ, जबकि मकान—II का निर्माण 2012 में हुआ। इस परिस्थिति के परिणाम को आयकर अधिनियम के प्रावधानों के अनुसार कैसे उपचारित किया जाएगा? (15 अंक)
(ग) "लेखा-परीक्षण अनिवार्य रूप से अनुसन्धान (इन्वेस्टिगेशन) नहीं है।" क्यों? अनुसन्धान में अपनायी जाने वाली सामान्य प्रक्रिया की व्याख्या कीजिए। (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Table with columns: Particulars, Process A, Process B, Process C, Finished Stock. Rows: Opening Stock (in Rs.): 8,000, 9,600, 6,400, 24,000 Direct Material (in Rs.): 16,000, 16,800, 24,000, - Direct Wages (in Rs.): 12,000, 12,000, 12,800, - Overheads (in Rs.): 11,200, 4,800, 32,000, - Closing Stock (in Rs.): 4,000, 4,800, 3,200, 12,000 Profit on Cost (%): 33 1/3, 25, 25, - Inter-process Profit for Opening Stock (in Rs.): -, 1,600, 1,600, 8,800
(b) Table with columns 'House-I' and 'House-II' and the following rows: Standard Rent (under the Rent Control Act) (in Rs): 38,000 and 36,000; Municipal Valuation (in Rs): 40,000 and 45,000; Fair Rent (in Rs): 50,000 and 60,000; De facto Rent (in Rs): - and 45,000; Municipal Taxes paid during previous year (in Rs): 6,000 and 7,250; Fire Insurance Premium (in Rs): 500 and 4,500; Water Benefit Tax (due but outstanding) (in Rs): 600 and 750; Interest on Loan taken to construct the house (in Rs): 22,500 and 5,750; Rent of Lease (due but outstanding) (in Rs): 750 and 750; Use of Assets: Self-occupied and Rented for Residence.
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Process accounts and actual profit
Stock in process is valued at prime cost (so it carries no profit of its own), and finished stock at the Process C transfer price. Each process takes the previous transfer at its transfer price and adds 33⅓% (A) or 25% (B, C) on its own total cost.
Process A account (₹): Debit: opening stock 8,000; direct material 16,000; direct wages 12,000; overheads 11,200. Credit: closing stock 4,000. Cost of the process = 47,200 − 4,000 = 43,200. Profit at 33⅓% on cost = 14,400. Transfer to B = 57,600.
Process B account (₹): Debit: opening stock 9,600; transfer from A 57,600; direct material, wages and overheads 16,800 + 12,000 + 4,800 = 33,600. Credit: closing stock 4,800. Cost = 1,00,800 − 4,800 = 96,000. Profit at 25% = 24,000. Transfer to C = 1,20,000.
Process C account (₹): Debit: opening stock 6,400; transfer from B 1,20,000; direct material, wages and overheads 24,000 + 12,800 + 32,000 = 68,800. Credit: closing stock 3,200. Cost = 1,95,200 − 3,200 = 1,92,000. Profit at 25% = 48,000. Transfer to finished stock = 2,40,000.
Finished stock account (₹): Opening stock 24,000 + transfer from C 2,40,000 = 2,64,000; less closing stock 12,000 gives cost of goods sold 2,52,000. Sales 2,80,000 − 2,52,000 = profit of 28,000 on sales.
Inter-process profit adjustment. Profit in the opening stocks, as given, is 1,600 + 1,600 + 8,800 = 12,000, and it is realised this month. Profit in the closing stocks is not yet realised:
- Closing stock of A is at prime cost, so nil.
- Closing stock of B: 4,800 × 14,400 / 57,600 = 1,200.
- Closing stock of C: 3,200 × (14,400 + 24,000) / 1,20,000 = 1,024.
- Finished stock: 12,000 × (14,400 + 24,000 + 48,000) / 2,40,000 = 4,320.
Closing reserve = 6,544.
Profit shown by the books = 14,400 + 24,000 + 48,000 + 28,000 = 1,14,400 (the 28,000 is the profit on the sale of finished stock).
Actual profit = 1,14,400 + 12,000 (opening reserve released) − 6,544 (closing reserve) = ₹1,19,856.
(b) House property income, AY 2022-23
House I (self-occupied, built February 2022). Gross annual value is nil (Section 23(2)). Municipal tax is not allowed for a self-occupied house. Interest on the construction loan, ₹22,500, is allowed under Section 24(b), as construction was completed in the previous year (limit ₹2,00,000). Income = (−) ₹22,500.
House II (let for residence, built 2012). Expected rent is the higher of municipal valuation (45,000) and fair rent (60,000), which is 60,000, but limited to the standard rent of 36,000. So expected rent = 36,000. Actual rent received = 45,000. Gross annual value = the higher, 45,000.
Less municipal taxes paid during the year: 7,250. Net annual value = 37,750.
Less standard deduction under Section 24(a), 30% of NAV: 11,325. Less interest under Section 24(b): 5,750. Income = 37,750 − 11,325 − 5,750 = ₹20,675.
Fire insurance premium, unpaid water benefit tax and unpaid lease rent are not deductible: Section 24 allows only the standard deduction and interest, and insurance and ground rent are covered by the 30%. (Municipal taxes are allowed only when actually paid.)
Income from house property = 20,675 − 22,500 = (−) ₹1,825.
Treatment of the loss. It arises from interest on a self-occupied house, so it can be set off against income from other heads in the same year under Section 71(3A), up to ₹2,00,000. The ₹1,825 loss is fully within this limit and is set off against other income such as salary. Any unabsorbed amount would be carried forward for 8 assessment years under Section 71B against house property income only. (The Income-tax Act, 2025 re-enacts these provisions from 1.4.2026.)
(c) Audit and investigation
Why an audit is not essentially an investigation. An audit examines whether the financial statements give a true and fair view under an accounting framework, and it ends in an opinion. It is periodic and often statutory, it relies on sampling and test checks, and its scope is set by law or engagement. An investigation is a special enquiry into a specific matter, such as fraud, the value of a business, or the profitability of a proposed venture. It is done for a particular person, without a fixed standard form, goes to the roots of transactions, and often covers several years. An audit can reveal something that needs investigation, but it does not of itself become one.
General procedure of an investigation.
- Fix the terms of reference and the scope, and obtain authority and access to records.
- Plan the work and form a team with the skills needed (accounting, legal, forensic).
- Collect evidence: books, bank records, contracts, third-party confirmations, and interviews.
- Analyse and verify it, tracing transactions to their source and testing for the matter investigated.
- Quantify the findings and cross-check them.
- Report in writing to the person who commissioned the investigation, with findings, conclusions and recommendations, and follow up.
How this answer will be evaluated
What earns full marks: Complete workings, correct formats, all statutory provisions cited, clear distinctions made
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Prepare Process A, B and C accounts and the finished stock account, and compute the actual profit. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Process costs at prime-cost stock valuation: A transfer 57,600, B transfer 1,20,000, C transfer 2,40,000
- Profit on each process: 14,400, 24,000 and 48,000; finished stock profit on sales 28,000
- Unrealised profit in closing stock 6,544 (1,200 + 1,024 + 4,320) and opening reserve 12,000
- Actual profit = 1,14,400 + 12,000 − 6,544 = ₹1,19,856
Loses marks
- Loading profit on the opening stocks twice or ignoring the closing reserve.
Earns more
- Marks for each process account, the reserve workings and the final actual profit.
Extra mark
- Showing the finished stock account and cost of goods sold of 2,52,000.
- (b) Compute the income from house property of Mr. A for AY 2022-23 and explain the treatment of the result. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- House I self-occupied: GAV nil, interest 22,500 allowed
- House II: expected rent limited by standard rent, GAV 45,000, NAV 37,750
- Deductions: 30% (11,325) and interest 5,750; income 20,675
- Net (−) 1,825, set off under Section 71(3A) up to ₹2,00,000 with carry-forward under Section 71B
Loses marks
- Deducting unpaid taxes or insurance, or taking the fair rent as the GAV.
Earns more
- Marks for GAV and NAV working, deductions, the net result and the set-off treatment.
Extra mark
- Noting that insurance, unpaid water tax and unpaid rent are not deductible.
- (c) Explain why an audit is not essentially an investigation and describe the general procedure of an investigation. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Audit: opinion on true and fair view, periodic, test-based, legally defined scope
- Investigation: special enquiry into a specific matter, for a particular person, in depth
- Procedure: terms of reference, plan and team, collect and verify evidence
- Findings quantified and a written report with recommendations
Loses marks
- Giving a long general description of audit instead of the contrast.
Earns more
- Marks for contrasting the two and listing the steps in order.
Extra mark
- Citing examples such as fraud or valuation of a business.
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q1 Answer the following questions in about 150 words each: (a) What is meant by buyback of s…
- Q2 (a) The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liab…
- Q3 (a) From the following information, prepare Process A/cs and calculate the actual profits…
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…
- Q6 (a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company i…