Paper I — Q2
(a) The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liabilities 1. Shareholders' Funds: (a)…
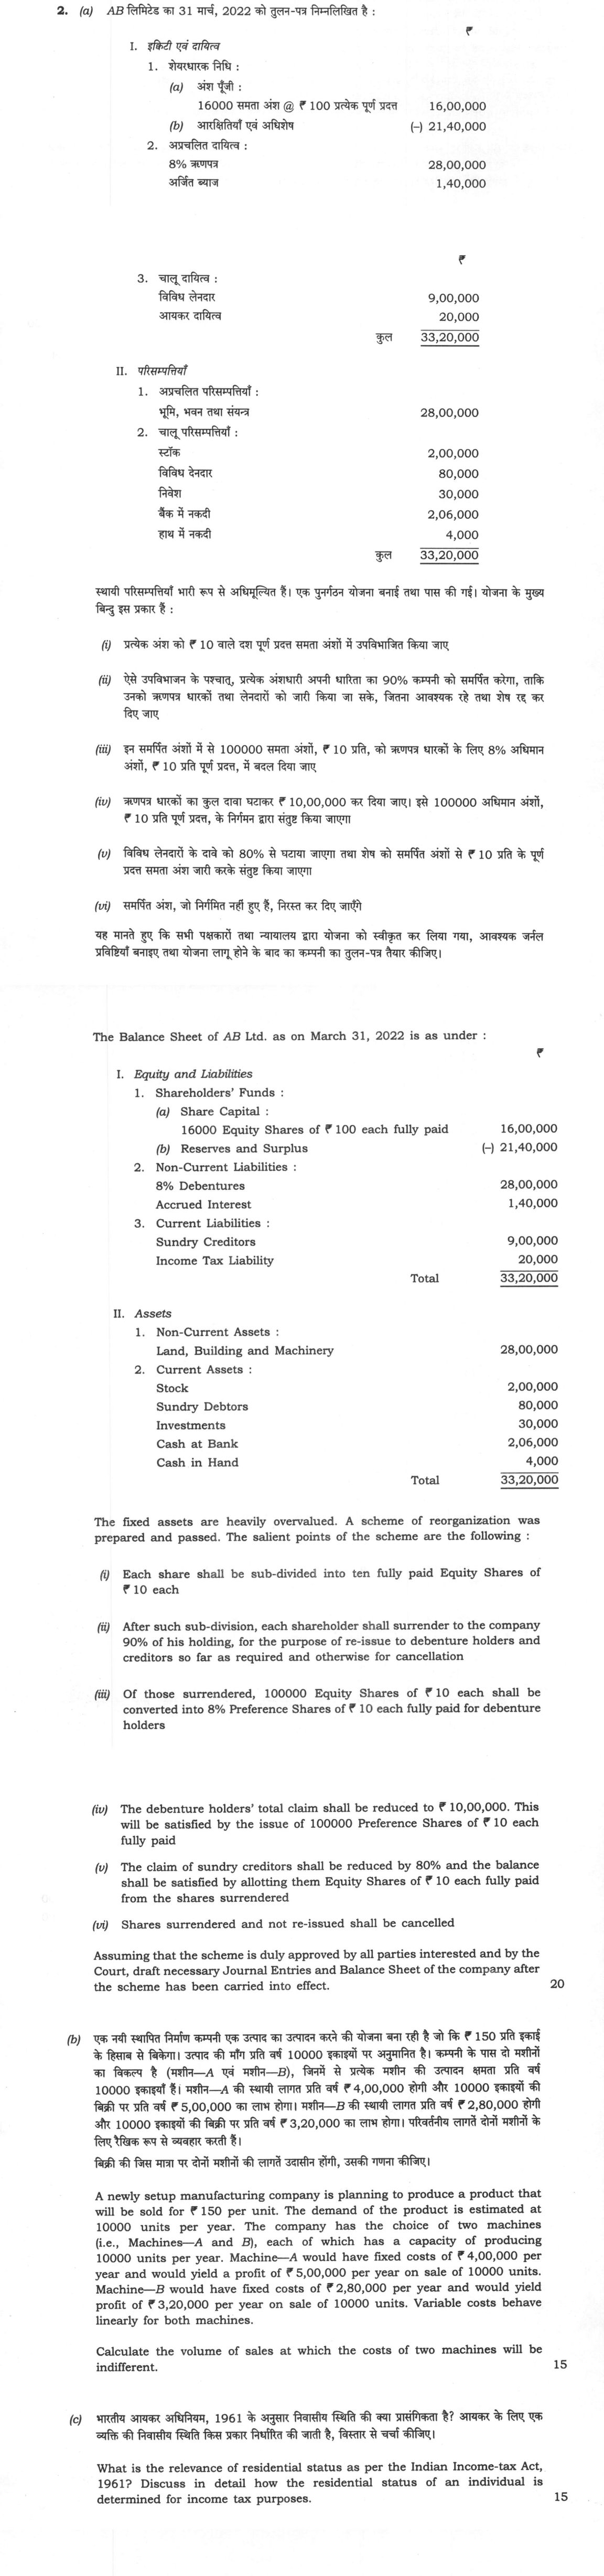
The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liabilities 1. Shareholders' Funds: (a) Share Capital: 16000 Equity Shares of ₹ 100 each fully paid 16,00,000; (b) Reserves and Surplus (−) 21,40,000 2. Non-Current Liabilities: 8% Debentures 28,00,000; Accrued Interest 1,40,000 3. Current Liabilities: Sundry Creditors 9,00,000; Income Tax Liability 20,000 Total 33,20,000 II. Assets 1. Non-Current Assets: Land, Building and Machinery 28,00,000 2. Current Assets: Stock 2,00,000; Sundry Debtors 80,000; Investments 30,000; Cash at Bank 2,06,000; Cash in Hand 4,000 Total 33,20,000 The fixed assets are heavily overvalued. A scheme of reorganization was prepared and passed. The salient points of the scheme are the following : Each share shall be sub-divided into ten fully paid Equity Shares of ₹ 10 each
After such sub-division, each shareholder shall surrender to the company 90% of his holding, for the purpose of re-issue to debenture holders and creditors so far as required and otherwise for cancellation
Of those surrendered, 100000 Equity Shares of ₹ 10 each shall be converted into 8% Preference Shares of ₹ 10 each fully paid for debenture holders
The debenture holders' total claim shall be reduced to ₹ 10,00,000. This will be satisfied by the issue of 100000 Preference Shares of ₹ 10 each fully paid
The claim of sundry creditors shall be reduced by 80% and the balance shall be satisfied by allotting them Equity Shares of ₹ 10 each fully paid from the shares surrendered
Shares surrendered and not re-issued shall be cancelled Assuming that the scheme is duly approved by all parties interested and by the Court, draft necessary Journal Entries and Balance Sheet of the company after the scheme has been carried into effect. 20 marks
A newly setup manufacturing company is planning to produce a product that will be sold for ₹ 150 per unit. The demand of the product is estimated at 10000 units per year. The company has the choice of two machines (i.e., Machines—A and B), each of which has a capacity of producing 10000 units per year. Machine—A would have fixed costs of ₹ 4,00,000 per year and would yield a profit of ₹ 5,00,000 per year on sale of 10000 units. Machine—B would have fixed costs of ₹ 2,80,000 per year and would yield profit of ₹ 3,20,000 per year on sale of 10000 units. Variable costs behave linearly for both machines. Calculate the volume of sales at which the costs of two machines will be indifferent. 15 marks
What is the relevance of residential status as per the Indian Income-tax Act, 1961? Discuss in detail how the residential status of an individual is determined for income tax purposes. 15 marks
हिंदी में प्रश्न पढ़ें
(क) AB लिमिटेड का 31 मार्च, 2022 को तुलन-पत्र निम्नलिखित है (₹): I. इक्विटी एवं दायित्व 1. शेयरधारक निधि: (a) अंश पूँजी: 16000 समता अंश @ ₹ 100 प्रत्येक पूर्ण प्रदत्त 16,00,000; (b) आरक्षितियाँ एवं अधिशेष (−) 21,40,000 2. अप्रचलित दायित्व: 8% ऋणपत्र 28,00,000; अर्जित ब्याज 1,40,000 3. चालू दायित्व: विविध लेनदार 9,00,000; आयकर दायित्व 20,000 कुल 33,20,000 II. परिसम्पत्तियाँ 1. अप्रचलित परिसम्पत्तियाँ: भूमि, भवन तथा संयन्त्र 28,00,000 2. चालू परिसम्पत्तियाँ: स्टॉक 2,00,000; विविध देनदार 80,000; निवेश 30,000; बैंक में नकदी 2,06,000; हाथ में नकदी 4,000 कुल 33,20,000 स्थायी परिसम्पत्तियाँ भारी रूप से अधिमूल्यित हैं। एक पुनर्गठन योजना बनाई तथा पास की गई। योजना के मुख्य बिन्दु इस प्रकार हैं : प्रत्येक अंश को ₹ 10 वाले दस पूर्ण प्रदत्त समता अंशों में उपविभाजित किया जाए
ऐसे उपविभाजन के पश्चात्, प्रत्येक अंशधारी अपनी धारिता का 90% कम्पनी को समर्पित करेगा, ताकि उनको ऋणपत्र धारकों तथा लेनदारों को जारी किया जा सके, जितना आवश्यक रहे तथा शेष रद्द कर दिए जाएँ
इन समर्पित अंशों में से 100000 समता अंशों, ₹ 10 प्रति, को ऋणपत्र धारकों के लिए 8% अधिमान अंशों, ₹ 10 प्रति पूर्ण प्रदत्त, में बदल दिया जाए
ऋणपत्र धारकों का कुल दावा घटाकर ₹ 10,00,000 कर दिया जाए। इसे 100000 अधिमान अंशों, ₹ 10 प्रति पूर्ण प्रदत्त, के निर्गमन द्वारा संतुष्ट किया जाएगा
विविध लेनदारों के दावे को 80% से घटाया जाएगा तथा शेष को समर्पित अंशों से ₹ 10 प्रति के पूर्ण प्रदत्त समता अंश जारी करके संतुष्ट किया जाएगा
समर्पित अंश, जो निर्गमित नहीं हुए हैं, निरस्त कर दिए जाएँगे यह मानते हुए कि सभी पक्षकारों तथा न्यायालय द्वारा योजना को स्वीकृत कर लिया गया, आवश्यक जर्नल प्रविष्टियाँ बनाइए तथा योजना लागू होने के बाद का कम्पनी का तुलन-पत्र तैयार कीजिए। (20 अंक)
(ख) एक नयी स्थापित निर्माण कम्पनी एक उत्पाद का उत्पादन करने की योजना बना रही है जो कि ₹ 150 प्रति इकाई के हिसाब से बिकेगा। उत्पाद की माँग प्रति वर्ष 10000 इकाइयों पर अनुमानित है। कम्पनी के पास दो मशीनों का विकल्प है (मशीन—A एवं मशीन—B), जिनमें से प्रत्येक मशीन की उत्पादन क्षमता प्रति वर्ष 10000 इकाइयाँ हैं। मशीन—A की स्थायी लागत प्रति वर्ष ₹ 4,00,000 होगी और 10000 इकाइयों की बिक्री पर प्रति वर्ष ₹ 5,00,000 का लाभ होगा। मशीन—B की स्थायी लागत प्रति वर्ष ₹ 2,80,000 होगी और 10000 इकाइयों की बिक्री पर प्रति वर्ष ₹ 3,20,000 का लाभ होगा। परिवर्तनीय लागतें दोनों मशीनों के लिए रैखिक रूप से व्यवहार करती हैं। बिक्री की जिस मात्रा पर दोनों मशीनों की लागतें उदासीन होंगी, उसकी गणना कीजिए। (15 अंक)
(ग) भारतीय आयकर अधिनियम, 1961 के अनुसार निवासीय स्थिति की क्या प्रासंगिकता है? आयकर के लिए एक व्यक्ति की निवासीय स्थिति किस प्रकार निर्धारित की जाती है, विस्तार से चर्चा कीजिए। (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Balance Sheet of AB Limited as on 31st March, 2022 (Amount in ₹)
I. Equity and Liabilities
- Shareholders' Funds: (a) Share Capital: 16,000 Equity Shares @ ₹ 100 each fully paid: 16,00,000 (b) Reserves and Surplus: 21,40,000
- Non-current Liabilities: 8% Debentures: 28,00,000 Accrued Interest: 1,40,000
II. Assets
- Non-Current Assets: Fixed Assets: (a) Tangible Assets: Plant & Machinery: 2,80,000 Land & Building: 2,00,000 Furniture & Fittings: 1,56,000 Subtotal: 6,36,000 Less: Provision for Depreciation: 1,48,000 Net Tangible Assets: 4,88,000 (b) Intangible Assets: Goodwill: 80,000 Investments: 3,00,000
- Current Assets: Current Assets: 4,40,000 Prepaid Rent: 4,000 Unamortized Preliminary Expenses: 20,000 Total: 13,32,000
(b) Table with columns: Item, House-I, House-II. Rows: Standard Rent (under the Rent Control Act) (in Rs) 38,000 36,000; Municipal Valuation (in Rs) 40,000 45,000; Fair Rent (in Rs) 50,000 60,000; De facto Rent (in Rs) - 45,000; Municipal Taxes paid during previous year (in Rs) 6,000 7,250; Fire Insurance Premium (in Rs) 500 4,500; Water Benefit Tax (due but outstanding) (in Rs) 600 750; Interest on Loan taken to construct the house (in Rs) 22,500 5,750; Rent of Lease (due but outstanding) (in Rs) 750 750; Use of Assets Self-occupied Rented for Residence.
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Reconstruction of AB Ltd.
Working: 16,000 shares of ₹100 become 1,60,000 shares of ₹10. Surrendered 90% = 1,44,000 shares (₹14,40,000). Debenture holders' claim = 28,00,000 + 1,40,000 interest = ₹29,40,000, settled by 1,00,000 preference shares of ₹10 (₹10,00,000). Creditors' claim is cut by 80%, so ₹1,80,000 remains and is settled by 18,000 equity shares. Surrendered shares cancelled = 1,44,000 − 1,00,000 − 18,000 = 26,000.
Journal entries (₹):
(1) Equity share capital (₹100) Dr 16,00,000; To Equity share capital (₹10) 16,00,000, for sub-division.
(2) Equity share capital (₹10) Dr 14,40,000; To Capital reduction account 14,40,000, for the surrender of 90% of the shares.
(3) 8% Debentures Dr 28,00,000; Accrued interest Dr 1,40,000; To 8% Preference share capital 10,00,000; To Capital reduction account 19,40,000, for settlement of the debenture holders.
(4) Sundry creditors Dr 9,00,000; To Equity share capital 1,80,000; To Capital reduction account 7,20,000, for settlement of the creditors.
(5) Capital reduction account Dr 41,00,000 (14,40,000 + 19,40,000 + 7,20,000); To Reserves and surplus (debit balance) 21,40,000; To Land, building and machinery 19,60,000, to write off the accumulated loss and reduce the overvalued fixed assets. (The 26,000 shares cancelled need no separate entry.)
Balance sheet after reconstruction: Equity and liabilities: equity share capital (34,000 shares of ₹10) 3,40,000; 8% preference share capital 10,00,000; income tax liability 20,000; total 13,60,000. Assets: land, building and machinery 8,40,000; stock 2,00,000; sundry debtors 80,000; investments 30,000; cash at bank 2,06,000; cash in hand 4,000; total 13,60,000.
(b) Indifference point of the two machines
Sales at 10,000 units = 10,000 × 150 = ₹15,00,000.
Machine A: total cost = 15,00,000 − 5,00,000 = 10,00,000; variable cost = 10,00,000 − 4,00,000 = 6,00,000, so ₹60 per unit.
Machine B: total cost = 15,00,000 − 3,20,000 = 11,80,000; variable cost = 11,80,000 − 2,80,000 = 9,00,000, so ₹90 per unit.
At indifference, total costs are equal: 4,00,000 + 60x = 2,80,000 + 90x, so 30x = 1,20,000 and x = 4,000 units, where the cost is ₹6,40,000 on either machine.
Below 4,000 units Machine B (lower fixed cost) is cheaper, and above it Machine A (lower variable cost) is cheaper. At the expected demand of 10,000 units, Machine A is better, with a profit of ₹5,00,000 against ₹3,20,000.
(c) Residential status under the Income-tax Act
Relevance: the status decides the scope of taxable income under Section 5. A resident and ordinarily resident (ROR) is taxed on global income. A resident but not ordinarily resident (RNOR) is taxed on Indian income and on income from a business controlled in or a profession set up in India; a non-resident (NR) is taxed only on Indian income. It is found each previous year and also matters for treaty benefits.
Test for an individual (Section 6): he is resident if (i) he stays in India for 182 days or more in the previous year, or (ii) he stays 60 days or more in the year and 365 days or more in the 4 preceding years. For an Indian citizen or person of Indian origin who leaves India for employment abroad or as a crew member, or who visits India, 182 days replaces 60 days; for a visitor whose Indian income exceeds ₹15 lakh, 120 days applies. A citizen with Indian income above ₹15 lakh who is not taxable in any other country is deemed resident, but only as RNOR.
A resident is ROR if he has been resident in at least 2 of the 10 preceding years and has stayed 730 days or more in the 7 preceding years; otherwise he is RNOR.
(The Income-tax Act, 2025, in force from 1.4.2026, carries the residency rules forward under new section numbers.)
How this answer will be evaluated
What earns full marks: Precise calculations, correct legal references, and clear logical flow.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Pass the journal entries for the reconstruction of AB Ltd. and prepare the balance sheet after the scheme. 20 marks
trace— start point → the stages in sequence → end point → what changed
Must cover
- Sub-division: 1,60,000 shares of ₹10; surrender 1,44,000
- Debenture holders' claim ₹29,40,000 settled by ₹10,00,000 preference shares; creditors' ₹1,80,000 by 18,000 equity shares
- Capital reduction account credited with 14,40,000 + 19,40,000 + 7,20,000 = 41,00,000
- Write off ₹21,40,000 loss and ₹19,60,000 of fixed assets; balance sheet total ₹13,60,000
Loses marks
- Omitting the accrued interest from the debenture holders' claim.
Earns more
- Marks for each journal entry and the balance sheet with correct totals.
Extra mark
- Stating that 26,000 shares are cancelled.
- (b) Find the sales volume at which the costs of the two machines are equal. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Variable cost per unit: A ₹60 and B ₹90
- Equate 4,00,000 + 60x = 2,80,000 + 90x
- x = 4,000 units
- A is better at the demand of 10,000 units
Loses marks
- Using profit instead of cost to find variable cost.
Earns more
- Marks for deriving the variable costs, the equation and the result.
Extra mark
- Stating the cost at indifference (₹6,40,000).
- (c) Discuss the relevance of residential status and how it is determined for an individual. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Relevance: scope of income under Section 5 for ROR, RNOR and NR
- Basic tests: 182 days, or 60 days plus 365 days in 4 years
- Special cases: citizen leaving or visiting India; 120 days; deemed resident
- ROR if resident in 2 of 10 years and 730 days in 7 years; otherwise RNOR
Loses marks
- Applying the 60-day test to a citizen leaving for employment.
Earns more
- Marks for the relevance, the basic tests, the special rules and the ROR test.
Extra mark
- Noting the Income-tax Act, 2025 from 1.4.2026.
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q1 Answer the following questions in about 150 words each: (a) What is meant by buyback of s…
- Q2 (a) The Balance Sheet of AB Ltd. as on March 31, 2022 is as under (₹): I. Equity and Liab…
- Q3 (a) From the following information, prepare Process A/cs and calculate the actual profits…
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…