Paper I — Q7
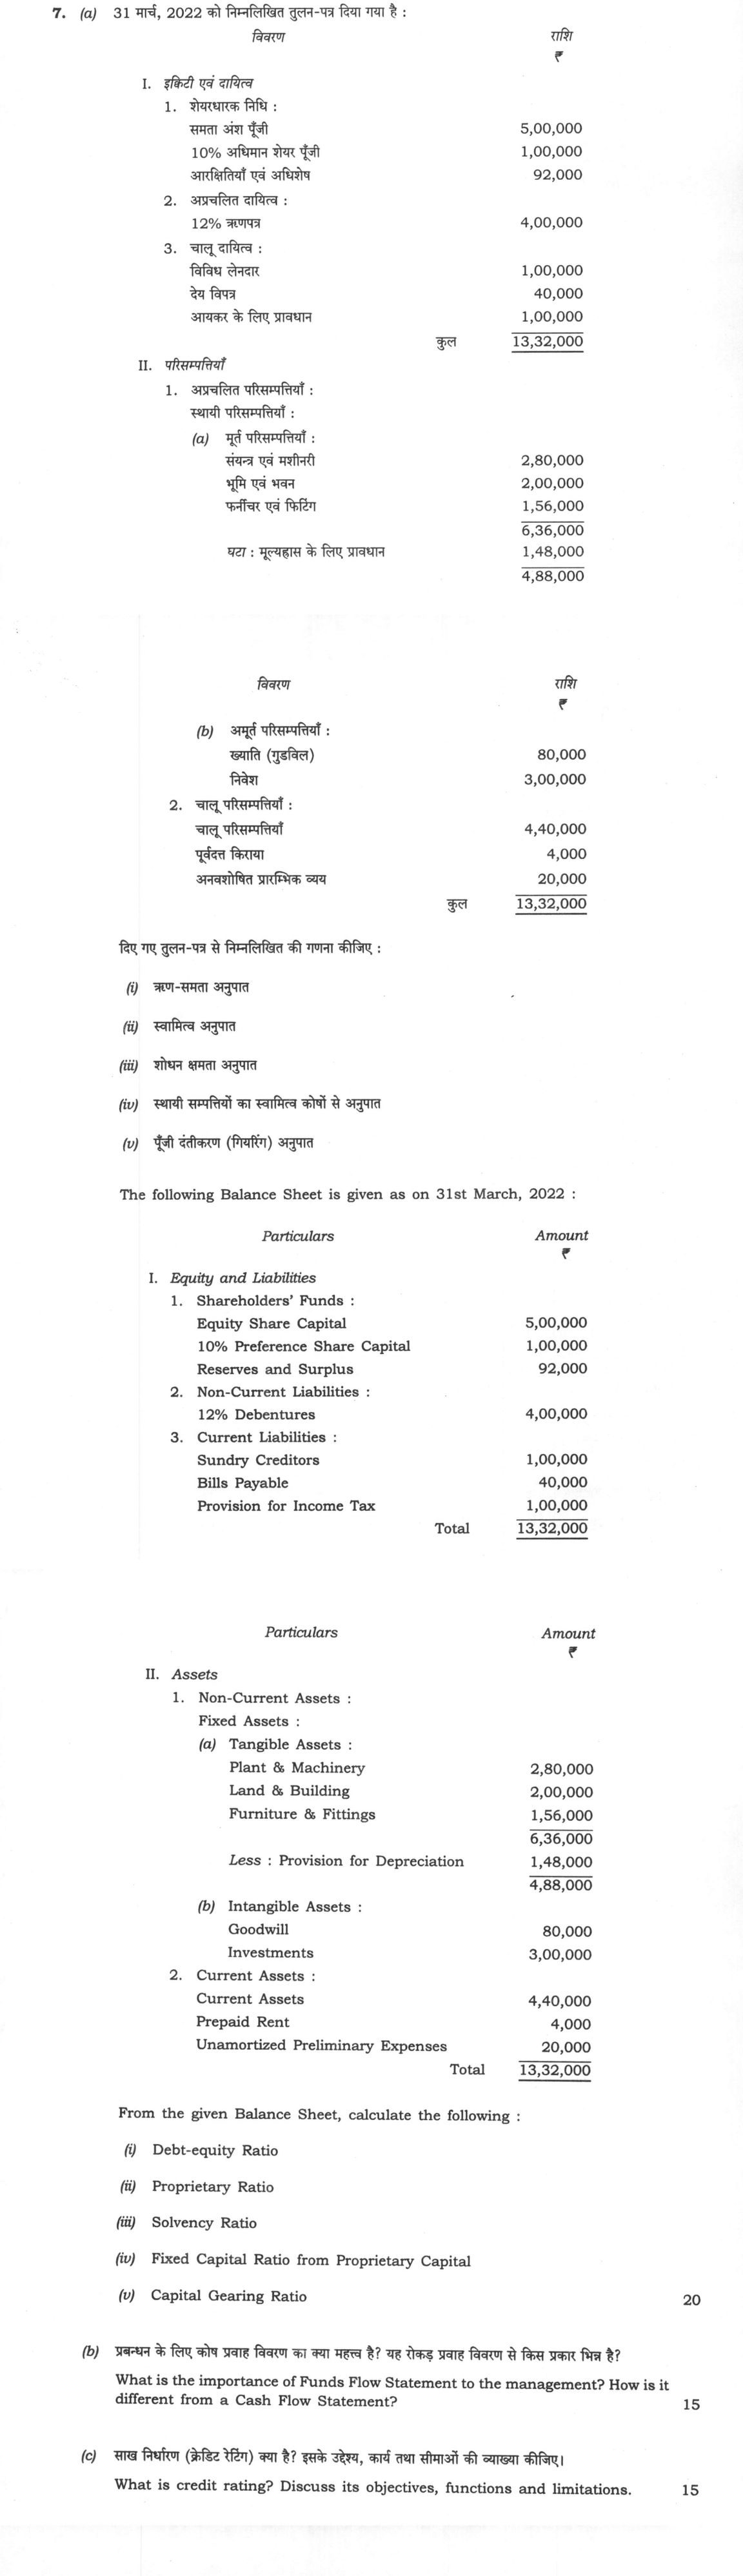
(a) The following Balance Sheet is given as on 31st March, 2022 : Particulars Amount ₹ I. Equity and Liabilities 1…
The following Balance Sheet is given as on 31st March, 2022 :
Particulars Amount ₹ I. Equity and Liabilities 1. Shareholders' Funds : Equity Share Capital 5,00,000 10% Preference Share Capital 1,00,000 Reserves and Surplus 92,000 2. Non-Current Liabilities : 12% Debentures 4,00,000 3. Current Liabilities : Sundry Creditors 1,00,000 Bills Payable 40,000 Provision for Income Tax 1,00,000 Total 13,32,000
II. Assets 1. Non-Current Assets : Fixed Assets :
Tangible Assets : Plant & Machinery 2,80,000 Land & Building 2,00,000 Furniture & Fittings 1,56,000 6,36,000 Less : Provision for Depreciation 1,48,000 4,88,000
Intangible Assets : Goodwill 80,000 Investments 3,00,000 2. Current Assets : Current Assets 4,40,000 Prepaid Rent 4,000 Unamortized Preliminary Expenses 20,000 Total 13,32,000
From the given Balance Sheet, calculate the following : Debt-equity Ratio
Proprietary Ratio
Solvency Ratio
Fixed Capital Ratio from Proprietary Capital
Capital Gearing Ratio 20 marks
What is the importance of Funds Flow Statement to the management? How is it different from a Cash Flow Statement? 15 marks
What is credit rating? Discuss its objectives, functions and limitations. 15 marks
हिंदी में प्रश्न पढ़ें
31 मार्च, 2022 को निम्नलिखित तुलन-पत्र दिया गया है :
विवरण राशि ₹ I. इक्विटी एवं दायित्व 1. शेयरधारक निधि : समता अंश पूंजी 5,00,000 10% अधिमान शेयर पूंजी 1,00,000 आरक्षितियाँ एवं अधिशेष 92,000
2. अप्रचलित दायित्व : 12% ऋणपत्र 4,00,000
3. चालू दायित्व : विविध लेनदार 1,00,000 देय विपत्र 40,000 आयकर के लिए प्रावधान 1,00,000 कुल 13,32,000
II. परिसंपत्तियाँ 1. अप्रचलित परिसंपत्तियाँ : स्थायी परिसंपत्तियाँ :
मूर्त परिसंपत्तियाँ : संयंत्र एवं मशीनरी 2,80,000 भूमि एवं भवन 2,00,000 फर्नीचर एवं फिटिंग 1,56,000 6,36,000 घटा : मूल्यह्रास के लिए प्रावधान 1,48,000 4,88,000
अमूर्त परिसम्पतियाँ : ख्याति (गुडविल) 80,000 निवेश 3,00,000
2. चालू परिसम्पतियाँ : चालू परिसम्पतियाँ 4,40,000 पूर्वदत्त किराया 4,000 अनवशोषित प्रारम्भिक व्यय 20,000 कुल 13,32,000
दिए गए तुलन-पत्र से निम्नलिखित की गणना कीजिए : ऋण-समता अनुपात
स्वामित्व अनुपात
शोधन क्षमता अनुपात
स्थायी सम्पतियों का स्वामित्व कोषों से अनुपात
पूँजी दंतिकरण (गियरिंग) अनुपात 20 अंक
प्रबंधन के लिए कोष प्रवाह विवरण का क्या महत्व है? यह रोकड़ प्रवाह विवरण से किस प्रकार भिन्न है? 15 अंक
साख निर्धारण (क्रेडिट रेटिंग) क्या है? इसके उद्देश्य, कार्य तथा सीमाओं की व्याख्या कीजिए। 15 अंक
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Ratios from the balance sheet
The unamortised preliminary expenses of ₹20,000 are a fictitious asset with no realisable value, so they are deducted both from proprietors' funds and from total assets. The investments of ₹3,00,000 are non-current investments (printed under intangibles) and are not treated as fixed assets.
Basic figures (₹):
- Shareholders' (proprietors') funds = equity 5,00,000 + preference 1,00,000 + reserves 92,000 = 6,92,000. Less fictitious asset 20,000 = 6,72,000.
- Total assets = 13,32,000 − 20,000 = 13,12,000.
- Long-term debt = 12% debentures = 4,00,000.
- Total outside liabilities = debentures 4,00,000 + creditors 1,00,000 + bills payable 40,000 + provision for tax 1,00,000 = 6,40,000.
- Fixed assets = tangible (net) 4,88,000 + goodwill 80,000 = 5,68,000.
(i) Debt-equity ratio = long-term debt ÷ shareholders' funds = 4,00,000 ÷ 6,72,000 = 0.595 : 1 (about 0.60 : 1). For every ₹1 of owners' funds, ₹0.60 is borrowed long term.
(ii) Proprietary ratio = proprietors' funds ÷ total assets = 6,72,000 ÷ 13,12,000 = 0.512 : 1 (51.2%). Owners finance a little over half the assets.
(iii) Solvency ratio = total outside liabilities ÷ total assets = 6,40,000 ÷ 13,12,000 = 0.488 : 1 (48.8%). Equivalently, assets cover outside liabilities 2.05 times (13,12,000 ÷ 6,40,000).
(iv) Fixed assets to proprietors' funds = fixed assets ÷ proprietors' funds = 5,68,000 ÷ 6,72,000 = 0.845 : 1. Owners' funds more than cover the fixed assets, so part of the owners' money also finances working capital, which is a healthy sign.
(v) Capital gearing ratio = fixed-return funds ÷ equity shareholders' funds. Fixed-return funds = preference 1,00,000 + debentures 4,00,000 = 5,00,000. Equity shareholders' funds = equity 5,00,000 + reserves 92,000 − fictitious asset 20,000 = 5,72,000. Ratio = 5,00,000 ÷ 5,72,000 = 0.874 : 1. As it is below 1, the company is low-geared.
If the fictitious asset is not deducted, the ratios are 0.58, 0.52, 0.48, 0.82 and 0.84 respectively.
(b) Funds flow statement
A funds flow statement shows where funds (working capital) came from and how they were used between two balance sheet dates. Its importance to management:
- It explains why working capital changed and why profit does not match the change in liquidity.
- It helps plan long-term finance, since it shows how fixed-asset purchases and repayments were financed.
- It guides dividend, expansion and debt-repayment decisions.
- It allows evaluation of past financial policy and supports forecasting of future fund needs.
Differences from a cash flow statement:
- Basis: funds flow uses working capital (accrual basis); cash flow uses cash and cash equivalents.
- Focus: funds flow shows sources and applications of funds; cash flow shows operating, investing and financing cash flows.
- Purpose: funds flow suits long-term financial planning; cash flow suits short-term liquidity.
- Preparation: funds flow needs a schedule of changes in working capital; cash flow does not.
- Status: a cash flow statement is required for many companies under AS-3 or Ind AS 7; a funds flow statement is not mandatory.
(c) Credit rating
Credit rating is an independent opinion by a rating agency on the ability and willingness of an issuer to meet its debt obligations on time, expressed as a symbol such as AAA (highest safety) to D (default). In India, agencies such as CRISIL, ICRA, CARE and India Ratings work under the SEBI (Credit Rating Agencies) Regulations, 1999.
Objectives: to give investors reliable information on default risk, to help issuers reach a wider market at a fair cost, and to bring discipline and transparency to the debt market.
Functions: grading the risk of instruments, giving an independent and expert opinion, keeping the rating under continuous surveillance, and guiding regulators and lenders, for example in setting risk weights and investment limits.
Limitations: ratings rest largely on past data and on analysts' judgement; the issuer pays for the rating, which may create a conflict of interest; downgrades can be late or sudden, as seen in the IL&FS case; a high rating is not a guarantee against default; and investors may over-rely on it instead of doing their own research.
How this answer will be evaluated
What earns full marks: All parts fully addressed with correct calculations, clear explanations, and comprehensive discussion.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Calculate the five ratios from the balance sheet. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Fictitious asset 20,000 deducted: proprietors' funds 6,72,000 and total assets 13,12,000
- Debt-equity 0.595 : 1 and proprietary ratio 0.512 : 1
- Solvency ratio 0.488 : 1 (assets cover liabilities 2.05 times) and fixed assets to proprietors' funds 0.845 : 1
- Capital gearing 0.874 : 1 with fixed-return funds 5,00,000 and equity funds 5,72,000
Loses marks
- Mixing up preference capital with debt, or ignoring the fictitious asset without saying so.
Earns more
- Marks for the formula and working of each ratio and its interpretation.
Extra mark
- Stating the assumptions on the fictitious asset and on investments.
- (b) Explain the importance of a funds flow statement to management and how it differs from a cash flow statement. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Shows sources and applications of funds and the change in working capital
- Helps financial planning and dividend, expansion and repayment decisions
- Differences: working capital versus cash basis; long term versus short term focus
- Cash flow statement is required under AS-3 or Ind AS 7, funds flow is not
Loses marks
- Describing only what the statement is, without the comparison.
Earns more
- Marks for the importance points and for each difference.
Extra mark
- Noting the schedule of changes in working capital.
- (c) Define credit rating and discuss its objectives, functions and limitations. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Independent opinion on an issuer's ability to repay debt, expressed by a symbol
- Objectives: investor information, cost for issuers, market discipline
- Functions: grading risk, surveillance and independent opinion
- Limitations: past data, issuer-paid conflict of interest, late downgrades, no guarantee
Loses marks
- Giving only limitations or listing agencies without explanation.
Earns more
- Marks for the definition and for each of objectives, functions and limitations.
Extra mark
- Naming agencies and the SEBI regulations, or an example such as IL&FS.
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2023 Paper I
- Q4 (a) A Limited invited applications for 160000 shares of ₹ 10 each at a premium of ₹ 2.50…
- Q5 Answer the following questions in about 150 words each: (a) Explain the 'Financial Indiff…
- Q6 (a) Moon Ltd. wants to replace its labour-intensive manufacturing facility. The company i…
- Q7 (a) The following Balance Sheet is given as on 31st March, 2022 : Particulars Amount ₹ I.…
- Q8 (a) X Limited has its present annual sales amounting to ₹ 60 lakhs at ₹ 24 per unit. Vari…