Paper I — Q7
(a) As a Financial Manager of an engineering company, you are required to compute the weighted average cost of capital of the…
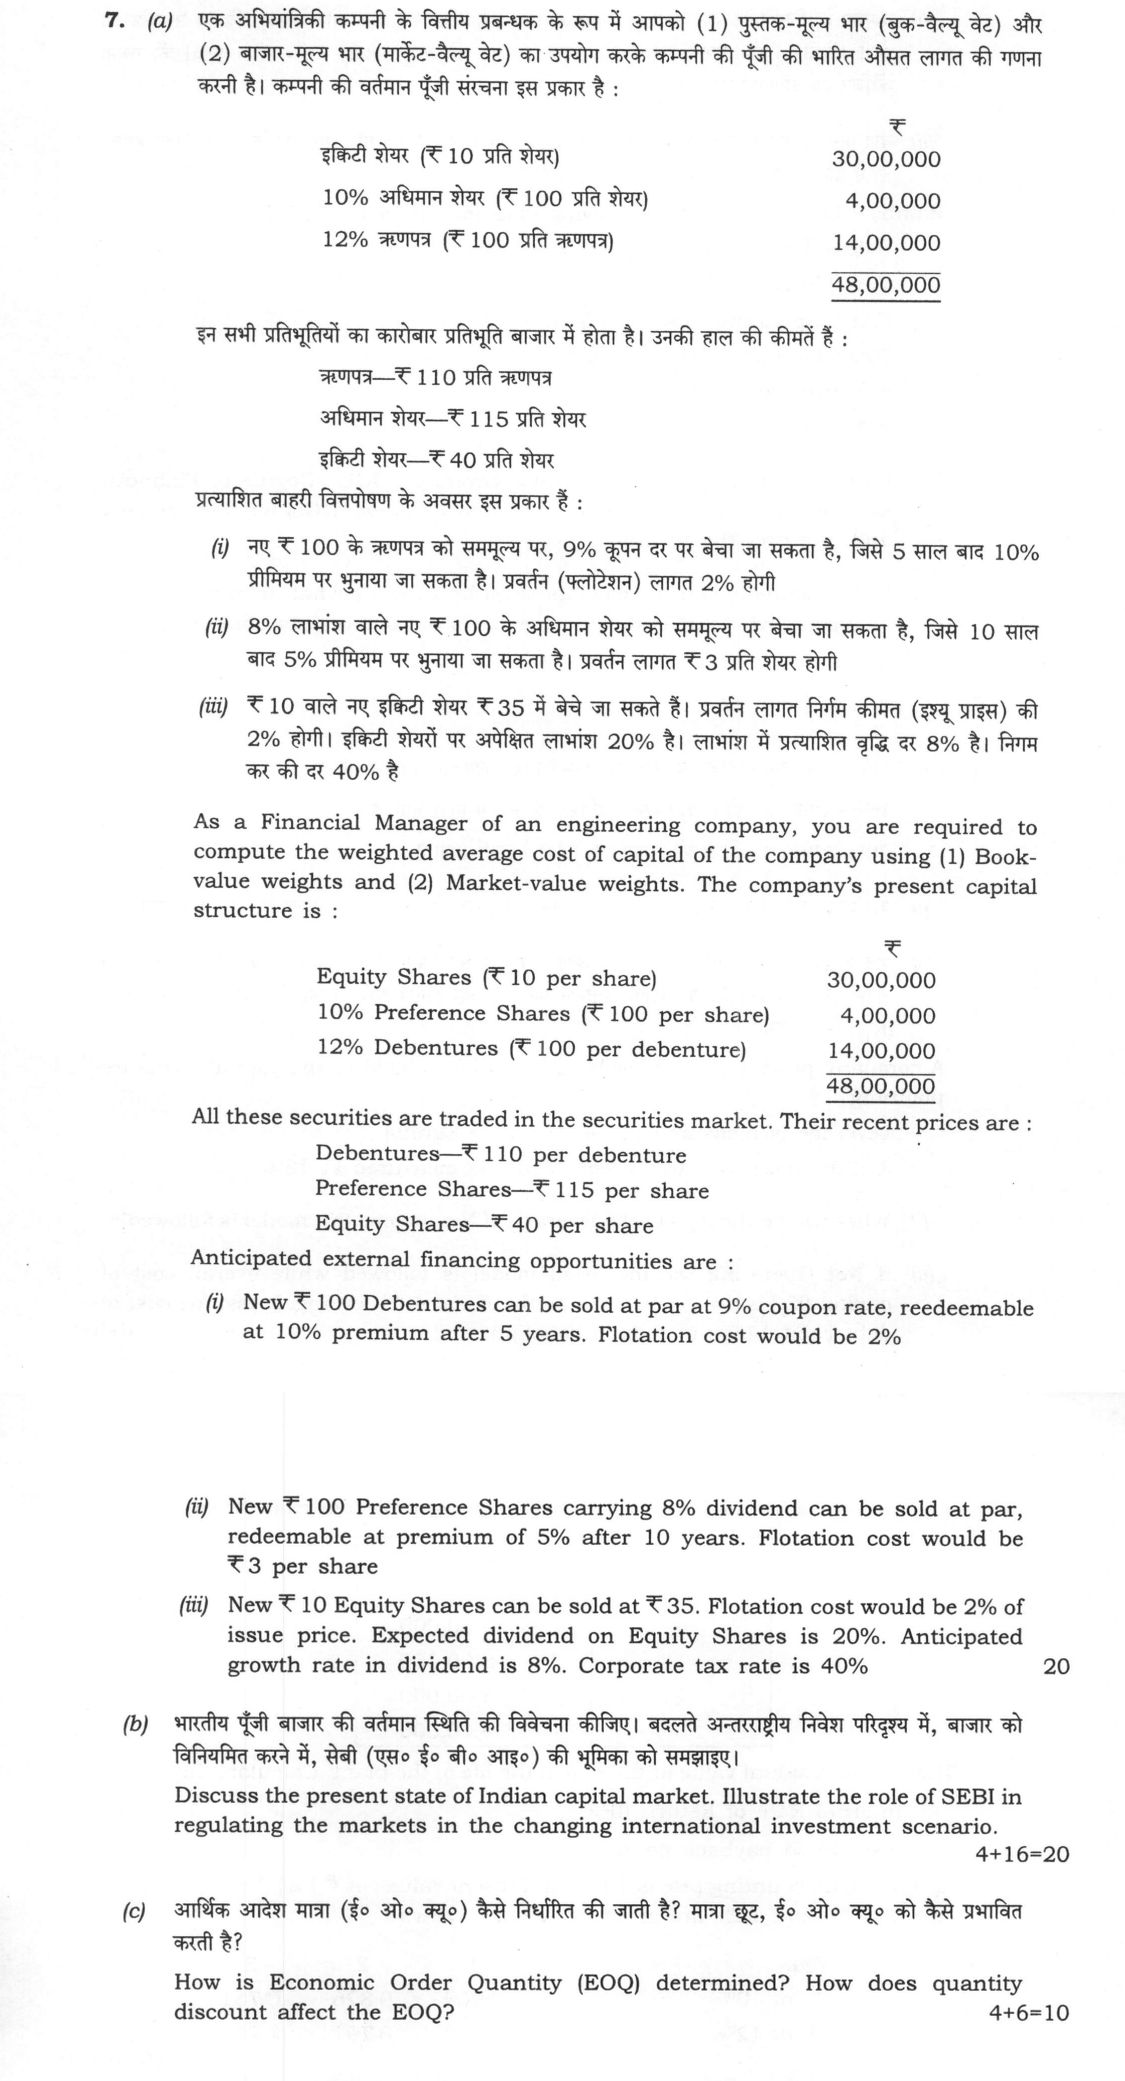
As a Financial Manager of an engineering company, you are required to compute the weighted average cost of capital of the company using (1) Book-value weights and (2) Market-value weights. The company's present capital structure is :
₹ Equity Shares (₹ 10 per share) 30,00,000 10% Preference Shares (₹ 100 per share) 4,00,000 12% Debentures (₹ 100 per debenture) 14,00,000 48,00,000
All these securities are traded in the securities market. Their recent prices are : Debentures—₹ 110 per debenture Preference Shares—₹ 115 per share Equity Shares—₹ 40 per share
Anticipated external financing opportunities are : New ₹ 100 Debentures can be sold at par at 9% coupon rate, redeemable at 10% premium after 5 years. Flotation cost would be 2%
New ₹100 Preference Shares carrying 8% dividend can be sold at par, redeemable at premium of 5% after 10 years. Flotation cost would be ₹3 per share
New ₹10 Equity Shares can be sold at ₹35. Flotation cost would be 2% of issue price. Expected dividend on Equity Shares is 20%. Anticipated growth rate in dividend is 8%. Corporate tax rate is 40% 20 marks
Discuss the present state of Indian capital market. Illustrate the role of SEBI in regulating the markets in the changing international investment scenario. 20 marks
How is Economic Order Quantity (EOQ) determined? How does quantity discount affect the EOQ? 10 marks
हिंदी में प्रश्न पढ़ें
एक अभियांत्रिकी कंपनी के वित्तीय प्रबंधक के रूप में आपको (1) पुस्तक-मूल्य भार (बुक-वैल्यू वेट) और (2) बाजार-मूल्य भार (मार्केट-वैल्यू वेट) का उपयोग करके कंपनी की पूंजी की भारित औसत लागत की गणना करनी है। कंपनी की वर्तमान पूंजी संरचना इस प्रकार है :
₹ इकिटी शेयर (₹ 10 प्रति शेयर) 30,00,000 10% अधिमान शेयर (₹ 100 प्रति शेयर) 4,00,000 12% ऋणपत्र (₹ 100 प्रति ऋणपत्र) 14,00,000 48,00,000
इन सभी प्रतिभूतियों का कारोबार प्रतिभूति बाजार में होता है। उनकी हाल की कीमतें हैं : ऋणपत्र—₹ 110 प्रति ऋणपत्र अधिमान शेयर—₹ 115 प्रति शेयर इकिटी शेयर—₹ 40 प्रति शेयर
प्रत्याशित बाहरी वित्तपोषण के अवसर इस प्रकार हैं : नए ₹ 100 के ऋणपत्र को सम्मूल्य पर, 9% कूपन दर पर बेचा जा सकता है, जिसे 5 साल बाद 10% प्रीमियम पर भुनाया जा सकता है। प्रवर्तन (फ्लोटेशन) लागत 2% होगी
8% लाभांश वाले नए ₹ 100 के अधिमान शेयर को सम्मूल्य पर बेचा जा सकता है, जिसे 10 साल बाद 5% प्रीमियम पर भुनाया जा सकता है। प्रवर्तन लागत ₹ 3 प्रति शेयर होगी
₹ 10 वाले नए इकिटी शेयर ₹ 35 में बेचे जा सकते हैं। प्रवर्तन लागत निर्गम कीमत (इश्यू प्राइस) की 2% होगी। इकिटी शेयरों पर अपेक्षित लाभांश 20% है। लाभांश में प्रत्याशित वृद्धि दर 8% है। निगम कर की दर 40% है (20 अंक)
भारतीय पूँजी बाजार की वर्तमान स्थिति की विवेचना कीजिए। बदलते अंतर्राष्ट्रीय निवेश परिदृश्य में, बाजार को विनियमित करने में, सेबी (एस० ई० बी० आई०) की भूमिका को समझाइए। (20 अंक)
आर्थिक आदेश मात्रा (ई० ओ० क्यू०) कैसे निर्धारित की जाती है? मात्रा छूट, ई० ओ० क्यू० को कैसे प्रभावित करती है? (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a)
Use WACC = Σ wᵢkᵢ. The component costs are computed from the new financing opportunities; weights are taken from book values or market values. Corporate tax rate = 40%.
(i) Cost of debt Using approximate after-tax yield-to-maturity formula: NP = 100 − 2% of 100 = ₹98. After-tax interest = 9(1 − 0.40) = ₹5.40. RV = 100 + 10% premium = ₹110; n = 5 years. Kd = [5.40 + (110 − 98)/5] ÷ [(110 + 98)/2] = (5.40 + 2.40)/104 = 7.80/104 = 0.075 = 7.50%.
(ii) Cost of preference shares NP = 100 − 3 = ₹97; D = ₹8; RV = ₹105; n = 10. Kp = [8 + (105 − 97)/10] ÷ [(105 + 97)/2] = (8 + 0.80)/101 = 8.80/101 = 0.0871287 = 8.7129%.
(iii) Cost of equity NP = 35(1 − 0.02) = ₹34.30. D1 = 20% of ₹10 = ₹2; g = 8%. Ke = D1/NP + g = 2/34.30 + 0.08 = 0.058309 + 0.08 = 0.138309 = 13.8309%.
(1) Book-value weights Book values: E = ₹30,00,000; P = ₹4,00,000; D = ₹14,00,000; total = ₹48,00,000. wE = 30/48 = 0.625; wP = 4/48 = 0.083333; wD = 14/48 = 0.291667. WACC_book = 0.625×0.138309 + 0.083333×0.087129 + 0.291667×0.075 = 0.086443 + 0.007261 + 0.021875 = 0.115579 = 11.56%.
(2) Market-value weights Equity shares = 30,00,000/10 = 3,00,000; MV = 3,00,000×40 = ₹1,20,00,000. Preference shares = 4,00,000/100 = 4,000; MV = 4,000×115 = ₹4,60,000. Debentures = 14,00,000/100 = 14,000; MV = 14,000×110 = ₹15,40,000. Total MV = ₹1,40,00,000. wE = 1,20,00,000/1,40,00,000 = 0.857143. wP = 4,60,000/1,40,00,000 = 0.032857. wD = 15,40,000/1,40,00,000 = 0.110000. WACC_market = 0.857143×0.138309 + 0.032857×0.087129 + 0.110000×0.075 = 0.118551 + 0.002863 + 0.008250 = 0.129664 = 12.97%.
(b)
India’s capital market is among the largest and most vibrant in the emerging world. Retail participation has expanded sharply, with demat accounts crossing 21 crore by December 2025 and mutual fund SIP inflows at record levels. The primary market is active through IPOs, QIPs, rights issues and SME platforms. The secondary market is dominated by NSE and BSE, with high derivatives turnover, growing cash-market depth and T+1 settlement. Market infrastructure includes NSDL/CDSL, clearing corporations and technology-driven trading. The government securities market is deep, but corporate bond liquidity remains comparatively low; steps such as RFQ, Electronic Repo Facility and GIFT City IFSC aim to deepen it. Global integration has increased through FPIs, ADRs/GDRs, Masala bonds and cross-border listings. Challenges include retail speculation in F&O, governance failures, cyber risk, valuation volatility and sensitivity to global monetary policy.
SEBI, under the SEBI Act 1992, is the statutory regulator with quasi-legislative, executive and judicial powers. Its mandate is investor protection, market development and regulation. It regulates exchanges, brokers, merchant bankers, mutual funds, FPIs, credit rating agencies and research analysts. It enforces disclosure, listing, takeover, insider-trading and corporate-governance norms. It conducts surveillance, investigations and enforcement, including penalties and disgorgement. In the changing international investment scenario, SEBI works with IOSCO, signs MoUs with foreign regulators and aligns with global AML/CFT, ESG, cybersecurity and sustainable-finance standards. It manages FPI flows, encourages stable long-term capital and facilitates IFSC/GIFT City and cross-border listing. Thus SEBI balances liberalisation, systemic stability and investor confidence.
(c)
EOQ is determined by minimising total inventory cost. Let D = annual demand, O = ordering cost per order and C = carrying cost per unit per year. Total cost TC = (D/Q)O + (Q/2)C. Differentiating and setting dTC/dQ = 0 gives: Q* = sqrt(2DO/C). If carrying cost is a percentage i of price P, then Q* = sqrt(2DO/iP). Assumptions: constant demand, known ordering and carrying costs, no shortages and no quantity discounts.
Quantity discount affects EOQ because purchase cost D×P becomes relevant. First compute EOQ at the base price. Then identify price-break quantities. For each feasible quantity—EOQ and each break quantity—compute: TC = D×P + (D/Q)O + (Q/2)C. Choose the Q with minimum total cost. A discount may justify ordering above EOQ if the saving in purchase cost exceeds the extra carrying cost; if not, the original EOQ remains optimal.
How this answer will be evaluated
What earns full marks: Complete workings for all calculations, comprehensive discussion with specific examples, clear EOQ explanation with discount impact
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute WACC using book-value and market-value weights. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Kd: NP 98, after-tax interest 5.40, RV 110, n 5 → 7.50%
- Kp: NP 97, D 8, RV 105, n 10 → 8.7129%
- Ke: NP 34.30, D1 ₹2, g 8% → 13.8309%
- WACC book weights 11.56%; market weights (E 1,20,00,000; P 4,60,000; D 15,40,000; total 1,40,00,000) → 12.97%
Loses marks
- Final WACC figures without supporting workings
- Incorrect calculation of market value weights
- Ignoring flotation costs in cost calculation
Earns more
- Correct application of flotation costs
- Accurate calculation of cost of new equity
- Proper handling of tax shield for debt
- Clear tabular presentation of workings
Extra mark
- Explicit statement of assumptions used
- Comparison of the two WACC results
- (b) Discuss Indian capital market state and SEBI's regulatory role. 20 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Present state: retail participation (demat accounts > 21 crore by Dec 2025), active primary market, T+1, NSDL/CDSL, deep G-secs but thin corporate bonds
- SEBI Act 1992 powers; regulation of intermediaries; enforcement/surveillance
- International scenario: IOSCO/MoUs, AML/CFT, ESG, FPI management, IFSC/GIFT City
- Balanced conclusion on regulatory effectiveness
Loses marks
- Generic discussion without specific SEBI references
- Ignoring the international investment scenario aspect
- No structured discussion of market state
Earns more
- Reference to specific SEBI regulations or frameworks
- Examples of international investment trends
- Discussion of market liberalization impacts
- Mention of investor protection mechanisms
Extra mark
- Reference to specific SEBI circulars or guidelines
- Data on foreign portfolio investment trends
- (c) Explain EOQ determination and quantity discount impact. 10 marks
explain— definition/context → points in order → small example → short close
Must cover
- EOQ from minimising TC = (D/Q)O + (Q/2)C → Q* = √(2DO/C) (or √(2DO/iP))
- Assumptions: constant demand, known costs, no shortages/discounts
- Quantity discount makes purchase cost D×P relevant; compare total costs at EOQ and price-break quantities
- Decision rule: order above EOQ only if purchase saving exceeds extra carrying cost
Loses marks
- EOQ formula without explanation of components
- Ignoring the quantity discount aspect
- No clear explanation of how discounts change ordering
Earns more
- Clear explanation of holding and ordering costs
- Example of EOQ calculation
- Discussion of total cost minimization
- Mention of price break points
Extra mark
- Graphical representation of total cost curves
- Reference to specific inventory models
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…
- Q6 (a) Define and explain the concept of merger, takeover and amalgamation. What leads to th…
- Q7 (a) As a Financial Manager of an engineering company, you are required to compute the wei…
- Q8 (a) Explain the structure of Indian financial system. Discuss the emerging role of RBI in…