Paper I — Q5
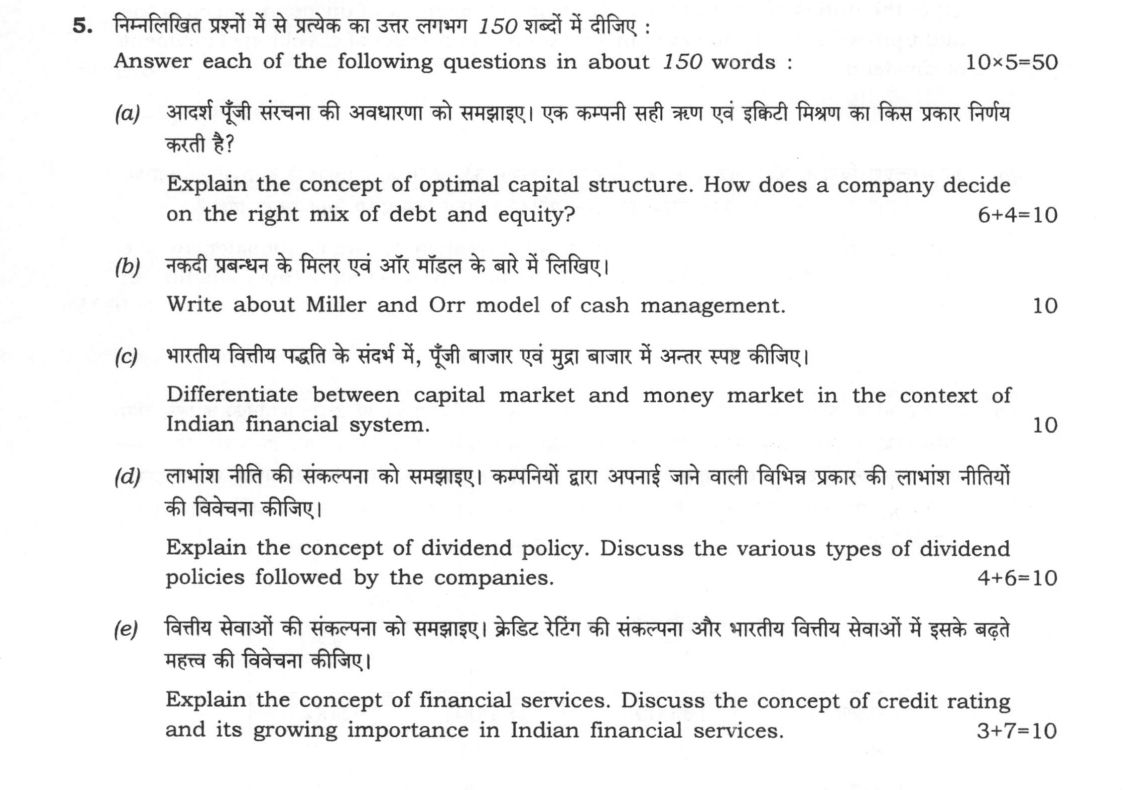
(a) Explain the concept of optimal capital structure. How does a company decide on the right mix of debt and equity? 6+4=10 (b)…
Answer each of the following questions in about 150 words : 10×5=50
Explain the concept of optimal capital structure. How does a company decide on the right mix of debt and equity? 6+4=10
Write about Miller and Orr model of cash management. 10 marks
Differentiate between capital market and money market in the context of Indian financial system. 10 marks
Explain the concept of dividend policy. Discuss the various types of dividend policies followed by the companies. 4+6=10
Explain the concept of financial services. Discuss the concept of credit rating and its growing importance in Indian financial services. 3+7=10
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए : 10×5=50
आदर्श पूँजी संरचना की अवधारणा को समझाइए। एक कम्पनी सही ऋण एवं इक्विटी मिश्रण का किस प्रकार निर्णय करती है? 6+4=10
नकदी प्रबन्धन के मिलर एवं ओर मॉडल के बारे में लिखिए। 10
भारतीय वित्तीय पद्धति के संदर्भ में, पूँजी बाजार एवं मुद्रा बाजार में अन्तर स्पष्ट कीजिए। 10
लाभांश नीति की संकल्पना को समझाइए। कम्पनियों द्वारा अपनाई जाने वाली विभिन्न प्रकार की लाभांश नीतियों की विवेचना कीजिए। 4+6=10
वित्तीय सेवाओं की संकल्पना को समझाइए। क्रेडिट रेटिंग की संकल्पना और भारतीय वित्तीय सेवाओं में इसके बढ़ते महत्व की विवेचना कीजिए। 3+7=10
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a)
Optimal capital structure is the debt-equity mix that minimises weighted average cost of capital (WACC) and maximises firm value. It is an equilibrium where the marginal benefit of debt equals its marginal cost. Debt is cheaper because interest is tax deductible, creating a tax shield; but excessive debt raises bankruptcy risk, agency costs and financial distress. Trade-off theory captures this: a firm adds debt while the tax shield outweighs expected insolvency costs, then stops. In practice, a company uses EBIT-EPS analysis, checks whether trading on equity raises EPS and share price, and weighs business risk, financial flexibility, control dilution and growth opportunities. High business risk or volatile earnings calls for less debt; stable cash flows allow more leverage. Causally, more debt lowers WACC through the tax shield, but if risk rises, cost of equity and distress costs increase, reducing value. Hence the right mix is where incremental debt no longer adds value.
(b)
The Miller-Orr model manages cash for uncertain cash flows. It assumes a two-asset firm holding cash and marketable securities, a fixed cost b per transfer, same for buying and selling, and net cash flows following a random walk. The firm sets a lower limit L, usually 0, and an upper limit H. When cash falls to L, it sells securities to restore the return point z; when cash rises to H, it buys securities to bring cash back to z. The optimal return point is z = ∛(3bσ²/(4i)) + L, where σ² is variance of daily net cash flows and i is the opportunity cost rate. The upper limit is H = 3z − 2L. The average cash balance is (4z − L)/3. The model balances transaction costs against opportunity costs: a wider spread reduces transfers but raises idle cash, while a narrower spread lowers idle cash but increases transactions. It suits unpredictable cash flows, not strongly seasonal or trended flows.
(c)
In India, the money market is the short-term segment, dealing in instruments with maturity of one year or less. It provides liquidity to banks, corporations and government through treasury bills, call money, commercial paper, certificates of deposit, repo and reverse repo. Participants include RBI, scheduled commercial banks, corporates, mutual funds and primary dealers. The capital market is the long-term segment, with shares, debentures, bonds, equity funds and government securities maturing beyond one year. It mobilises long-term savings for companies and government through NSE and BSE, with participants including corporate issuers, foreign portfolio investors (FPIs), retail investors and domestic institutions. Regulators differ: RBI mainly oversees money-market operations and short-term instruments, while SEBI regulates capital markets and protects investors. Causally, money markets manage day-to-day liquidity and interest-rate transmission, whereas capital markets determine long-term cost of capital and asset prices. Money markets are highly liquid and lower-risk; capital markets are deeper, more volatile and expose investors to longer-term business and interest-rate risk.
(d)
Dividend policy decides how much of earnings a company distributes and how much it retains. It links profitability, investment needs and shareholder expectations. A stable dividend policy pays a fixed or slowly rising dividend, giving confidence but possibly straining cash in weak years. A constant payout ratio pays a fixed percentage of earnings, aligning dividends with performance but making payouts volatile. A residual dividend policy first funds positive-NPV projects and pays only surplus earnings, preserving flexibility but producing irregular dividends. A hybrid policy combines stability with payout discipline. Lintner’s partial adjustment model explains that firms adjust dividends gradually toward a target payout, avoiding abrupt changes. The policy is contested: Walter and Gordon argue dividends matter because they affect risk and growth, while Modigliani-Miller argue, in perfect markets, dividends are irrelevant to value. Practically, it signals confidence and shapes demand.
(e)
Financial services channel savings into investment and provide payment, risk management, advisory and credit facilities. They include banking, insurance, securities, asset management and credit information. Credit rating is an opinion on the creditworthiness of a debt instrument or issuer, assessing the likelihood of timely payment of principal and interest. In India, its importance grew after 1991 reforms when market-based borrowing expanded and investors needed independent signals. SEBI (Credit Rating Agencies) Regulations, 1999, brought CRAs under regulation, while registered agencies such as CRISIL, ICRA, CARE, India Ratings and Acuité provide ratings to bonds, debentures, commercial paper and infrastructure projects. The causal mechanism is that ratings reduce information asymmetry: investors can price default risk more accurately, issuers with strong ratings borrow at lower cost, and weaker issuers face higher spreads. Ratings also protect retail investors, support institutional allocation, and deepen the bond market. Yet ratings are opinions, not guarantees.
How this answer will be evaluated
Framework: Miller-Orr Model
What earns full marks: Precise definitions, correct application of models, specific Indian examples, and clear differentiation.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Define optimal capital structure and describe the decision process for debt-equity mix. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Optimal capital structure minimises WACC and maximises value; tax shield benefit vs distress costs (trade-off theory)
- Decision tools: EBIT-EPS analysis, trading on equity, business risk, flexibility, control, growth
- High business risk/volatile earnings → less debt; stable cash flows → more leverage
- Marginal-cost/marginal-benefit logic of adding debt
Loses marks
- Confusing capital structure with capital budgeting
- Ignoring the tax benefit of debt
- Failing to link the mix to firm value
Earns more
- Reference to Modigliani-Miller propositions
- Mention of the pecking order theory
- Discussion of agency costs
- Reference to the target capital structure
Extra mark
- Citing a specific industry benchmark for D/E ratio
- Mentioning the specific role of the CFO in this decision
- (b) Describe the Miller and Orr model for cash management. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Miller-Orr: two assets, fixed transfer cost b, random walk; lower limit L and upper limit H
- Return point z = ∛(3bσ²/4i) + L; upper limit H = 3z − 2L
- Trade-off between transaction and opportunity costs; suits uncertain cash flows
- Not suitable for strongly seasonal/trended flows
Loses marks
- Confusing it with the Baumol model (fixed flows)
- Failing to mention the random nature of cash flows
- Omitting the concept of the return point
Earns more
- Mentioning the formula for the return point
- Comparing it briefly with the Baumol model
- Noting the model's limitation regarding fixed transaction costs
- Mentioning the average cash balance (4z − L)/3
Extra mark
- Providing a numerical example of the limits
- Citing the original 1966 paper by Miller and Orr
- (c) Differentiate between capital market and money market in the Indian context. 10 marks · 150 words
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- Money market: ≤ 1 year; T-bills, call money, CP, CD, repo; RBI and banks; liquidity/monetary transmission
- Capital market: > 1 year; shares, debentures, bonds, G-secs; NSE/BSE; long-term cost of capital
- Regulators: RBI (money market) vs SEBI (capital market)
- Liquidity/risk contrasts and their economic roles
Loses marks
- Confusing the maturity periods
- Listing equity as a money market instrument
- Failing to mention the specific Indian context
Earns more
- Mentioning NSE and BSE for capital market
- Mentioning the role of RBI in the money market
- Discussing the difference in risk and return
- Mentioning the specific Indian instruments like T-bills
Extra mark
- Citing the specific maturity period of T-bills (91, 182, 364 days)
- Mentioning the specific role of the SEBI in the capital market
- (d) Define dividend policy and discuss the various types followed by companies. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Dividend policy = distribution vs retention decision linking earnings, investment needs and expectations
- Types: stable, constant payout, residual, hybrid policies (each explained)
- Lintner partial-adjustment model; Walter/Gordon vs Modigliani-Miller views
- Signalling effect of dividends
Loses marks
- Confusing dividend with bonus shares
- Failing to distinguish between the different policies
- Ignoring the impact on the company's cash flow
Earns more
- Mentioning the 'Bird in the hand' theory
- Discussing the impact of dividend on share price
- Mentioning the legal requirements for dividend declaration
- Discussing the role of the board of directors
Extra mark
- Citing a specific company's dividend history
- Mentioning the specific section of the Companies Act regarding dividends
- (e) Define financial services and discuss credit rating and its importance in India. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Financial services channel savings to investment (banking, insurance, securities, asset management, credit information)
- Credit rating = independent opinion on creditworthiness/timely payment
- Post-1991 growth; SEBI (Credit Rating Agencies) Regulations 1999; CRISIL/ICRA/CARE
- Ratings reduce information asymmetry, lower borrowing cost, protect retail investors; opinions not guarantees
Loses marks
- Confusing credit rating with credit scoring
- Failing to mention the specific Indian context
- Ignoring the role of the rating agencies
Earns more
- Mentioning specific Indian CRAs like CRISIL, ICRA, CARE
- Discussing the role of SEBI in regulating CRAs
- Mentioning the impact of rating on interest rates
- Discussing the role of credit rating in the bond market
Extra mark
- Citing a specific rating scale (e.g., AAA, AA, A)
- Mentioning the specific role of the RBI in the credit rating process
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q2 From the following Trial Balance and other additional information furnished by AGN Ltd.,…
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…
- Q6 (a) Define and explain the concept of merger, takeover and amalgamation. What leads to th…
- Q7 (a) As a Financial Manager of an engineering company, you are required to compute the wei…
- Q8 (a) Explain the structure of Indian financial system. Discuss the emerging role of RBI in…