Paper I — Q3
(a) Explain in brief the deductions that are expressly allowed in computing the income from business under the Income-tax Act…
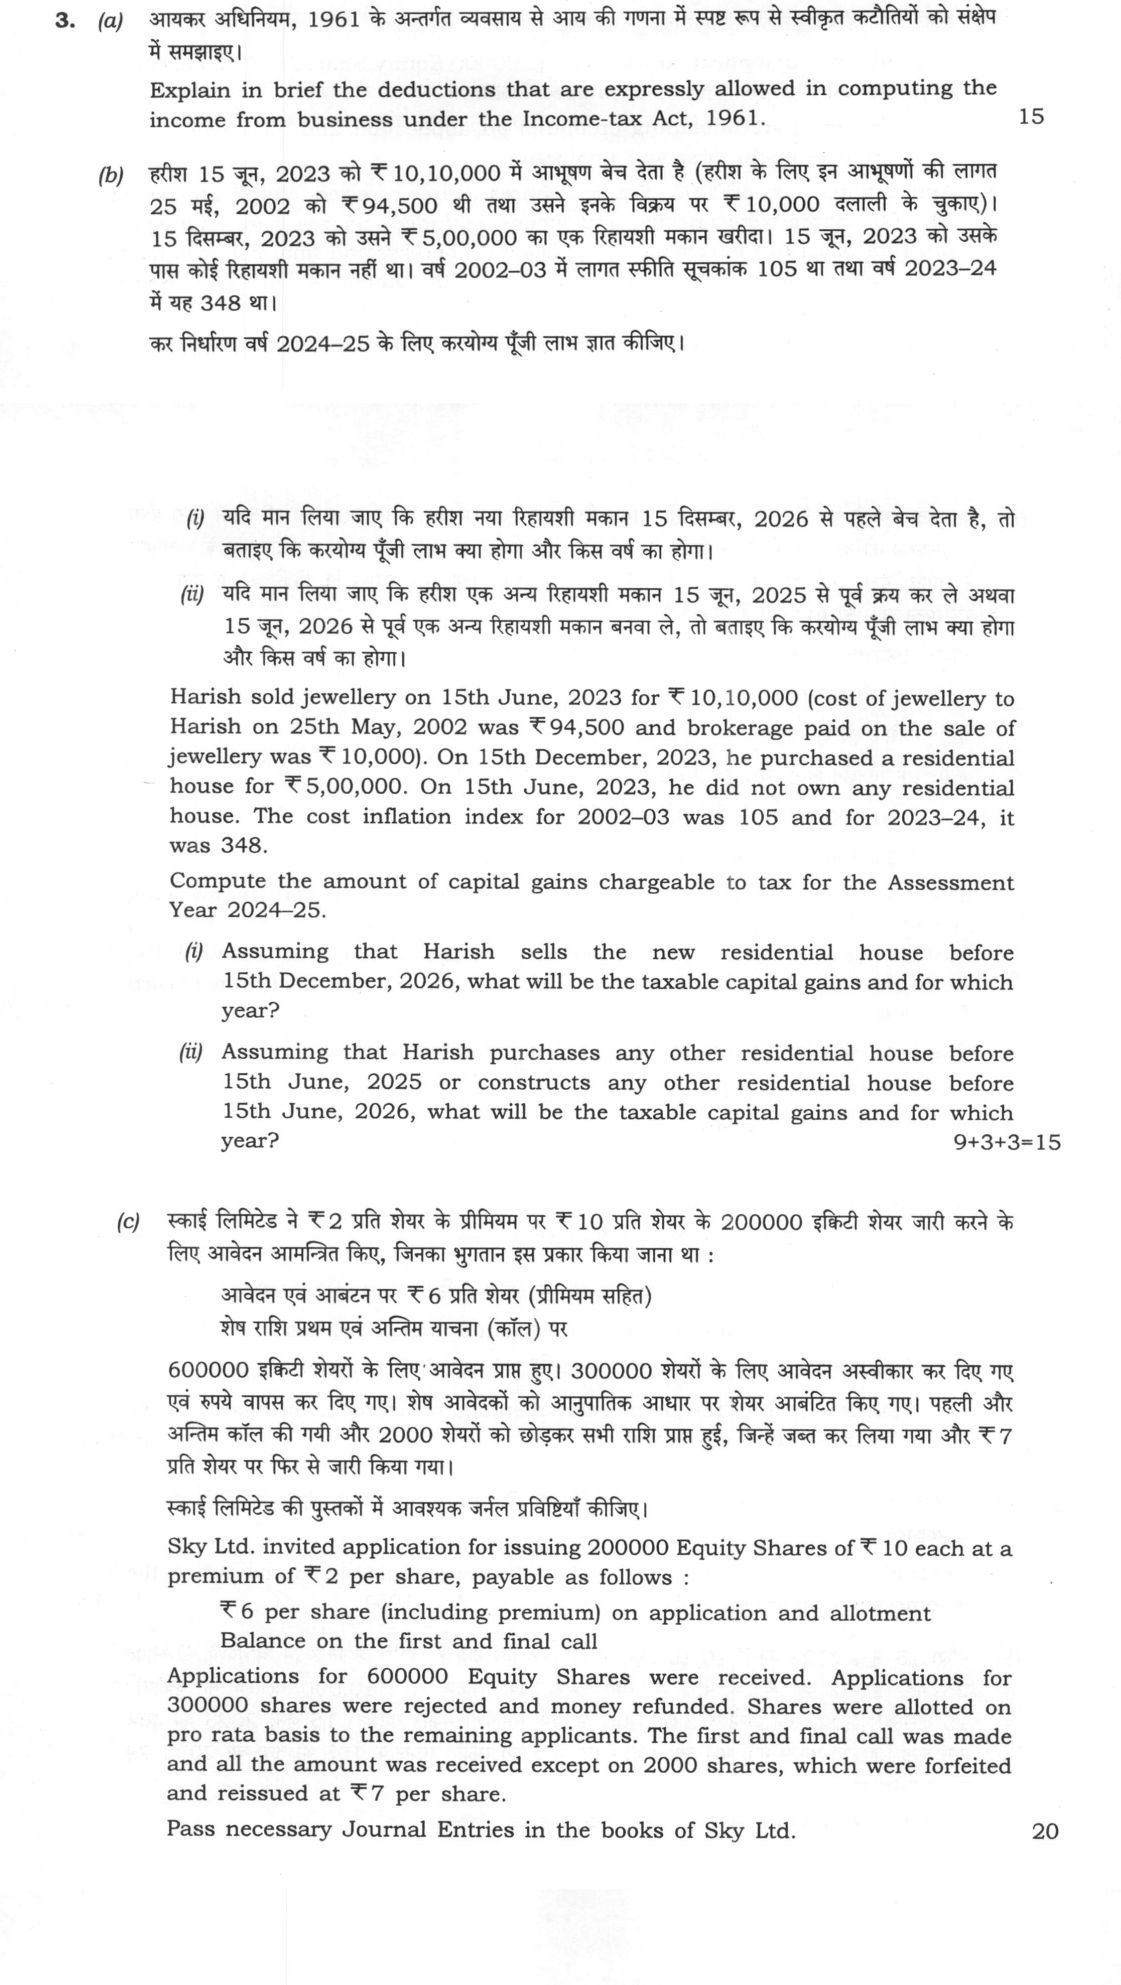
Explain in brief the deductions that are expressly allowed in computing the income from business under the Income-tax Act, 1961. 15 marks
Harish sold jewellery on 15th June, 2023 for ₹ 10,10,000 (cost of jewellery to Harish on 25th May, 2002 was ₹ 94,500 and brokerage paid on the sale of jewellery was ₹ 10,000). On 15th December, 2023, he purchased a residential house for ₹ 5,00,000. On 15th June, 2023, he did not own any residential house. The cost inflation index for 2002-03 was 105 and for 2023-24, it was 348.
Compute the amount of capital gains chargeable to tax for the Assessment Year 2024-25.
Assuming that Harish sells the new residential house before 15th December, 2026, what will be the taxable capital gains and for which year?
Assuming that Harish purchases any other residential house before 15th June, 2025 or constructs any other residential house before 15th June, 2026, what will be the taxable capital gains and for which year? 9+3+3=15
Sky Ltd. invited application for issuing 200000 Equity Shares of ₹ 10 each at a premium of ₹ 2 per share, payable as follows:
₹ 6 per share (including premium) on application and allotment
Balance on the first and final call
Applications for 600000 Equity Shares were received. Applications for 300000 shares were rejected and money refunded. Shares were allotted on pro rata basis to the remaining applicants. The first and final call was made and all the amount was received except on 2000 shares, which were forfeited and reissued at ₹ 7 per share.
Pass necessary Journal Entries in the books of Sky Ltd. 20 marks
हिंदी में प्रश्न पढ़ें
आयकर अधिनियम, 1961 के अंतर्गत व्यवसाय से आय की गणना में स्पष्ट रूप से स्वीकृत कटौतियों को संक्षेप में समझाइए। 15
हरीश 15 जून, 2023 को ₹ 10,10,000 में आभूषण बेच देता है (हरीश के लिए इन आभूषणों की लागत 25 मई, 2002 को ₹ 94,500 थी तथा उसने इनके विक्रय पर ₹ 10,000 दलाली के चुकाए)। 15 दिसंबर, 2023 को उसने ₹ 5,00,000 का एक रिहायशी मकान खरीदा। 15 जून, 2023 को उसके पास कोई रिहायशी मकान नहीं था। वर्ष 2002-03 में लागत स्फीति सूचकांक 105 था तथा वर्ष 2023-24 में यह 348 था।
कर निर्धारण वर्ष 2024-25 के लिए करयोग्य पूंजी लाभ ज्ञात कीजिए।
यदि मान लिया जाए कि हरीश नया रिहायशी मकान 15 दिसंबर, 2026 से पहले बेच देता है, तो बताइए कि करयोग्य पूँजी लाभ क्या होगा और किस वर्ष का होगा।
यदि मान लिया जाए कि हरीश एक अन्य रिहायशी मकान 15 जून, 2025 से पूर्व क्रय कर ले अथवा 15 जून, 2026 से पूर्व एक अन्य रिहायशी मकान बनवा ले, तो बताइए कि करयोग्य पूँजी लाभ क्या होगा और किस वर्ष का होगा। 9+3+3=15
स्काई लिमिटेड ने ₹ 2 प्रति शेयर के प्रीमियम पर ₹ 10 प्रति शेयर के 200000 इक्विटी शेयर जारी करने के लिए आवेदन आमंत्रित किए, जिनका भुगतान इस प्रकार किया जाना था:
आवेदन एवं आवंटन पर ₹ 6 प्रति शेयर (प्रीमियम सहित)
शेष राशि प्रथम एवं अंतिम याचना (कॉल) पर
600000 इक्विटी शेयरों के लिए आवेदन प्राप्त हुए। 300000 शेयरों के लिए आवेदन अस्वीकार कर दिए गए एवं रुपये वापस कर दिए गए। शेष आवेदकों को अनुपातिक आधार पर शेयर आवंटित किए गए। पहली और अंतिम कॉल की गयी और 2000 शेयरों को छोड़कर सभी राशि प्राप्त हुई, जिन्हें जब्त कर लिया गया और ₹ 7 प्रति शेयर पर फिर से जारी किया गया।
स्काई लिमिटेड की पुस्तकों में आवश्यक जर्नल प्रविष्टियाँ कीजिए। 20
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a)
The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026; the provisions below are those of the 1961 Act, which the question asks about and which governs the years in this question. The Act computes business income by deducting only the outgoings expressly allowed under Sections 30–37 from gross business receipts. Section 30 allows rent, rates, taxes and repairs of business premises; Section 31 allows repairs and insurance of plant, machinery and furniture; Section 32 allows depreciation on assets used for business (with Section 32(1)(iia) additional depreciation on new plant and Section 32AD investment allowance of 15% for new plant in notified backward areas); Sections 33AB/33ABA allow deposits with NABARD/Site Restoration Account; Section 35 allows scientific-research expenditure and Section 35D amortises pre-commencement expenses over five years; Section 36(1) allows insurance on stocks, bonus and commission, employer's contributions to PF/gratuity, interest on borrowed capital, bad debts and certain provisions; and Section 37 allows any other business expenditure laid out wholly and exclusively for the business (not capital or personal). The mechanism is selective: only these statutory items are deductible, and Sections 40, 40A and 43B restrict these deductions: section 40(a) disallows payments on which TDS was not deducted or paid, section 40A(3) disallows cash payments above ₹10,000 a day, and section 43B allows statutory dues, bonus and certain other items only on actual payment.
(b)
Jewellery is a capital asset and, being held from 25.5.2002 to 15.6.2023, the gain is long-term. Indexed cost of acquisition = ₹94,500 × 348/105 = ₹3,13,200. Net sale proceeds = ₹10,10,000 − ₹10,000 brokerage = ₹10,00,000. Long-term capital gain = ₹10,00,000 − ₹3,13,200 = ₹6,86,800. Under section 54F, Harish did not own a residential house on 15.6.2023 and purchased one for ₹5,00,000 within the period, so exemption = ₹5,00,000/₹10,00,000 × ₹6,86,800 = ₹3,43,400. Chargeable capital gain for AY 2024-25 = ₹6,86,800 − ₹3,43,400 = ₹3,43,400.
(i) Under section 54F(3), if the new house is sold within three years of its purchase, i.e. before 15.12.2026, the exempted ₹3,43,400 is deemed to be long-term capital gain of the previous year in which the new house is sold, and is taxed in the corresponding assessment year (for example, a sale in PY 2025-26 is taxed in AY 2026-27, and a sale between 1.4.2026 and 15.12.2026 in AY 2027-28). The gain on the new house itself is computed normally; its cost is not reduced (that treatment applies under section 54, not 54F).
(ii) Under section 54F(2), if Harish purchases any other residential house within two years of the original transfer (before 15.6.2025) or constructs one within three years (before 15.6.2026), the exempted ₹3,43,400 is deemed to be long-term capital gain of the previous year in which that other house is purchased or constructed, and is taxed in the corresponding assessment year (for example, a purchase between 1.4.2025 and 15.6.2025 is taxed in AY 2026-27, and a construction completed between 1.4.2026 and 15.6.2026 in AY 2027-28).
(c)
Because applications exceeded the issue, the remaining 3,00,000 applied shares are allotted 2,00,000 shares in a 2:3 ratio, creating excess application money of ₹3 per allotted share. Dr Bank A/c 36,00,000; Cr Share Application A/c 36,00,000 (application money on 6,00,000 shares). Dr Share Application A/c 18,00,000; Cr Bank A/c 18,00,000 (refund on 3,00,000 shares). Dr Share Application A/c 18,00,000; Cr Share Capital A/c 8,00,000; Cr Securities Premium A/c 4,00,000; Cr Calls-in-Advance A/c 6,00,000 (allotment; excess adjusted to call). Dr First and Final Call A/c 12,00,000; Cr Share Capital A/c 12,00,000 (call made). Dr Bank A/c 5,94,000; Dr Calls-in-Advance A/c 6,00,000; Dr Calls-in-Arrears A/c 6,000; Cr First and Final Call A/c 12,00,000 (net call ₹6,00,000 received except default on 2,000 shares). Dr Share Capital A/c 20,000; Cr Share Forfeiture A/c 14,000; Cr Calls-in-Arrears A/c 6,000 (forfeiture; premium already received, so not reversed). Dr Bank A/c 14,000; Dr Share Forfeiture A/c 6,000; Cr Share Capital A/c 20,000 (reissue at ₹7). Dr Share Forfeiture A/c 8,000; Cr Capital Reserve A/c 8,000. Balance-sheet effect: share capital ₹20,00,000, securities premium ₹4,00,000 and capital reserve ₹8,000.
How this answer will be evaluated
Framework: CBSE/UPSC Commerce Accountancy Paper 1
What earns full marks: All parts answered with correct workings, statutory citations, and precise journal entries.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Brief explanation of deductions allowed in computing business income under Income-tax Act, 1961. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Statutory scheme of §§30–37 — only expressly allowed deductions
- §30 rent/rates/repairs; §31 plant repairs/insurance; §32 depreciation; §35 research and §35D amortisation
- §36(1): stock insurance, bonus, PF/gratuity, interest on borrowings, bad debts; §37 residuary business expenditure
- Selectivity principle plus §40/40A/43B disallowances (TDS defaults, cash payments)
Loses marks
- Listing deductions without brief explanation
- Confusing personal deductions with business deductions
Earns more
- Mention Section 36 (interest on borrowed capital)
- Mention Section 35D (preliminary expenses)
- Mention Section 43B (payment of statutory dues)
Extra mark
- Cite specific sub-sections (e.g., 37(1))
- (b) Compute capital gains chargeable for AY 2024-25 with working notes. 9 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- ICA = 94,500 × 348/105 = ₹3,13,200; NSP = ₹10,00,000
- LTCG = ₹6,86,800; §54F exemption = (5,00,000/10,00,000) × 6,86,800 = ₹3,43,400
- Chargeable for AY 2024-25 = ₹3,43,400
Loses marks
- Final figure without working notes
- Incorrect application of CII to sale price
Earns more
- Correct calculation of CII ratio (348/105)
- Correct deduction of brokerage from sale price
Extra mark
- Explicit mention of Section 54F(1) conditions
- (b)(i) Determine taxable capital gains and year if new house is sold before 15 Dec 2026. 3 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Sale of the new house before 15.12.2026 (within 3 years) → the exempted ₹3,43,400 is withdrawn and taxed in the previous year of sale (AY follows the actual year of sale)
Loses marks
- Failing to identify the correct year of taxation
Earns more
- Mention the amount of unexempted gain
Extra mark
- Cite Section 54F(3) specifically
- (b)(ii) Determine taxable capital gains and year if another house is purchased/constructed within limits. 3 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Purchase of another house before 15.6.2025 or construction before 15.6.2026 → the exempted amount becomes taxable in the year of that event
Loses marks
- Confusing purchase and construction timelines
Earns more
- Mention the specific time limits (purchase within 2 years / construction within 3 years)
Extra mark
- Cite Section 54F(2) specifically
- (c) Pass necessary journal entries in the books of Sky Ltd. 20 marks
derive— given → assumptions → stepwise derivation → result → check
Must cover
- Application money 36,00,000; refund 18,00,000; pro-rata allotment of 2,00,000 shares (capital 8,00,000 + premium 4,00,000 + calls-in-advance 6,00,000)
- Call 12,00,000; receipts 5,94,000 + C-I-A 6,00,000 + arrears 6,000
- Forfeiture entry: capital 20,000 = forfeiture 14,000 + arrears 6,000 (premium not reversed)
- Reissue at ₹7 (bank 14,000 + forfeiture 6,000); transfer ₹8,000 to capital reserve; balance-sheet figures
Loses marks
- Missing journal entries for any stage
- Incorrect calculation of pro-rata shares
- Incorrect calculation of forfeiture amount
Earns more
- Entry for reissue of forfeited shares
- Correct calculation of pro-rata allotment
- Correct calculation of forfeiture amount
Extra mark
- Explicit calculation of premium on reissue
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q1 Answer each of the following questions in about 150 words: (a) Discuss the key points tha…
- Q2 From the following Trial Balance and other additional information furnished by AGN Ltd.,…
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…
- Q6 (a) Define and explain the concept of merger, takeover and amalgamation. What leads to th…