Paper I — Q6
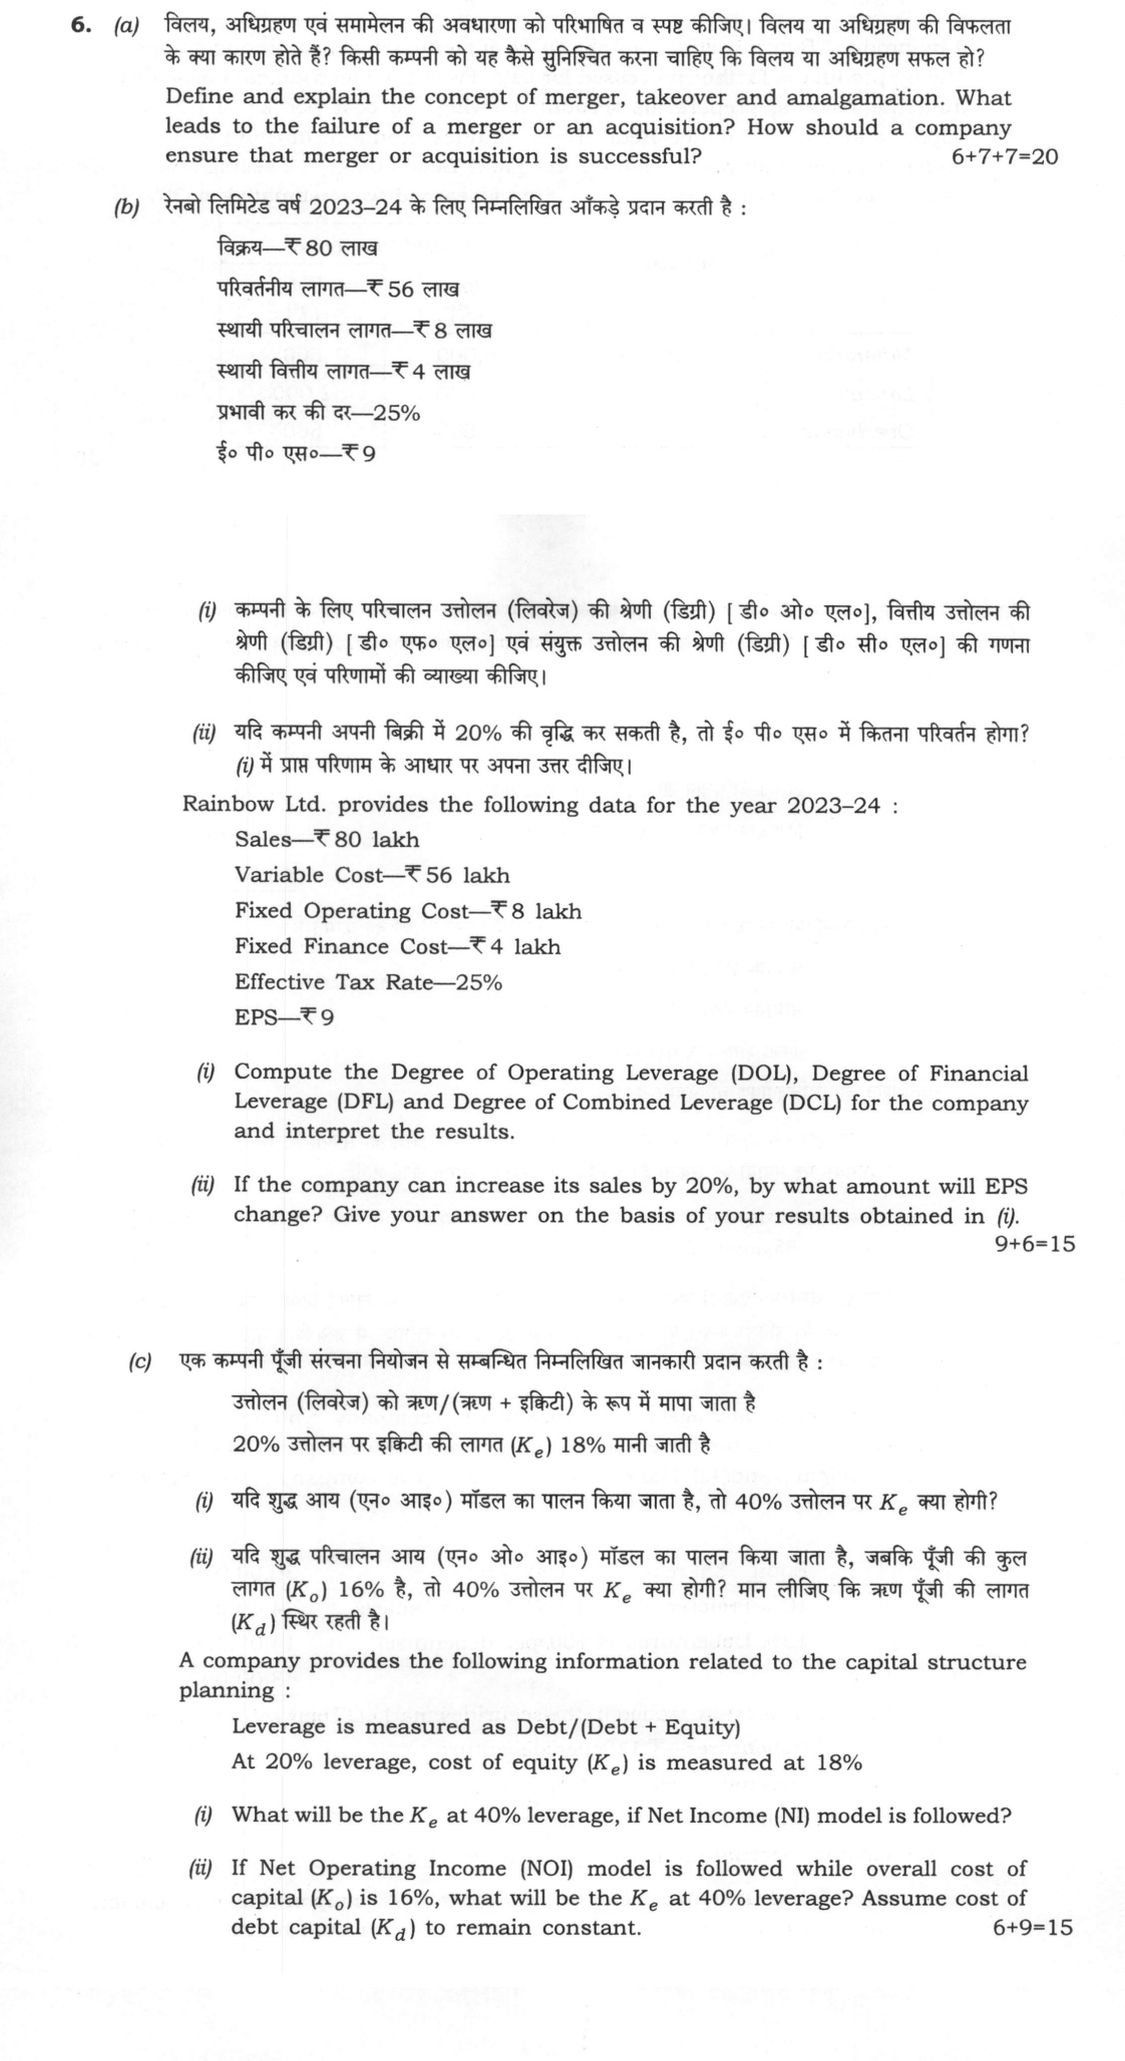
(a) Define and explain the concept of merger, takeover and amalgamation. What leads to the failure of a merger or an acquisition?…
Define and explain the concept of merger, takeover and amalgamation. What leads to the failure of a merger or an acquisition? How should a company ensure that merger or acquisition is successful? 6+7+7=20
Rainbow Ltd. provides the following data for the year 2023-24 :
Sales—₹ 80 lakh
Variable Cost—₹ 56 lakh
Fixed Operating Cost—₹ 8 lakh
Fixed Finance Cost—₹ 4 lakh
Effective Tax Rate—25%
EPS—₹ 9
Compute the Degree of Operating Leverage (DOL), Degree of Financial Leverage (DFL) and Degree of Combined Leverage (DCL) for the company and interpret the results.
If the company can increase its sales by 20%, by what amount will EPS change? Give your answer on the basis of your results obtained in (i).
9+6=15
A company provides the following information related to the capital structure planning :
Leverage is measured as Debt/(Debt + Equity)
At 20% leverage, cost of equity (Kₑ) is measured at 18%
What will be the Kₑ at 40% leverage, if Net Income (NI) model is followed?
If Net Operating Income (NOI) model is followed while overall cost of capital (K₀) is 16%, what will be the Kₑ at 40% leverage? Assume cost of debt capital (Kₐ) to remain constant.
6+9=15
हिंदी में प्रश्न पढ़ें
विलय, अधिग्रहण एवं समामेलन की अवधारणा को परिभाषित व स्पष्ट कीजिए। विलय या अधिग्रहण की विफलता के क्या कारण होते हैं? किसी कम्पनी को यह कैसे सुनिश्चित करना चाहिए कि विलय या अधिग्रहण सफल हो? 6+7+7=20
रेनबो लिमिटेड वर्ष 2023-24 के लिए निम्नलिखित आँकड़े प्रदान करती है :
विक्रय—₹ 80 लाख
परिवर्तनीय लागत—₹ 56 लाख
स्थायी परिचालन लागत—₹ 8 लाख
स्थायी वित्तीय लागत—₹ 4 लाख
प्रभावी कर की दर—25%
ई० पी० एस०—₹ 9
कम्पनी के लिए परिचालन उत्तोलन (लिवरेज) की श्रेणी (डिग्री) [डी० ओ० एल०], वित्तीय उत्तोलन की श्रेणी (डिग्री) [डी० एफ० एल०] एवं संयुक्त उत्तोलन की श्रेणी (डिग्री) [डी० सी० एल०] की गणना कीजिए एवं परिणामों की व्याख्या कीजिए।
यदि कम्पनी अपनी बिक्री में 20% की वृद्धि कर सकती है, तो ई० पी० एस० में कितना परिवर्तन होगा? (i) में प्राप्त परिणाम के आधार पर अपना उत्तर दीजिए।
9+6=15
एक कम्पनी पूँजी संरचना नियोजन से सम्बन्धित निम्नलिखित जानकारी प्रदान करती है :
उत्तोलन (लिवरेज) को ऋण/(ऋण + इक्विटी) के रूप में मापा जाता है
20% उत्तोलन पर इक्विटी की लागत (Kₑ) 18% मानी जाती है
यदि शुद्ध आय (एन० आई०) मॉडल का पालन किया जाता है, तो 40% उत्तोलन पर Kₑ क्या होगी?
यदि शुद्ध परिचालन आय (एन० ओ० आई०) मॉडल का पालन किया जाता है, जबकि पूँजी की कुल लागत (K₀) 16% है, तो 40% उत्तोलन पर Kₑ क्या होगी? मान लीजिए कि ऋण पूँजी की लागत (Kₐ) स्थिर रहती है।
6+9=15
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Merger, Takeover, and Amalgamation
Definitions and Concepts A Merger is a legal combination of two or more companies where at least one pre-existing entity survives. It typically takes the form of an "absorption," where the assets and liabilities of the disappearing entity vest in the surviving company. A Takeover refers to the acquisition of control over a target company, usually through the purchase of a majority of its shares or assets; the target may continue to exist as a subsidiary. Amalgamation, as defined in section 2(1B) of the Income-tax Act and AS 14, covers both forms: absorption of one company into an existing company, and consolidation of two or more companies into a new company formed for the purpose. In the narrower sense used to contrast it with merger, the transferor companies are dissolved without winding up under a scheme sanctioned under sections 230–232 of the Companies Act, 2013, and their assets and liabilities vest in the new company. Takeovers of listed companies are governed by the SEBI (Substantial Acquisition of Shares and Takeovers) Regulations, 2011.
Causes of Failure Mergers and acquisitions often fail due to:
- Overpayment: Hubris leads to paying a premium far exceeding the target's intrinsic value.
- Culture Clash: Incompatible organizational cultures and management styles cause internal friction.
- Inadequate Due Diligence: Failing to uncover hidden liabilities or legal issues.
- Lack of Integration: Absence of a pre-signed integration plan leads to operational chaos.
- Talent Flight: Key employees leave due to uncertainty or restructuring.
Ensuring Success To ensure success, a company must:
- Conduct comprehensive financial, legal, and HR due diligence.
- Perform conservative valuations to avoid overpaying.
- Develop a detailed integration roadmap before the deal closes.
- Retain key personnel through retention incentives.
- Establish a board-level Project Management Office (PMO) to track synergy realization.
(b)(i) Leverage Calculations
Given Data: Sales = ₹80 lakh; Variable Cost = ₹56 lakh; Fixed Operating Cost = ₹8 lakh; Fixed Finance Cost = ₹4 lakh.
Working Notes:
- Contribution = Sales - Variable Cost = 80 - 56 = ₹24 lakh
- EBIT = Contribution - Fixed Operating Cost = 24 - 8 = ₹16 lakh
- EBT = EBIT - Fixed Finance Cost = 16 - 4 = ₹12 lakh
Calculations:
- Degree of Operating Leverage (DOL) = Contribution / EBIT = 24 / 16 = 1.5
- Degree of Financial Leverage (DFL) = EBIT / EBT = 16 / 12 = 1.33
- Degree of Combined Leverage (DCL) = DOL × DFL = 1.5 × 1.33 = 2.0
Interpretation: The DOL of 1.5 indicates that a 1% change in sales results in a 1.5% change in EBIT. The DFL of 1.33 shows that a 1% change in EBIT leads to a 1.33% change in EBT. The DCL of 2.0 signifies that a 1% change in sales will cause a 2% change in EPS.
(b)(ii) Change in EPS
Given: Sales increase by 20%.
Calculation: Using the DCL calculated in part (i):
- Percentage Change in EPS = DCL × Percentage Change in Sales
- Percentage Change in EPS = 2.0 × 20% = 40%
Absolute Change:
- New EPS = Current EPS × (1 + 40%) = 9 × 1.4 = ₹12.60
- Change in EPS = 12.60 - 9 = ₹3.60
Result: A 20% increase in sales will result in a 40% increase in EPS, raising it from ₹9 to ₹12.60.
(c)(i) NI Model Calculation
Given: Leverage (L) = Debt / (Debt + Equity). At 20% leverage, Cost of Equity (Ke) = 18%.
Analysis: Under the Net Income (NI) model, the cost of equity (Ke) and cost of debt (Kd) are considered constant regardless of the level of leverage. The model assumes that as a company adds more debt, the risk to equity holders does not increase because the debt is serviced from earnings.
Calculation: Since Ke remains constant under the NI model:
- Ke at 40% leverage = Ke at 20% leverage = 18%
Result: The cost of equity at 40% leverage remains 18%.
(c)(ii) NOI Model Calculation
Given: Overall Cost of Capital (Ko) = 16%. Leverage at 20%: Ke = 18%. Leverage at 40%: Find Ke.
Step 1: Calculate Kd Using the NOI model formula: Ko = Kd × (D/V) + Ke × (E/V) At 20% leverage (D/V = 0.2, E/V = 0.8): 16 = Kd(0.2) + 18(0.8) 16 = 0.2Kd + 14.4 1.6 = 0.2Kd Kd = 8%
Step 2: Calculate Ke at 40% Leverage At 40% leverage (D/V = 0.4, E/V = 0.6): 16 = 8(0.4) + Ke(0.6) 16 = 3.2 + 0.6Ke 12.8 = 0.6Ke Ke = 21.33%
Result: Under the NOI model, the cost of equity at 40% leverage is 21.33%.
How this answer will be evaluated
What earns full marks: All parts answered with correct formulas, clear workings, and precise interpretations.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Define merger, takeover, and amalgamation; analyze failure causes; suggest success measures. 20 marks
explain— definition/context → points in order → small example → short close
Must cover
- Definitions: merger (surviving entity), takeover (acquisition of control; SEBI SAST 2011), amalgamation (absorption or new entity; s. 2(1B), AS 14; ss. 230–232)
- Failure causes: overpayment/hubris, culture clash, inadequate due diligence, no integration plan, talent flight
- Success measures: comprehensive due diligence, conservative valuation, integration roadmap, retention incentives, PMO
- Balanced treatment of all three sub-parts (6+7+7)
Loses marks
- Confusing merger with amalgamation
- Vague generalities without specific causes
Earns more
- Distinguish between merger and amalgamation
- Cite specific failure examples
- Mention due diligence in success
Extra mark
- Reference SEBI Takeover Regulations
- (b)(i) Compute DOL, DFL, and DCL for Rainbow Ltd. and interpret the results. 9 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Contribution 24; EBIT 16; EBT 12 (₹ lakh)
- DOL = 24/16 = 1.5; DFL = 16/12 = 1.33; DCL = 1.5 × 1.33 = 2.0
- Interpretation: 1% sales change → 1.5% EBIT → 2% EPS
Loses marks
- Using wrong formula for DFL
- Omitting interpretation of results
Earns more
- Show working notes for EBIT and EBT
- Correctly identify fixed finance cost
Extra mark
- Mention sensitivity of EPS to sales
- (b)(ii) Determine the change in EPS if sales increase by 20%. 6 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- %ΔEPS = DCL × 20% = 40%
- New EPS = 9 × 1.4 = ₹12.60; change = ₹3.60
- Answer based on part (i) results as required
Loses marks
- Ignoring the 20% sales increase
- Not linking to DCL from part (i)
Earns more
- Show step-by-step calculation
- State final EPS value
Extra mark
- Verify with direct calculation
- (c)(i) Calculate Ke at 40% leverage using the Net Income (NI) model. 6 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- NI model: Ke and Kd independent of leverage
- Ke at 40% leverage = 18% (same as at 20%)
Loses marks
- Using wrong leverage ratio
- Confusing NI with NOI model
Earns more
- Show formula substitution
- State assumption of constant Kd
Extra mark
- Mention limitations of NI model
- (c)(ii) Calculate Ke at 40% leverage using the NOI model with Ko=16%. 9 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Ko = Kd(D/V) + Ke(E/V); 16 = 0.2Kd + 18(0.8) → Kd = 8%
- At 40% leverage: 16 = 8(0.4) + 0.6Ke → Ke = 12.8/0.6 = 21.33%
- Assumption of constant Kd stated
Loses marks
- Ignoring constant Kd assumption
- Using wrong leverage definition
Earns more
- Show working for Kd calculation
- State final Ke value clearly
Extra mark
- Compare with NI model result
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…
- Q6 (a) Define and explain the concept of merger, takeover and amalgamation. What leads to th…
- Q7 (a) As a Financial Manager of an engineering company, you are required to compute the wei…
- Q8 (a) Explain the structure of Indian financial system. Discuss the emerging role of RBI in…