Paper I — Q4
(a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit procedure to be followed by the Auditor…
State the duties of an Auditor with regard to payment of dividend. Discuss the audit procedure to be followed by the Auditor in respect of checking of payment of dividend. 6+9=15
Discuss the important points that an Investigator must consider in the beginning and during the conduct of an Investigation. How should an investigator draft his report? 6+9=15
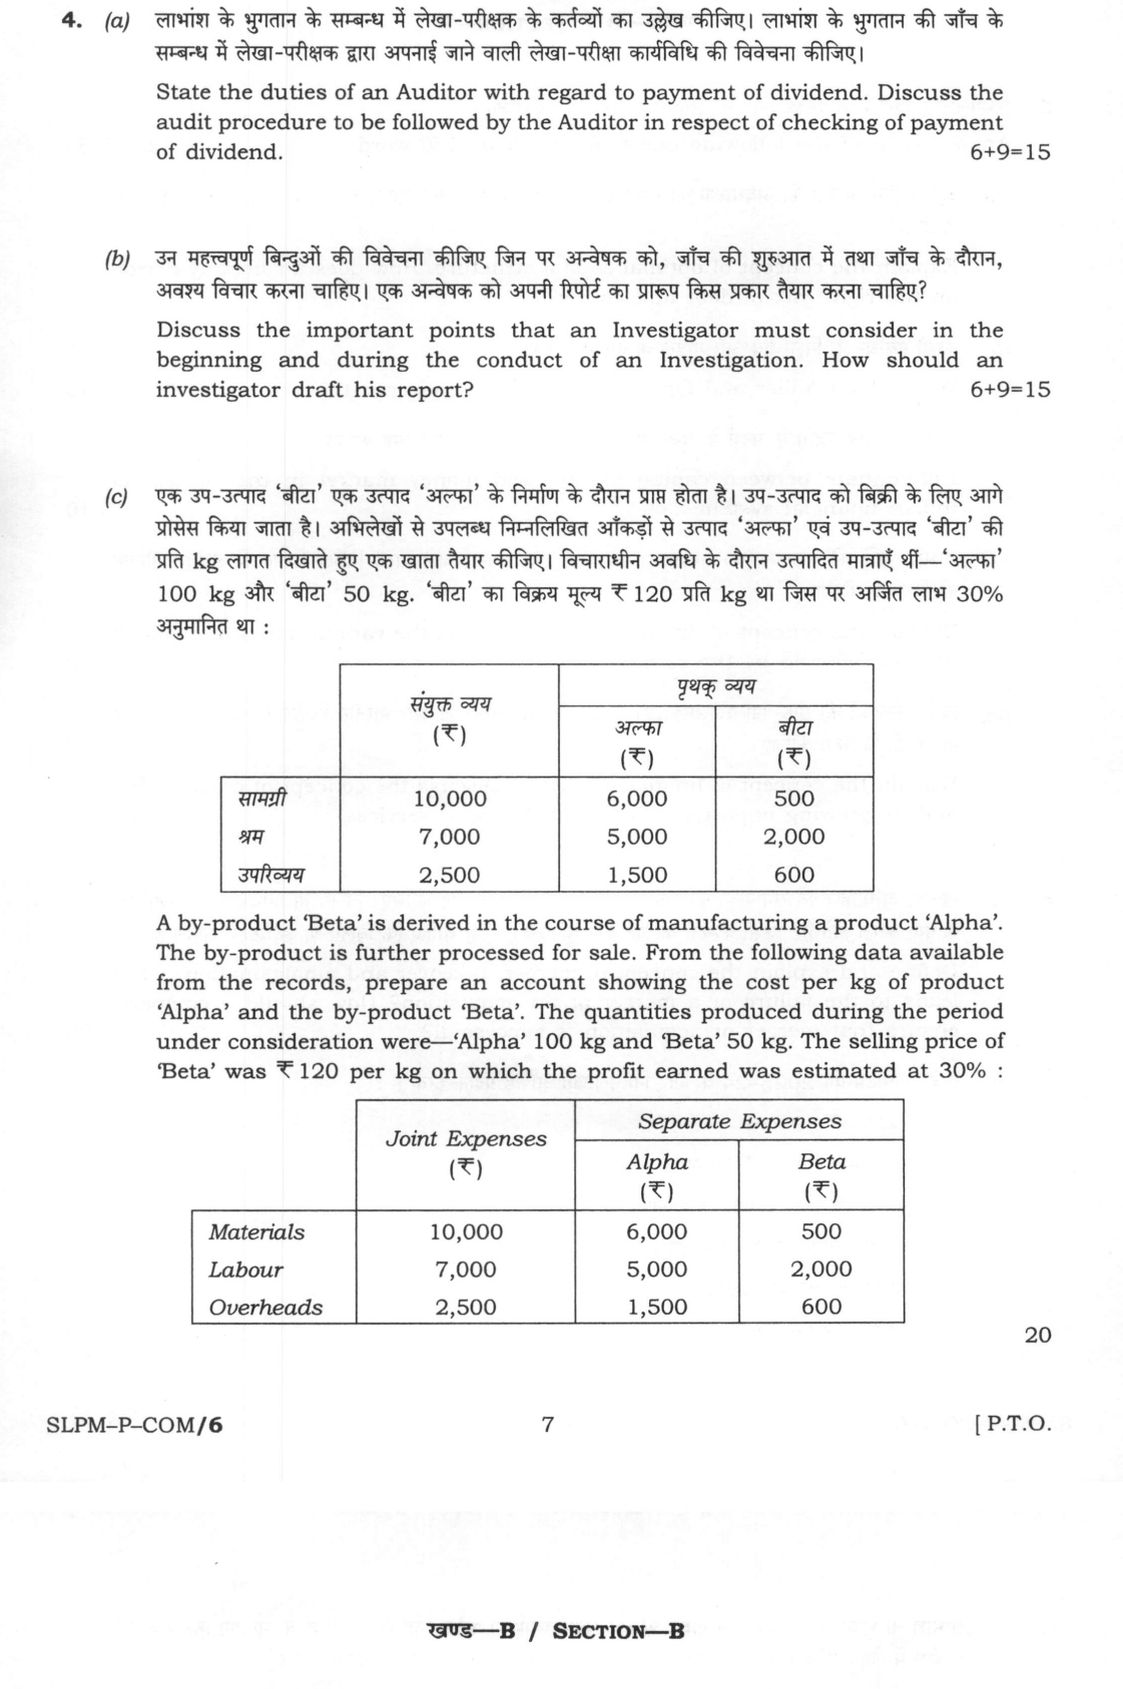
A by-product 'Beta' is derived in the course of manufacturing a product 'Alpha'. The by-product is further processed for sale. From the following data available from the records, prepare an account showing the cost per kg of product 'Alpha' and the by-product 'Beta'. The quantities produced during the period under consideration were—'Alpha' 100 kg and 'Beta' 50 kg. The selling price of 'Beta' was ₹ 120 per kg on which the profit earned was estimated at 30%: 20 marks
हिंदी में प्रश्न पढ़ें
लाभांश के भुगतान के संबंध में लेखा-परीक्षक के कर्तव्यों का उल्लेख कीजिए। लाभांश के भुगतान की जांच के संबंध में लेखा-परीक्षक द्वारा अपनाई जाने वाली लेखा-परीक्षा कार्यविधि की विवेचना कीजिए। 6+9=15
उन महत्वपूर्ण बिंदुओं की विवेचना कीजिए जिन पर अन्वेषक को, जांच की शुरुआत में तथा जांच के दौरान, अवश्य विचार करना चाहिए। एक अन्वेषक को अपनी रिपोर्ट का प्रारूप किस प्रकार तैयार करना चाहिए? 6+9=15
एक उप-उत्पाद 'बीटा' एक उत्पाद 'अल्फा' के निर्माण के दौरान प्राप्त होता है। उप-उत्पाद को बिक्री के लिए आगे प्रोसेस किया जाता है। अभिलेखों से उपलब्ध निम्नलिखित आंकड़ों से उत्पाद 'अल्फा' एवं उप-उत्पाद 'बीटा' की प्रति kg लागत दिखाते हुए एक खाता तैयार कीजिए। विचाराधीन अवधि के दौरान उत्पादित मात्राएं थीं—'अल्फा' 100 kg और 'बीटा' 50 kg. 'बीटा' का विक्रय मूल्य ₹ 120 प्रति kg था जिस पर अर्जित लाभ 30% अनुमानित था: 20 अंक
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(c) Table with columns: 'Joint Expenses (Rs.)', 'Separate Expenses - Alpha (Rs.)', 'Separate Expenses - Beta (Rs.)'. Rows: Materials: 10,000 | 6,000 | 500 Labour: 7,000 | 5,000 | 2,000 Overheads: 2,500 | 1,500 | 600
Trial Balance Table: Header: Particulars | Debit (₹) | Credit (₹) Rows: Equity Capital (Face Value of ₹ 100) | | 20,00,000 Calls-in-Arrears | 2,000 | General Reserve | | 4,60,000 Loan from SBI (Long-term) | | 3,00,000 Land | 4,00,000 | Building | 8,00,000 | Plant & Machinery | 11,00,000 | Furniture | 1,20,000 | Raw Materials | 1,00,000 | Finished Goods | 4,00,000 | Trade Receivables | 3,80,000 | Advances (Short-term) | 90,000 | Provision for Taxation | | 1,38,000 Dividend Payable | | 1,20,000 Profit & Loss A/c | | 1,80,000 Loans (Unsecured) | | 2,50,000 Trade Payables | | 4,00,000 Cash at Bank | 3,86,000 | Cash in Hand | 70,000 | Totals | 38,48,000 | 38,48,000
Additional Information: (i) 6000 Equity Shares were issued for consideration other than cash (ii) Loan from SBI includes ₹ 8,000 for interest accrued but not due. The loan is secured by hypothecation of building (iii) The cost of assets: Building: ₹ 9,60,000 Plant & Machinery: ₹ 14,00,000 Furniture: ₹ 1,80,000 (iv) Trade Receivables of ₹ 1,80,000 are due for 8 months
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a)
The auditor’s duty on dividend is to ensure that the amount paid is lawful, properly authorised and paid to the right members. The auditor should also consider whether the dividend is paid only to members appearing on the record date and whether any shares are pledged, encumbered or subject to a court order. Section 123 of the Companies Act 2013 restricts dividend to profits after providing depreciation, so the auditor must verify that the profit and loss account, prior period losses, depreciation, statutory dues and reserves leave sufficient distributable profit. Section 123(4) contains the five-day deposit requirement and Section 127 the 30-day payment requirement, while Section 124 deals with unclaimed dividend and transfer to the IEPF. The auditor should therefore check board and AGM resolutions, the rate, record date and amount; reconcile the dividend register with the register of members; verify warrants or electronic credits; and examine the treatment of unclaimed dividend. The audit procedure is to obtain the minutes and confirm that declaration is within powers; recompute distributable profit after depreciation and losses; agree dividend per share to the resolution and register; inspect warrants and bank statements for timely payment; trace unclaimed amounts to the Unpaid Dividend Account and any IEPF transfer; and confirm the disclosures in the financial statements. This gives assurance that dividend is not paid out of capital or in breach of the Act.
(b)
An investigation is broader and more flexible than a routine audit because it is directed at a specific purpose: a statutory investigation ordered by the Central Government (sections 210 and 212, including the SFIO) or on an NCLT order (section 213) into fraud or mismanagement, or a non-statutory investigation for a prospective buyer, lender or the management. At the beginning, the investigator must fix the terms of reference, scope, period, document access, legal powers, confidentiality and fee; secure records before tampering; assess the risk of destruction of evidence and preserve digital records; identify directors, banks, registries and third parties; plan interviews; and set up a secure working-paper file. During the investigation, the investigator should gather ledgers, contracts, bank statements and e-mail trails; maintain chain of custody; interview directors, managers, employees and outsiders separately; cross-verify explanations with documents; test samples where the population is large; update findings continuously; note limitations or non-cooperation; and observe legal privilege and data protection. The report should be drafted as a factual, objective and balanced document: state the appointment, scope and methodology; describe evidence examined; present findings with references to documents and interviews; distinguish facts from inferences; give conclusions on each term of reference; and make practical recommendations for recovery, prosecution, governance or accounting correction. It should be clear, concise, supported by annexures, and avoid unsupported accusations. The draft should be reviewed for accuracy, legal sufficiency and consistency with the working papers before finalisation.
(c)
Assuming the 30% profit is on selling price, Beta’s sales are 50 × ₹120 = ₹6,000. Profit = 30% × 6,000 = ₹1,800, so total cost of Beta = ₹4,200. The expense data used are: joint expenses ₹19,500, Alpha's separate expenses ₹12,500 and Beta's separate (further-processing) expenses ₹3,100. Cost of Beta: sales ₹6,000 less profit ₹1,800 gives total cost ₹4,200; less further processing ₹3,100 gives joint cost at split-off ₹1,100. This amount is credited to the joint cost account because Beta is a by-product, not a co-product. Cost of Alpha: joint expenses ₹19,500 less Beta’s split-off value ₹1,100 gives ₹18,400; add Alpha’s separate expenses ₹12,500 gives total cost ₹30,900. For 100 kg, Alpha’s cost is ₹309/kg. Beta’s cost is ₹4,200/50 = ₹84/kg. If the 30% profit were on cost, Beta’s cost would be 6,000/1.30 = ₹4,615.38, joint share ₹1,515.38, Alpha total ₹30,484.62 and per kg ₹304.85, while Beta would be ₹92.31/kg. The account therefore shows Alpha at ₹309/kg and Beta at ₹84/kg.
How this answer will be evaluated
Framework: SLPM-P-COM/6 (Symbiosis Distance Education)
What earns full marks: Precise statutory references, logical flow, and accurate calculations with clear workings.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Duties of Auditor regarding dividend and audit procedure for checking payment. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Duties: lawfulness and authorisation; correct members; §§123, 123(4), 124 (IEPF) and 127 compliance
- Audit procedure: resolutions; recompute distributable profits; dividend register vs members' register; warrants/electronic credits
- Unpaid Dividend Account/IEPF follow-up; disclosure check; assurance that dividend is not paid out of capital
Loses marks
- Confusing auditor duties with board duties
- Omitting the 'checking' procedure steps
Earns more
- Mention of Companies Act Section 123
- Reference to dividend distribution account
- Checking for unclaimed dividend transfer
Extra mark
- Citing specific Companies Act sections
- (b) Points for investigator at start/during investigation and report drafting. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Investigation vs audit; at the start: terms of reference, scope, powers, confidentiality, evidence preservation
- During: documents/email trails, chain of custody, interviews, cross-verification, sampling, limitations
- Report: factual, objective; appointment/scope/methodology; findings with references; facts vs inferences
- Conclusions per term of reference, recommendations, annexures, legal review
Loses marks
- Vague generalities without specific steps
- Ignoring the 'report drafting' component
Earns more
- Mention of 'chain of custody' for evidence
- Reference to 'fairness' in report drafting
- Structure of report (intro, findings, conclusion)
Extra mark
- Citing specific investigative standards
- (c) Account showing cost per kg of Alpha and Beta. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Beta sales 6,000 − 30% profit 1,800 = cost 4,200; less separate 3,100 → joint-cost share 1,100 credited to joint cost
- Alpha = 19,500 − 1,100 + 12,500 = 30,900 → ₹309/kg
- Beta = 4,200/50 = ₹84/kg
- Alternative (profit on cost): Alpha ₹304.85/kg and Beta ₹92.31/kg
Loses marks
- Final figures without workings
- Incorrect calculation of Beta's cost
Earns more
- Clear working notes for Beta's cost
- Proper statement format for cost allocation
Extra mark
- Explicit statement of assumptions
What "Discuss" is asking you to do
Lay the issue out from more than one side — how it arose, what is claimed for it, what is held against it, and where it now stands. UPSC attaches discuss to broad topics with several live dimensions, so coverage of the dimensions earns more than the strength of your opinion.
Structure that answers it
Set the issue up → the case as it is made → the case against → the dimension both sides leave out → where the balance now lies
Where marks are lost
Listing facts with no thread between them, or arguing one side throughout and calling it a discussion.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q1 Answer each of the following questions in about 150 words: (a) Discuss the key points tha…
- Q2 From the following Trial Balance and other additional information furnished by AGN Ltd.,…
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…
- Q6 (a) Define and explain the concept of merger, takeover and amalgamation. What leads to th…
- Q7 (a) As a Financial Manager of an engineering company, you are required to compute the wei…