Paper I — Q1
(a) Discuss the key points that an Auditor would take into consideration while auditing the books of accounts of an insurance…
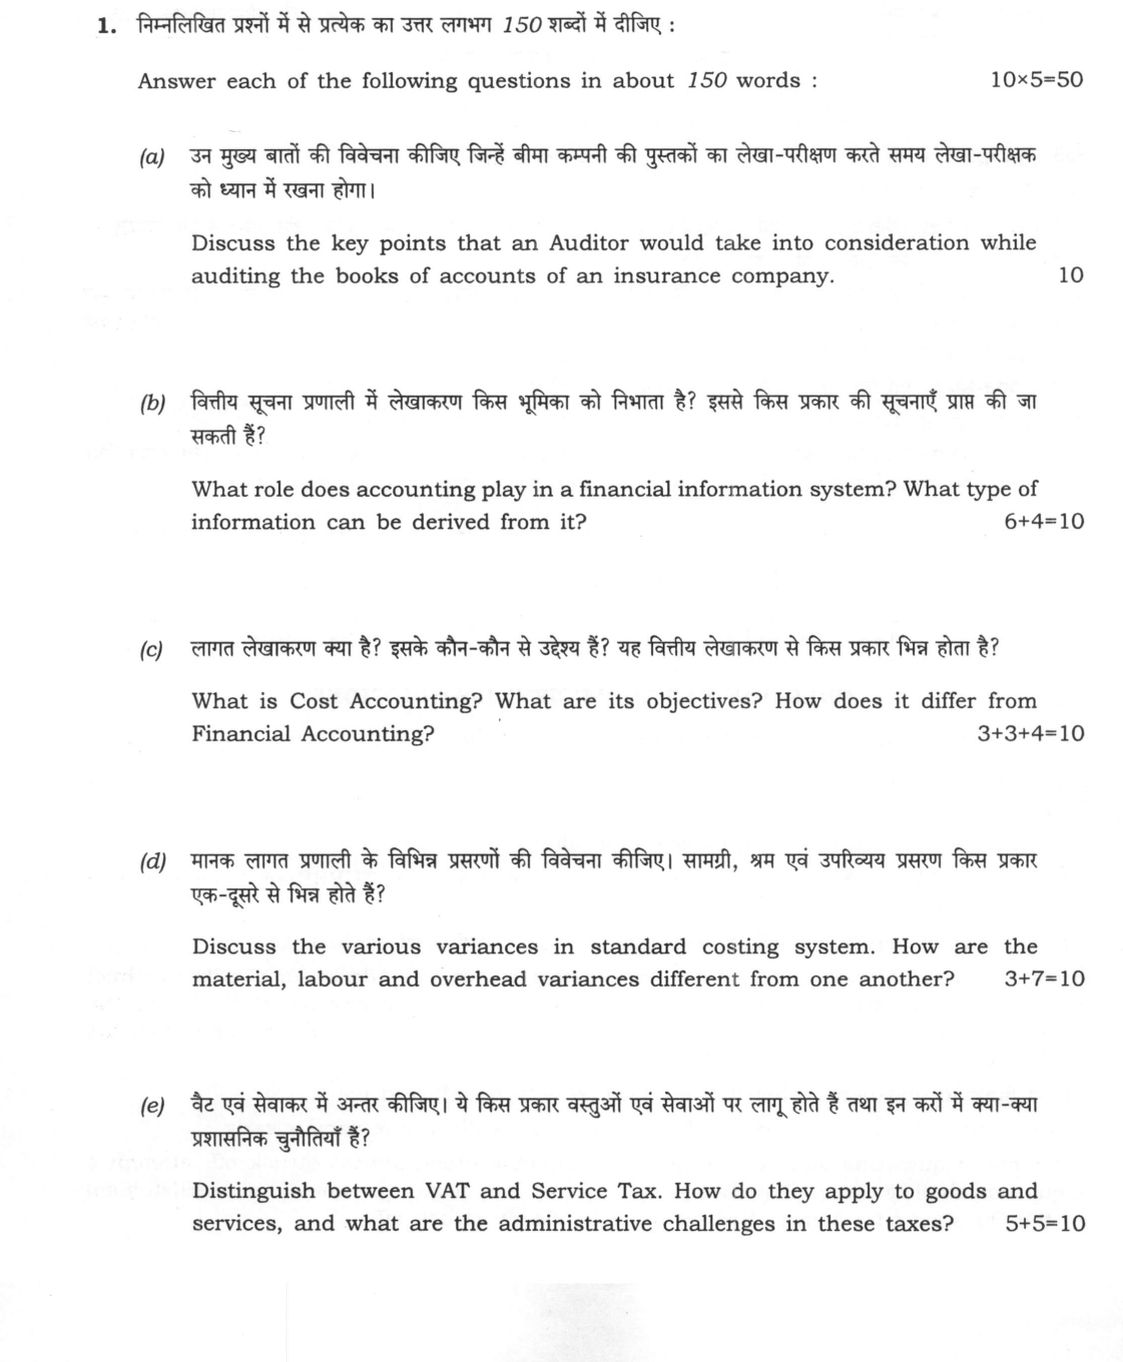
Answer each of the following questions in about 150 words:
Discuss the key points that an Auditor would take into consideration while auditing the books of accounts of an insurance company. 10 marks
What role does accounting play in a financial information system? What type of information can be derived from it? (6+4=10 marks)
What is Cost Accounting? What are its objectives? How does it differ from Financial Accounting? (3+3+4=10 marks)
Discuss the various variances in standard costing system. How are the material, labour and overhead variances different from one another? (3+7=10 marks)
Distinguish between VAT and Service Tax. How do they apply to goods and services, and what are the administrative challenges in these taxes? (5+5=10 marks)
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए :
उन मुख्य बातों की विवेचना कीजिए जिन्हें बीमा कंपनी की पुस्तकों का लेखा-परीक्षण करते समय लेखा-परीक्षक को ध्यान में रखना होगा। (10 अंक)
वित्तीय सूचना प्रणाली में लेखाकरण किस भूमिका को निभाता है? इससे किस प्रकार की सूचनाएं प्राप्त की जा सकती हैं? (6+4=10 अंक)
लागत लेखाकरण क्या है? इसके कौन-कौन से उद्देश्य हैं? यह वित्तीय लेखाकरण से किस प्रकार भिन्न होता है? (3+3+4=10 अंक)
मानक लागत प्रणाली के विभिन्न प्रसरणों की विवेचना कीजिए। सामग्री, श्रम एवं उपरिव्यय प्रसरण किस प्रकार एक-दूसरे से भिन्न होते हैं? (3+7=10 अंक)
वैट एवं सेवाकर में अंतर कीजिए। ये किस प्रकार वस्तुओं एवं सेवाओं पर लागू होते हैं तथा इन करों में क्या-क्या प्रशासनिक चुनौतियां हैं? (5+5=10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Audit Considerations for an Insurance Company
Auditing an insurance company requires verifying strict adherence to statutory frameworks, primarily the Insurance Act 1938, the IRDA Act 1999, and the IRDAI (Actuarial, Finance and Investment Functions of Insurers) Regulations, 2024, which replaced the 2002 financial statements regulations. First, the auditor must examine revenue recognition, ensuring premium income is accounted for on an accrual basis net of service taxes/GST, alongside adequate provision for Unearned Premium Reserves (UPR) and Premium Deficiency Reserves. Second, claims provisioning demands rigorous verification of claims paid, claims outstanding, and actuarially computed reserves for Incurred But Not Reported (IBNR) and Incurred But Not Enough Reported (IBNER) claims. Third, reinsurance ceded and accepted must be verified to assess risk retention limits, commission structures, and outstanding recoveries. Fourth, the auditor evaluates the investment portfolio, ensuring compliance with prudential investment norms and prescribed valuation principles (fair value for equity, amortized cost for debt). A balanced audit approach necessitates reconciling financial figures with appointed actuaries' reports while examining internal controls over policy underwriting and collections.
(b) Role of Accounting in a Financial Information System
Accounting serves as the core data transformation engine within an enterprise Financial Information System (FIS), converting unstructured transactional data into structured, decision-useful financial intelligence. It fulfills a dual role: stewardship accountability, which provides historical, verifiable records of resource stewardship for compliance and governance; and predictive decision-support, which facilitates forward-looking resource allocation.
From this subsystem, diverse categories of information are derived. For operational control, it yields segment-wise profitability, cost-centre performance metrics, and inventory turnover figures. For tactical and strategic planning, the system produces cash flow projections, working capital cycles, and capital expenditure variances. Externally, it generates structured indicators including liquidity ratios (current and quick ratios), solvency measures (debt-equity, interest coverage), and valuation metrics (earnings per share, return on capital employed). By integrating operational inputs into standard formats, accounting enhances transparency, mitigates information asymmetry, and enables dynamic scenario modeling for executive leadership.
(c) Cost Accounting: Nature, Objectives, and Distinctions
Cost Accounting is the application of costing principles, methods, and techniques to ascertain profitability and control the costs of activities, processes, and products. Its primary objectives include precise cost ascertainment, cost control through predetermined targets, cost reduction through value engineering, guidance for pricing decisions, and supplying relevant cost data for managerial decision-making, such as make-or-buy and product-mix choices.
It differs fundamentally from Financial Accounting across multiple parameters. Financial Accounting caters primarily to external stakeholders (shareholders, creditors, regulators) to present a true and fair view of overall financial health; Cost Accounting serves internal management for operational control. Financial statements are prepared periodically (quarterly or annually) based strictly on historical transactions under rigid statutory frameworks. In contrast, cost accounts are generated continuously—often daily or batch-wise—utilizing historical data, current standards, and future estimates. While Financial Accounting classifies expenses by natural classification (e.g., salaries, rent), Cost Accounting classifies costs by function, behaviour (fixed versus variable), and direct/indirect traceability, providing granular operational visibility.
(d) Variances in Standard Costing Systems
A standard costing system breaks down performance deviations into specific variances across cost elements to fix operational responsibility.
Material variances measure deviations in tangible inputs, split into Material Price Variance (difference in standard vs actual purchase price, handled by procurement) and Material Usage Variance (quantities consumed on shop floors), which further subdivides into Material Mix and Yield Variances when inputs are substitutable.
Labour variances evaluate human resource costs, segregated into Labour Rate Variance (wage differentials), Labour Efficiency Variance (standard vs actual operational hours), Idle Time Variance (unproductive paid time), and Labour Gang/Mix and Yield Variances.
Overhead variances evaluate capacity and indirect expenditure. Variable Overhead divides into Spending (rate) and Efficiency variances. Fixed Overhead divides into Expenditure/Budget Variance and Volume Variance, with the latter further analyzed into Capacity (plant utilization), Calendar (working days), and Efficiency variances.
These categories differ based on the nature of the resource and degree of controllability. Material and labour variances directly reflect physical input efficiency and market price volatility, whereas fixed overhead variances reflect structural time-utilization and macroeconomic demand fluctuations influencing installed capacity.
(e) VAT versus Service Tax: Distinctions and Challenges
Under the erstwhile indirect tax structure, Value Added Tax (VAT) was a state-level, multi-point tax levied under each State's VAT Act on the intra-state sale of goods, with input tax credit (ITC) across successive sales stages to remove cascading; inter-state sales attracted the origin-based Central Sales Tax, for which no credit was available. Service Tax, conversely, was a Union levy under Chapter V of the Finance Act 1994 on taxable services (on a negative-list basis from July 2012), with the Place of Provision of Services Rules, 2012 making it effectively destination-based: exports were relieved and imported services were taxed under reverse charge. Credit ran through the CENVAT Credit Rules, 2004.
The two systems diverged in tax base, point of taxation, and jurisdiction: VAT was governed by state-specific statutes triggered by the transfer of property in goods, whereas Service Tax was uniformly administered by the Central Board of Excise and Customs based on the Point of Taxation Rules.
Administrative challenges were substantial. Invoice matching across disjointed state boundaries proved cumbersome, leading to evasion. The absence of seamless cross-credit between state VAT and central Service Tax resulted in stranded taxes. Most critically, composite transactions—such as works contracts, software delivery, and restaurant services—suffered from jurisdictional overlap and double taxation, prompting protracted litigation (BSNL v. Union of India) before being unified under the Goods and Services Tax framework.
How this answer will be evaluated
What earns full marks: Precise, specific to the question, uses correct terminology, and addresses all sub-parts with depth.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Key audit considerations specific to insurance company accounts. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Insurance Act 1938, IRDA Act 1999 and IRDAI (AFIF) Regulations 2024 (which repealed the 2002 financial statements regulations) — verified
- Premium income on accrual basis, net of service tax/GST; UPR and premium deficiency reserves
- Claims: paid/outstanding plus actuarial IBNR/IBNER reserves
- Reinsurance (retention, commission, recoveries) and investment portfolio (prudential norms; fair value/amortised cost)
Loses marks
- Generic audit points not specific to insurance
- Ignoring actuarial aspects of the audit
Earns more
- Mention of ICAI audit standards for insurance
- Reference to IRDAI guidelines
- Discussion of reinsurance recoverables
Extra mark
- Citation of specific ICAI Audit Standards
- Reference to specific IRDAI circulars
- (b) Role of accounting in financial information systems and derived data. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Accounting as the core data-transformation engine of the FIS
- Dual role: stewardship/compliance records and forward-looking decision support
- Information types: segment profitability, cost-centre metrics (operational); cash-flow projections, working-capital cycles (planning)
- External indicators: liquidity, solvency and valuation ratios; reduces information asymmetry
Loses marks
- Confusing accounting with general bookkeeping
- Failing to distinguish types of information
Earns more
- Mention of internal vs external users
- Reference to management accounting data
- Discussion of historical vs predictive data
Extra mark
- Reference to specific accounting standards (Ind AS)
- Mention of specific financial ratios derived
- (c) Definition, objectives, and differences of Cost Accounting. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Definition: application of costing principles/methods to ascertain and control costs
- Objectives: cost ascertainment, control, reduction, pricing guidance, managerial decisions
- Differs from financial accounting: external vs internal users; periodic/statutory vs continuous/flexible
- Classification: natural vs functional/behavioural (fixed-variable) and direct/indirect
Loses marks
- Vague definition of cost accounting
- Failing to distinguish from financial accounting
Earns more
- Mention of cost centers and responsibility accounting
- Reference to management decision support
- Distinction in legal requirements
Extra mark
- Reference to CMA guidelines
- Specific example of cost control
- (d) Standard costing variances and their specific differences. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Material: price and usage variances; mix and yield sub-variances
- Labour: rate, efficiency, idle-time, gang/mix and yield variances
- Variable overhead: spending and efficiency; Fixed overhead: expenditure/budget and volume (capacity, calendar, efficiency)
- Explains how the three groups differ: physical input efficiency and prices vs structural capacity/time utilisation
Loses marks
- Confusing variance types (e.g., price vs usage)
- Failing to distinguish material, labour, overhead
Earns more
- Explanation of favorable vs unfavorable variances
- Mention of variance analysis for control
- Reference to standard cost cards
Extra mark
- Specific formula for variance calculation
- Reference to CMA standards
- (e) Distinction between VAT and Service Tax, application, and challenges. 10 marks · 150 words
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- VAT: state-level multi-point tax on intra-state sale of goods with ITC; inter-state sales under origin-based CST without credit
- Service Tax: Union levy under Chapter V of the Finance Act 1994 (negative list from 2012); Place of Provision Rules made it effectively destination-based; CENVAT credit
- Administrative challenges: invoice matching across states, no seamless cross-credit (stranded taxes), composite-transaction overlap/double taxation
- BSNL v. Union of India examples the composite-contract litigation; resolved by GST
Loses marks
- Confusing the scope of VAT and Service Tax
- Failing to address administrative challenges
Earns more
- Mention of input tax credit mechanisms
- Reference to GST as a unifying reform
- Discussion of compliance burden
Extra mark
- Reference to specific GST transition provisions
- Mention of specific court cases on jurisdiction
What "Discuss" is asking you to do
Lay the issue out from more than one side — how it arose, what is claimed for it, what is held against it, and where it now stands. UPSC attaches discuss to broad topics with several live dimensions, so coverage of the dimensions earns more than the strength of your opinion.
Structure that answers it
Set the issue up → the case as it is made → the case against → the dimension both sides leave out → where the balance now lies
Where marks are lost
Listing facts with no thread between them, or arguing one side throughout and calling it a discussion.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q1 Answer each of the following questions in about 150 words: (a) Discuss the key points tha…
- Q2 From the following Trial Balance and other additional information furnished by AGN Ltd.,…
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…