Paper I — Q2
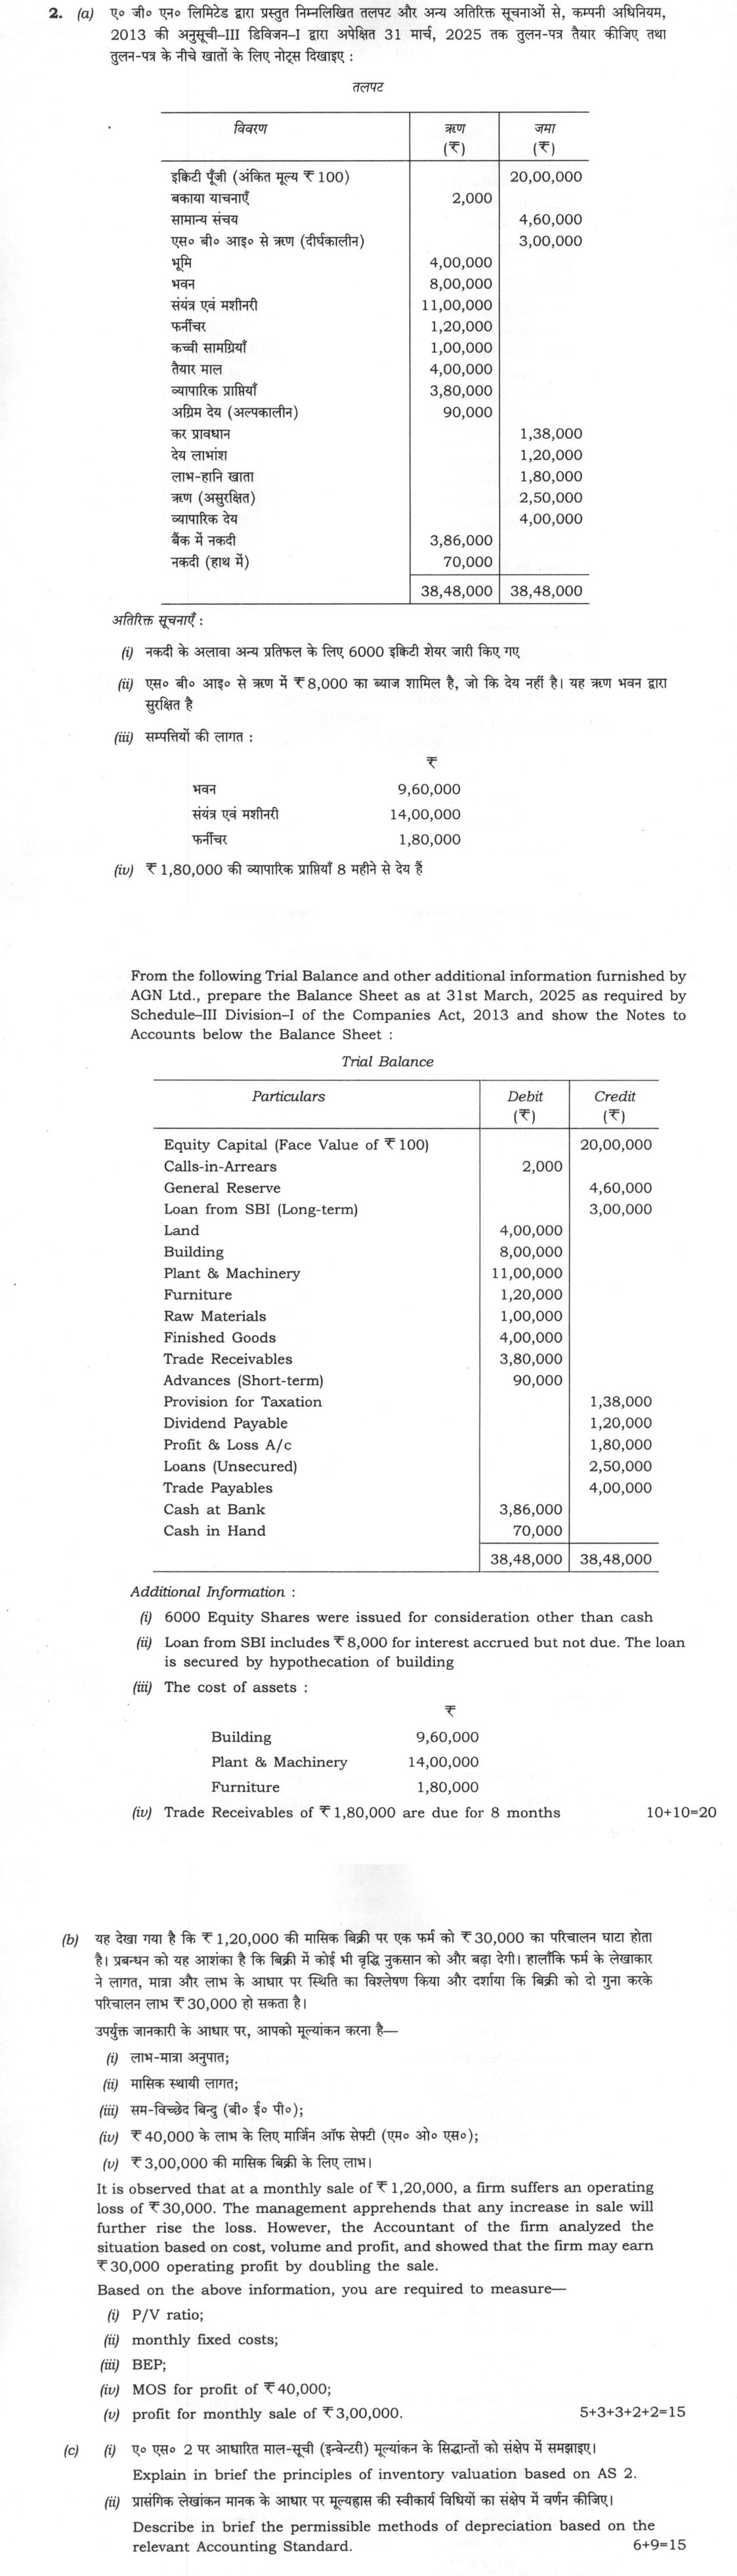
From the following Trial Balance and other additional information furnished by AGN Ltd., prepare the Balance Sheet as at 31st…
From the following Trial Balance and other additional information furnished by AGN Ltd., prepare the Balance Sheet as at 31st March, 2025 as required by Schedule-III Division-I of the Companies Act, 2013 and show the Notes to Accounts below the Balance Sheet:
Trial Balance
| Particulars | Debit (₹) | Credit (₹) |
|---|---|---|
| Equity Capital (Face Value of ₹ 100) | 20,00,000 | |
| Calls-in-Arrears | 2,000 | |
| General Reserve | 4,60,000 | |
| Loan from SBI (Long-term) | 3,00,000 | |
| Land | 4,00,000 | |
| Building | 8,00,000 | |
| Plant & Machinery | 11,00,000 | |
| Furniture | 1,20,000 | |
| Raw Materials | 1,00,000 | |
| Finished Goods | 4,00,000 | |
| Trade Receivables | 3,80,000 | |
| Advances (Short-term) | 90,000 | |
| Provision for Taxation | 1,38,000 | |
| Dividend Payable | 1,20,000 | |
| Profit & Loss A/c | 1,80,000 | |
| Loans (Unsecured) | 2,50,000 | |
| Trade Payables | 4,00,000 | |
| Cash at Bank | 3,86,000 | |
| Cash in Hand | 70,000 | |
| 38,48,000 | 38,48,000 |
Additional Information:
6000 Equity Shares were issued for consideration other than cash
Loan from SBI includes ₹ 8,000 for interest accrued but not due. The loan is secured by hypothecation of building
The cost of assets:
| ₹ | |
|---|---|
| Building | 9,60,000 |
| Plant & Machinery | 14,00,000 |
| Furniture | 1,80,000 |
Trade Receivables of ₹ 1,80,000 are due for 8 months
(10+10=20 marks)
It is observed that at a monthly sale of ₹ 1,20,000, a firm suffers an operating loss of ₹ 30,000. The management apprehends that any increase in sale will further rise the loss. However, the Accountant of the firm analyzed the situation based on cost, volume and profit, and showed that the firm may earn ₹ 30,000 operating profit by doubling the sale.
Based on the above information, you are required to measure—
P/V ratio;
monthly fixed costs;
BEP;
MOS for profit of ₹ 40,000;
profit for monthly sale of ₹ 3,00,000. (5+3+3+2+2=15 marks)
Explain in brief the principles of inventory valuation based on AS 2.
Describe in brief the permissible methods of depreciation based on the relevant Accounting Standard. (6+9=15 marks)
हिंदी में प्रश्न पढ़ें
ए० जी० एन० लिमिटेड द्वारा प्रस्तुत निम्नलिखित तलपट और अन्य अतिरिक्त सूचनाओं से, कम्पनी अधिनियम, 2013 की अनुसूची-III डिविजन-I द्वारा अपेक्षित 31 मार्च, 2025 तक तुलन-पत्र तैयार कीजिए तथा तुलन-पत्र के नीचे खातों के लिए नोट्स दिखाइए :
तलपट
| विवरण | ऋण (₹) | जमा (₹) |
|---|---|---|
| इक्विटी पूँजी (अंकित मूल्य ₹ 100) | 20,00,000 | |
| बकाया याचनाएँ | 2,000 | |
| सामान्य संचय | 4,60,000 | |
| एस० बी० आई० से ऋण (दीर्घकालीन) | 3,00,000 | |
| भूमि | 4,00,000 | |
| भवन | 8,00,000 | |
| संयंत्र एवं मशीनरी | 11,00,000 | |
| फर्नीचर | 1,20,000 | |
| कच्ची सामग्रियाँ | 1,00,000 | |
| तैयार माल | 4,00,000 | |
| व्यापारिक प्राप्तियाँ | 3,80,000 | |
| अग्रिम देय (अल्पकालीन) | 90,000 | |
| कर प्रावधान | 1,38,000 | |
| देय लाभांश | 1,20,000 | |
| लाभ-हानि खाता | 1,80,000 | |
| ऋण (असुरक्षित) | 2,50,000 | |
| व्यापारिक देय | 4,00,000 | |
| बैंक में नकदी | 3,86,000 | |
| नकदी (हाथ में) | 70,000 | |
| 38,48,000 | 38,48,000 |
अतिरिक्त सूचनाएँ :
नकदी के अलावा अन्य प्रतिफल के लिए 6000 इक्विटी शेयर जारी किए गए
एस० बी० आई० से ऋण में ₹ 8,000 का ब्याज शामिल है, जो कि देय नहीं है। यह ऋण भवन द्वारा सुरक्षित है
सम्पत्तियों की लागत :
| ₹ | |
|---|---|
| भवन | 9,60,000 |
| संयंत्र एवं मशीनरी | 14,00,000 |
| फर्नीचर | 1,80,000 |
₹ 1,80,000 की व्यापारिक प्राप्तियाँ 8 महीने से देय हैं
(10+10=20 अंक)
यह देखा गया है कि ₹ 1,20,000 की मासिक बिक्री पर एक फर्म को ₹ 30,000 का परिचालन घाटा होता है। प्रबंधन को यह आशंका है कि बिक्री में कोई भी वृद्धि नुकसान को और बढ़ा देगी। हालांकि फर्म के लेखाकार ने लागत, मात्रा और लाभ के आधार पर स्थिति का विश्लेषण किया और दर्शाया कि बिक्री को दो गुना करके परिचालन लाभ ₹ 30,000 हो सकता है।
उपर्युक्त जानकारी के आधार पर, आपको मूल्यांकन करना है—
लाभ-मात्रा अनुपात;
मासिक स्थायी लागत;
सम-विच्छेद बिंदु (बी० ई० पी०);
₹ 40,000 के लाभ के लिए मार्जिन ऑफ सेफ्टी (एम० ओ० एस०);
₹ 3,00,000 की मासिक बिक्री के लिए लाभ। (5+3+3+2+2=15 अंक)
ए० एस० 2 पर आधारित माल-सूची (इन्वेंटरी) मूल्यांकन के सिद्धांतों को संक्षेप में समझाइए।
प्रासंगिक लेखांकन मानक के आधार पर मूल्यह्रास की स्वीकार्य विधियों का संक्षेप में वर्णन कीजिए। (6+9=15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a)
Balance Sheet of AGN Ltd. as at 31st March, 2025 (Schedule III, Division I)
Equity and Liabilities
- Shareholders’ funds: Share capital ₹19,98,000 (Note 1); Reserves and surplus ₹6,40,000 (Note 2); total ₹26,38,000
- Non-current liabilities: Long-term borrowings ₹5,42,000 (Note 3)
- Current liabilities: Trade payables ₹4,00,000 (Note 4); Other current liabilities ₹1,28,000 (Note 5); Short-term provisions ₹1,38,000 (Note 6); total ₹6,66,000
- Total equity and liabilities: ₹38,46,000
Assets
- Non-current assets: Property, Plant and Equipment ₹24,20,000 (Note 7)
- Current assets: Inventories ₹5,00,000 (Note 8); Trade receivables ₹3,80,000 (Note 9); Short-term loans and advances ₹90,000 (Note 10); Cash and cash equivalents ₹4,56,000 (Note 11); total ₹14,26,000
- Total assets: ₹38,46,000
Notes to Accounts
- Share Capital:
- 20,000 Equity Shares of ₹100 each fully called-up: ₹20,00,000
- Less: Calls-in-arrears: ₹2,000
- Paid-up share capital: ₹19,98,000
- Out of above, 6,000 equity shares were issued for consideration other than cash.
- Reserves and Surplus:
- General Reserve: ₹4,60,000
- Surplus as per Profit and Loss A/c: ₹1,80,000
- Total: ₹6,40,000
- Long-term Borrowings:
- Secured loan from SBI: ₹2,92,000 (secured by hypothecation of building; excludes ₹8,000 interest accrued but not due)
- Unsecured loans: ₹2,50,000 (treated as long-term; no current maturity given)
- Total: ₹5,42,000
- Trade Payables: ₹4,00,000
- Other Current Liabilities:
- Dividend payable: ₹1,20,000
- Interest accrued but not due on SBI loan: ₹8,000
- Total: ₹1,28,000
- Short-term Provisions:
- Provision for taxation: ₹1,38,000
- Property, Plant and Equipment:
- Land: ₹4,00,000
- Building: cost ₹9,60,000 − accumulated depreciation ₹1,60,000 = ₹8,00,000
- Plant and Machinery: cost ₹14,00,000 − accumulated depreciation ₹3,00,000 = ₹11,00,000
- Furniture: cost ₹1,80,000 − accumulated depreciation ₹60,000 = ₹1,20,000
- Net PPE: ₹24,20,000 (gross ₹29,40,000; accumulated depreciation ₹5,20,000)
- Inventories:
- Raw materials: ₹1,00,000
- Finished goods: ₹4,00,000
- Total: ₹5,00,000
- Trade Receivables:
- Outstanding for more than six months: ₹1,80,000
- Others: ₹2,00,000
- Total: ₹3,80,000
- Short-term Loans and Advances:
- Advances: ₹90,000
- Cash and Cash Equivalents:
- Cash at bank: ₹3,86,000
- Cash in hand: ₹70,000
- Total: ₹4,56,000
(b)
Let P/V ratio = p and monthly fixed cost = F. At sale ₹1,20,000, loss = ₹30,000:
- 1,20,000p − F = −30,000 … (1) At double sale ₹2,40,000, profit = ₹30,000:
- 2,40,000p − F = 30,000 … (2) Subtracting (1) from (2): 1,20,000p = 60,000, so p = 0.50 = 50%. Putting p in (1): 60,000 − F = −30,000, so F = ₹90,000.
(i) P/V ratio = 50%. (ii) Monthly fixed costs = ₹90,000. (iii) BEP = Fixed cost ÷ P/V ratio = 90,000 ÷ 0.50 = ₹1,80,000. (iv) MOS for profit ₹40,000 = Profit ÷ P/V ratio = 40,000 ÷ 0.50 = ₹80,000. (v) Profit at sale ₹3,00,000 = 3,00,000 × 0.50 − 90,000 = ₹60,000.
(c)(i)
Principles of inventory valuation under AS 2:
- Inventory is valued at lower of cost and net realisable value (NRV), generally item by item.
- Cost includes purchase cost, conversion cost and other costs incurred to bring inventory to its present location and condition.
- Abnormal waste, non-production storage, administration and selling overheads are excluded.
- Cost formula: specific identification for non-interchangeable goods; FIFO or weighted average for other inventories. LIFO is not permitted under AS 2.
- NRV = estimated selling price less estimated completion and selling costs.
- The comparison of cost and NRV is made at each balance sheet date, item by item or for groups of similar items; materials held for production are not written down below cost if the finished products are expected to sell at or above cost.
(c)(ii)
Permissible methods of depreciation under AS 10 (Property, Plant and Equipment):
- Depreciation is systematic allocation of depreciable amount over useful life. Depreciable amount = cost − residual value.
- Permissible methods include straight-line method, diminishing balance/written down value method, units of production/usage method, and any other systematic method reflecting the pattern of consumption of economic benefits.
- The method must be applied consistently; a change is treated as a change in accounting estimate and its effect is disclosed.
- Residual value and useful life are reviewed at least annually; changes are accounted prospectively.
- Depreciation begins when the asset is available for use and ceases on disposal or when fully depreciated; it is not stopped merely because the asset is idle.
- Significant components are depreciated separately; land is generally not depreciated unless it has a depletable nature.
How this answer will be evaluated
Framework: Schedule-III Division-I (Companies Act, 2013)
What earns full marks: Precise statutory format, complete workings, and accurate theoretical application.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Prepare Balance Sheet as at 31st March, 2025 with Notes to Accounts. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Correct Schedule III classification: equity/share capital 19,98,000; reserves 6,40,000; non-current borrowings 5,42,000
- Current liabilities: trade payables 4,00,000; other current liabilities 1,28,000 (dividend 1,20,000 + interest accrued 8,000); provisions 1,38,000
- Assets: PPE 24,20,000 (with cost/depreciation notes); inventories 5,00,000; receivables 3,80,000 (1,80,000 > 6 months); advances 90,000; cash 4,56,000
- Balance sheet total 38,46,000 = 38,46,000; notes for share capital (calls-in-arrears, shares for consideration other than cash), loan interest, asset costs
Loses marks
- Omitting Notes to Accounts
- Incorrect treatment of accrued interest
- Failure to show cost of assets in notes
Earns more
- Correct presentation of 'Loans' vs 'Other Liabilities'
- Accurate calculation of net block of assets
- Proper disclosure of 'Calls-in-Arrears'
Extra mark
- Explicit mention of Schedule-III Division-I
- (b) Measure P/V ratio, fixed costs, BEP, MOS, and profit at ₹3,00,000 sales. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Equations: 1,20,000p − F = −30,000 and 2,40,000p − F = +30,000 → P/V ratio = 50%
- Monthly fixed cost = ₹90,000
- BEP = F/PV = ₹1,80,000
- MOS for ₹40,000 profit = ₹80,000; profit at ₹3,00,000 sales = ₹60,000
Loses marks
- Final figures without workings
- Incorrect assumption of variable cost behavior
Earns more
- Clear step-by-step working for each sub-part
- Correct interpretation of 'doubling the sale' scenario
Extra mark
- Explicit formula citation for P/V ratio
- (c)(i) Explain principles of inventory valuation based on AS 2. 6 marks
explain— definition/context → points in order → small example → short close
Must cover
- Lower of cost and NRV (item by item)
- Cost = purchase + conversion + other costs to bring inventory to present condition; excludes abnormal waste/admin/selling overheads
- Cost formulas: specific identification; FIFO/weighted average (LIFO not permitted)
- Comparison at each balance sheet date, item-wise or by groups of similar items; raw materials not written down if finished goods sell at or above cost
Loses marks
- Confusing AS 2 with Ind AS 2
- Omitting the NRV concept
Earns more
- Mention of FIFO/Weighted Average methods
- Distinction between cost and NRV
Extra mark
- Reference to specific AS 2 paragraph numbers
- (c)(ii) Describe permissible methods of depreciation based on Accounting Standards. 9 marks
describe— define → structure or process in order → labelled diagram → significance
Must cover
- Depreciation = systematic allocation of depreciable amount over useful life (AS 10)
- SLM and WDV/diminishing balance identified; units-of-production/other systematic methods allowed
- Method applied consistently; change = change in accounting estimate with disclosure
- Residual value/useful life reviewed annually; components depreciated separately; land generally not depreciated
Loses marks
- Presenting tax-rate (Income-tax Act) depreciation as an AS 10 method
- Failing to cite AS 10
Earns more
- Explanation of the 'change in estimate' rule
- Mention of useful life and residual value
Extra mark
- Brief example of depreciation calculation
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2025 Paper I
- Q1 Answer each of the following questions in about 150 words: (a) Discuss the key points tha…
- Q2 From the following Trial Balance and other additional information furnished by AGN Ltd.,…
- Q3 (a) Explain in brief the deductions that are expressly allowed in computing the income fr…
- Q4 (a) State the duties of an Auditor with regard to payment of dividend. Discuss the audit…
- Q5 Answer each of the following questions in about 150 words : 10×5=50 (a) Explain the conce…