Paper I — Q2
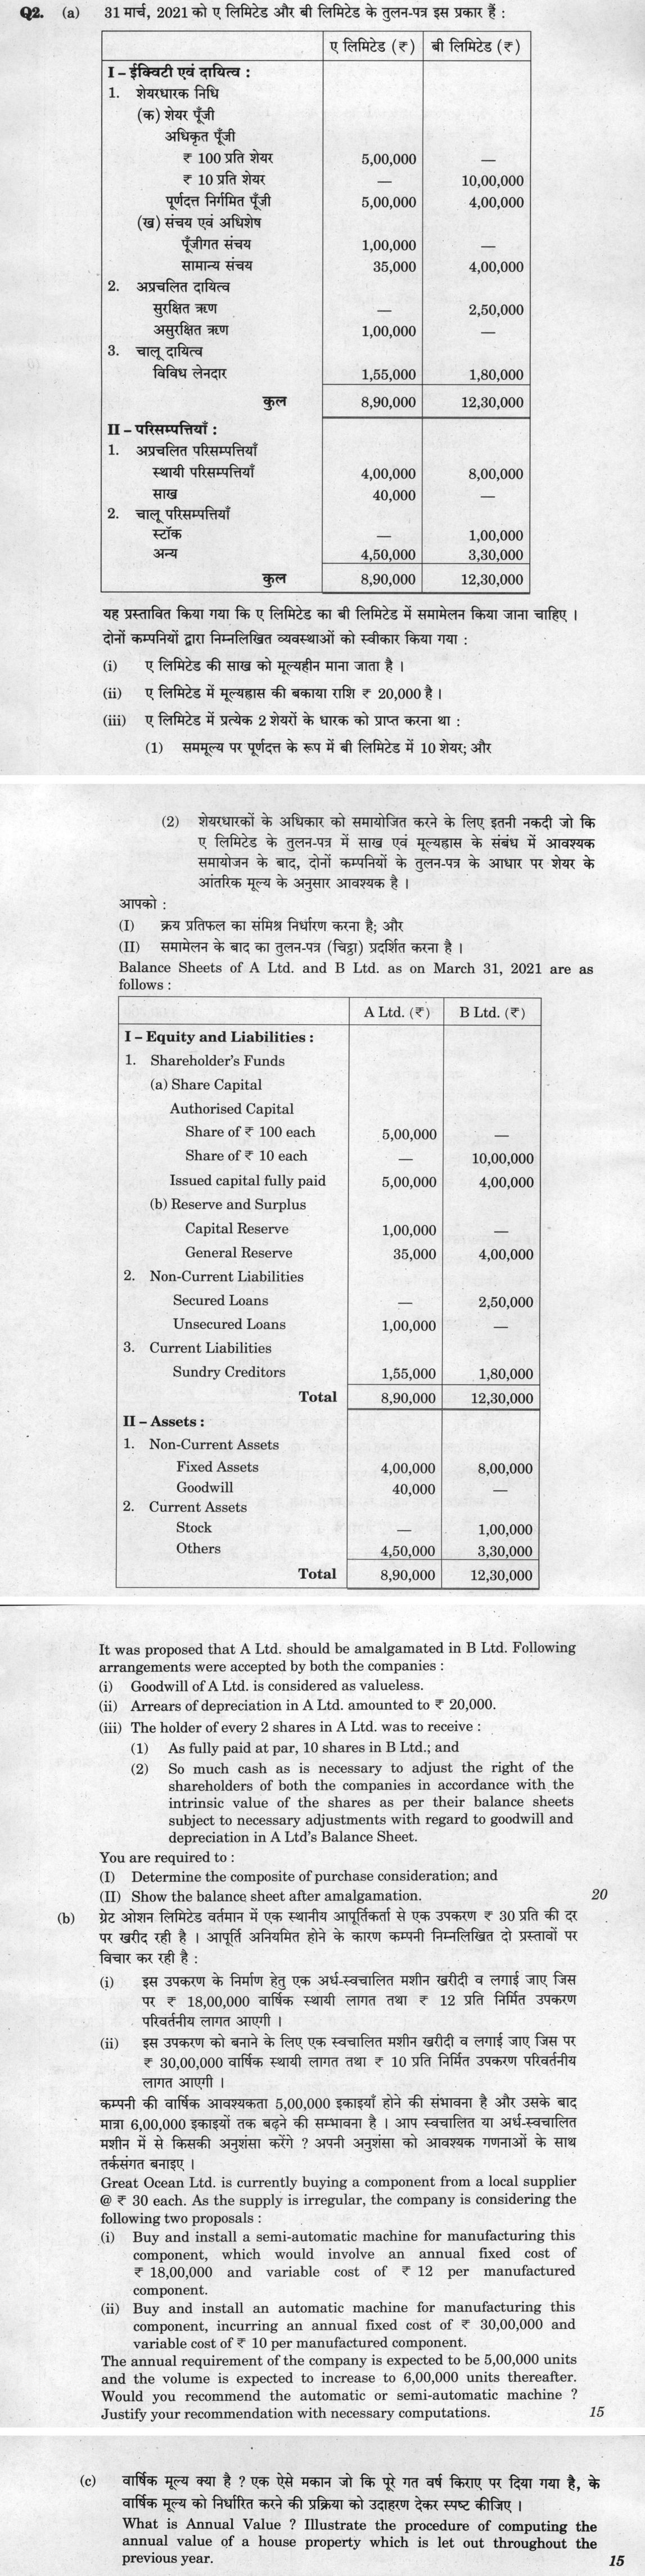
(a) Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows: | | A Ltd. (₹) | B Ltd. (₹) | |---|---|---| | **I –…
Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows:
| A Ltd. (₹) | B Ltd. (₹) | |
|---|---|---|
| **I – Equity and Liabilities:** | ||
| 1. Shareholder's Funds | ||
| (a) Share Capital | ||
| Authorised Capital | ||
| Share of ₹ 100 each | 5,00,000 | — |
| Share of ₹ 10 each | — | 10,00,000 |
| Issued capital fully paid | 5,00,000 | 4,00,000 |
| (b) Reserve and Surplus | ||
| Capital Reserve | 1,00,000 | — |
| General Reserve | 35,000 | 4,00,000 |
| 2. Non-Current Liabilities | ||
| Secured Loans | — | 2,50,000 |
| Unsecured Loans | 1,00,000 | — |
| 3. Current Liabilities | ||
| Sundry Creditors | 1,55,000 | 1,80,000 |
| **Total** | **8,90,000** | **12,30,000** |
| **II – Assets:** | ||
| 1. Non-Current Assets | ||
| Fixed Assets | 4,00,000 | 8,00,000 |
| Goodwill | 40,000 | — |
| 2. Current Assets | ||
| Stock | — | 1,00,000 |
| Others | 4,50,000 | 3,30,000 |
| **Total** | **8,90,000** | **12,30,000** |
It was proposed that A Ltd. should be amalgamated in B Ltd. Following arrangements were accepted by both the companies: Goodwill of A Ltd. is considered as valueless.
Arrears of depreciation in A Ltd. amounted to ₹ 20,000.
The holder of every 2 shares in A Ltd. was to receive: (1) As fully paid at par, 10 shares in B Ltd.; and (2) So much cash as is necessary to adjust the right of the shareholders of both the companies in accordance with the intrinsic value of the shares as per their balance sheets subject to necessary adjustments with regard to goodwill and depreciation in A Ltd.'s Balance Sheet.
You are required to: (I) Determine the composite of purchase consideration; and (II) Show the balance sheet after amalgamation. 20 marks
Great Ocean Ltd. is currently buying a component from a local supplier @ ₹ 30 each. As the supply is irregular, the company is considering the following two proposals: Buy and install a semi-automatic machine for manufacturing this component, which would involve an annual fixed cost of ₹ 18,00,000 and variable cost of ₹ 12 per manufactured component.
Buy and install an automatic machine for manufacturing this component, incurring an annual fixed cost of ₹ 30,00,000 and variable cost of ₹ 10 per manufactured component. The annual requirement of the company is expected to be 5,00,000 units and the volume is expected to increase to 6,00,000 units thereafter. Would you recommend the automatic or semi-automatic machine? Justify your recommendation with necessary computations. 15 marks
What is Annual Value? Illustrate the procedure of computing the annual value of a house property which is let out throughout the previous year. 15 marks
हिंदी में प्रश्न पढ़ें
31 मार्च, 2021 को ए लिमिटेड और बी लिमिटेड के तुलन-पत्र इस प्रकार हैं:
| ए लिमिटेड (₹) | बी लिमिटेड (₹) | |
|---|---|---|
| **I – इक्विटी एवं दायित्व:** | ||
| 1. शेयरधारक निधि | ||
| (क) शेयर पूँजी | ||
| अधिकृत पूँजी | ||
| ₹ 100 प्रति शेयर | 5,00,000 | — |
| ₹ 10 प्रति शेयर | — | 10,00,000 |
| पूर्णतः निर्गमित पूँजी | 5,00,000 | 4,00,000 |
| (ख) संचय एवं अधिशेष | ||
| पूँजीगत संचय | 1,00,000 | — |
| सामान्य संचय | 35,000 | 4,00,000 |
| 2. अचलित दायित्व | ||
| सुरक्षित ऋण | — | 2,50,000 |
| असुरक्षित ऋण | 1,00,000 | — |
| 3. चालू दायित्व | ||
| विविध लेनदार | 1,55,000 | 1,80,000 |
| **कुल** | **8,90,000** | **12,30,000** |
| **II – परिसम्पत्तियाँ:** | ||
| 1. अचलित परिसम्पत्तियाँ | ||
| स्थायी परिसम्पत्तियाँ | 4,00,000 | 8,00,000 |
| साख | 40,000 | — |
| 2. चालू परिसम्पत्तियाँ | ||
| स्टॉक | — | 1,00,000 |
| अन्य | 4,50,000 | 3,30,000 |
| **कुल** | **8,90,000** | **12,30,000** |
यह प्रस्तावित किया गया कि ए लिमिटेड का बी लिमिटेड में सममेलन किया जाना चाहिए। दोनों कंपनियों द्वारा निम्नलिखित व्यवस्थाओं को स्वीकार किया गया: ए लिमिटेड की साख को मूल्यहीन माना जाता है।
ए लिमिटेड में मूल्यह्रास की बकाया राशि ₹ 20,000 है।
ए लिमिटेड में प्रत्येक 2 शेयरों के धारक को प्राप्त करना था: (1) सममूल्य पर पूर्णतः के रूप में बी लिमिटेड में 10 शेयर; और (2) शेयरधारकों के अधिकार को समायोजित करने के लिए इतनी नकदी जो कि ए लिमिटेड के तुलन-पत्र में साख एवं मूल्यह्रास के संबंध में आवश्यक समायोजन के बाद, दोनों कंपनियों के तुलन-पत्र के आधार पर शेयर के आंतरिक मूल्य के अनुसार आवश्यक है।
आपको: (I) क्रय प्रतिफल का संमिश्र निर्धारण करना है; और (II) सममेलन के बाद का तुलन-पत्र (चित्र) प्रदर्शित करना है। (20 अंक)
ग्रेट ओशन लिमिटेड वर्तमान में एक स्थानीय आपूर्तिकर्ता से एक उपकरण ₹ 30 प्रति की दर पर खरीद रही है। आपूर्ति अनियमित होने के कारण कंपनी निम्नलिखित दो प्रस्तावों पर विचार कर रही है: इस उपकरण के निर्माण हेतु एक अर्ध-स्वचालित मशीन खरीदी व लगाई जाए जिस पर ₹ 18,00,000 वार्षिक स्थायी लागत तथा ₹ 12 प्रति निर्मित उपकरण परिवर्तनीय लागत आएगी।
इस उपकरण को बनाने के लिए एक स्वचालित मशीन खरीदी व लगाई जाए जिस पर ₹ 30,00,000 वार्षिक स्थायी लागत तथा ₹ 10 प्रति निर्मित उपकरण परिवर्तनीय लागत आएगी। कंपनी की वार्षिक आवश्यकता 5,00,000 इकाइयों होने की संभावना है और उसके बाद मात्रा 6,00,000 इकाइयों तक बढ़ने की संभावना है। आप स्वचालित या अर्ध-स्वचालित मशीन में से किसकी अनुशंसा करेंगे? अपनी अनुशंसा को आवश्यक गणनाओं के साथ तर्कसंगत बनाइए। (15 अंक)
वार्षिक मूल्य क्या है? एक ऐसे मकान जो कि पूरे गत वर्ष किए पर दिया गया है, के वार्षिक मूल्य को निर्धारित करने की प्रक्रिया को उदाहरण देकर स्पष्ट कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Amalgamation of A Ltd. in B Ltd.
1. Determination of Intrinsic Value (IV) of Shares
To determine the cash consideration, we must first calculate the intrinsic value of the shares of both companies, subject to the necessary adjustments.
A Ltd. (Adjusted):
- Net Assets: Total Assets (8,90,000) − Goodwill (40,000) − Arrears of Depreciation (20,000) − Outside Liabilities (Unsecured Loans 1,00,000 + Creditors 1,55,000) = ₹ 5,75,000.
- Intrinsic Value: ₹ 5,75,000 ÷ 5,000 shares = ₹ 115 per share.
B Ltd. (Unadjusted):
- Net Assets: Total Assets (12,30,000) − Outside Liabilities (Secured Loans 2,50,000 + Creditors 1,80,000) = ₹ 8,00,000.
- Intrinsic Value: ₹ 8,00,000 ÷ 40,000 shares = ₹ 20 per share.
2. Composite of Purchase Consideration
The terms state that for every 2 shares of A Ltd., the holder receives 10 shares of B Ltd. and cash to equalize the intrinsic value.
- Value of 2 A Ltd. Shares: 2 × ₹ 115 = ₹ 230.
- Value of 10 B Ltd. Shares: 10 × ₹ 20 = ₹ 200.
- Cash per Packet: ₹ 230 − ₹ 200 = ₹ 30.
Total Purchase Consideration:
- Number of Packets: 5,000 shares ÷ 2 = 2,500 packets.
- Shares of B Ltd. Issued: 2,500 × 10 = 25,000 shares (Value: ₹ 2,50,000).
- Cash Payment: 2,500 × ₹ 30 = ₹ 75,000.
- Total Purchase Consideration: ₹ 2,50,000 + ₹ 75,000 = ₹ 3,25,000.
3. Balance Sheet of B Ltd. after Amalgamation
Equity and Liabilities
- Share capital, 65,000 shares of ₹10 each (40,000 + 25,000): ₹6,50,000
- Reserves and surplus: General reserve (B Ltd.) ₹4,00,000, Capital reserve (5,75,000 − 3,25,000) ₹2,50,000
- Non-current liabilities: Secured loans (B Ltd.) ₹2,50,000, Unsecured loans (A Ltd.) ₹1,00,000
- Current liabilities: Sundry creditors (1,55,000 + 1,80,000) ₹3,35,000
- Total ₹19,85,000
Assets
- Non-current assets: Fixed assets (3,80,000 + 8,00,000) ₹11,80,000
- Current assets: Stock ₹1,00,000, Other current assets (7,80,000 − 75,000 cash paid) ₹7,05,000
- Total ₹19,85,000
(b) Choice between the two machines
To determine the most cost-effective machine, we must compare the total annual costs (Fixed + Variable) for both proposals at the projected volumes of 5,00,000 and 6,00,000 units.
Cost Analysis:
- Semi-Automatic Machine: Fixed Cost = ₹ 18,00,000; Variable Cost = ₹ 12/unit.
- Automatic Machine: Fixed Cost = ₹ 30,00,000; Variable Cost = ₹ 10/unit.
Comparison:
- At 5,00,000 units: semi-automatic 18,00,000 + 5,00,000 × 12 = ₹78,00,000, automatic 30,00,000 + 5,00,000 × 10 = ₹80,00,000
- At 6,00,000 units: semi-automatic 18,00,000 + 6,00,000 × 12 = ₹90,00,000, automatic 30,00,000 + 6,00,000 × 10 = ₹90,00,000
Justification and Recommendation: The indifference point, where the costs of both machines are equal, is calculated as: (30,00,000 − 18,00,000) / (12 − 10) = 6,00,000 units.
At the current expected requirement of 5,00,000 units, the semi-automatic machine is cheaper by ₹ 2,00,000. At the increased volume of 6,00,000 units, both machines incur an identical cost of ₹ 90,00,000. Therefore, I recommend the semi-automatic machine. It is more economical at the current volume and remains cost-neutral at the projected increase. The automatic machine would only be superior if the volume were to exceed 6,00,000 units. Furthermore, both options are significantly cheaper than buying the component from the supplier at ₹ 30 each (which would cost ₹ 1,50,00,000 for 5,00,000 units).
(c) Annual value of a let-out house property
Definition: Annual Value is the statutory basis for computing the income from house property under the Income Tax Act. It represents the potential gross income of the property, adjusted for municipal taxes paid by the owner.
Procedure for a Let-Out Property:
- Gross Annual Value (GAV): For a property let out throughout the year, the GAV is the higher of:
- Expected Rent: The higher of the reasonable rent or municipal value, subject to a cap of the Standard Rent (if applicable).
- Actual Rent Received or Receivable: The rent actually collected or due.
- Deduction of Municipal Taxes: From the GAV, we deduct the municipal taxes actually paid by the owner during the previous year. There is no percentage ceiling on this deduction.
- Net Annual Value (NAV): The result after the municipal tax deduction is the Net Annual Value.
Numerical Illustration: Assume a house is let out throughout the year with the following details:
- Expected Rent: ₹ 1,20,000
- Actual Rent Received: ₹ 1,32,000
- Municipal Taxes paid by owner: ₹ 12,000
Computation:
- Step 1: Determine GAV Higher of Expected Rent (₹ 1,20,000) and Actual Rent (₹ 1,32,000) = ₹ 1,32,000.
- Step 2: Deduct Municipal Taxes Municipal taxes paid by the owner = ₹ 12,000. The full amount actually paid by the owner is deductible.
- Step 3: Calculate NAV GAV (₹ 1,32,000) − Municipal Taxes (₹ 12,000) = ₹ 1,20,000.
The Net Annual Value for this property is ₹ 1,20,000, which is then used to apply the standard deduction of 30% and interest on borrowed capital (section 24). The Income-tax Act, 2025, in force from 1 April 2026, keeps this annual-value method under renumbered provisions.
How this answer will be evaluated
Framework: Commerce Accountancy, Paper 1
What earns full marks: Complete workings, correct formats, precise statutory references, and clear justifications.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Determine purchase consideration and show post-amalgamation balance sheet. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Adjust A Ltd. assets for ₹40,000 goodwill and ₹20,000 depreciation
- Calculate intrinsic value of A Ltd. shares
- Determine cash payment to equalize intrinsic values
- Present consolidated balance sheet in prescribed format
Loses marks
- Final figures without working notes
- Incorrect adjustment of arrears of depreciation
- Wrong statement format for balance sheet
Earns more
- Working notes for share exchange ratio
- Correct treatment of capital reserve
- Accurate calculation of cash consideration
Extra mark
- Cites AS 14 (amalgamation in the nature of purchase) or ss. 230–232 of the Companies Act, 2013
- (b) Recommend machine based on cost analysis for 5L and 6L units. 15 marks
justify— claim → 3-4 reasons → evidence → conclusion
Must cover
- Calculate total cost for semi-automatic at 5,00,000 units
- Calculate total cost for automatic at 5,00,000 units
- Calculate total cost for both at 6,00,000 units
- Provide clear recommendation with justification
Loses marks
- Missing calculation for 6,00,000 unit volume
- Recommendation without cost comparison
- Arithmetic errors in cost computation
Earns more
- Comparison table of costs
- Break-even analysis between machines
- Consideration of volume increase
Extra mark
- Graphical representation of cost curves
- (c) Define Annual Value and illustrate computation for let-out property. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Define Annual Value as per Income Tax Act
- Explain Gross Annual Value calculation
- Deduct municipal taxes actually paid by the owner during the year (no percentage ceiling)
- Illustrate with numerical example
Loses marks
- Definition without computation illustration
- Omission of Municipal Tax deduction
- Confusion between Gross and Net Annual Value
Earns more
- Mention of standard rent concept
- Explanation of vacant period adjustment
- Clear step-by-step computation format
Extra mark
- Cites section 23 of the Income-tax Act, 1961 (and notes the Income-tax Act, 2025 from 1 April 2026)
What "Compare" is asking you to do
Set the items against each other on named dimensions. In UPSC practice compare already carries both halves — likeness and difference — and where the stem names the dimensions, as in region, nature and climatic impact, those are the headings the examiner expects to see.
Structure that answers it
Dimensions named → both items on dimension 1 → dimension 2 → dimension 3 → where they converge and where they part
Where marks are lost
Two self-contained descriptive blocks with the comparison left for the reader to make. Marks here sit on the dimensions, so an answer that names none of them gives the examiner nothing to award.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q1 Answer the following questions in about 150 words each : (a) What are Sweat Equity Shares…
- Q2 (a) Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows: | | A Ltd. (…
- Q3 (a) X, an employee of a firm, furnished the following particulars of his income for the y…
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…