Paper I — Q3
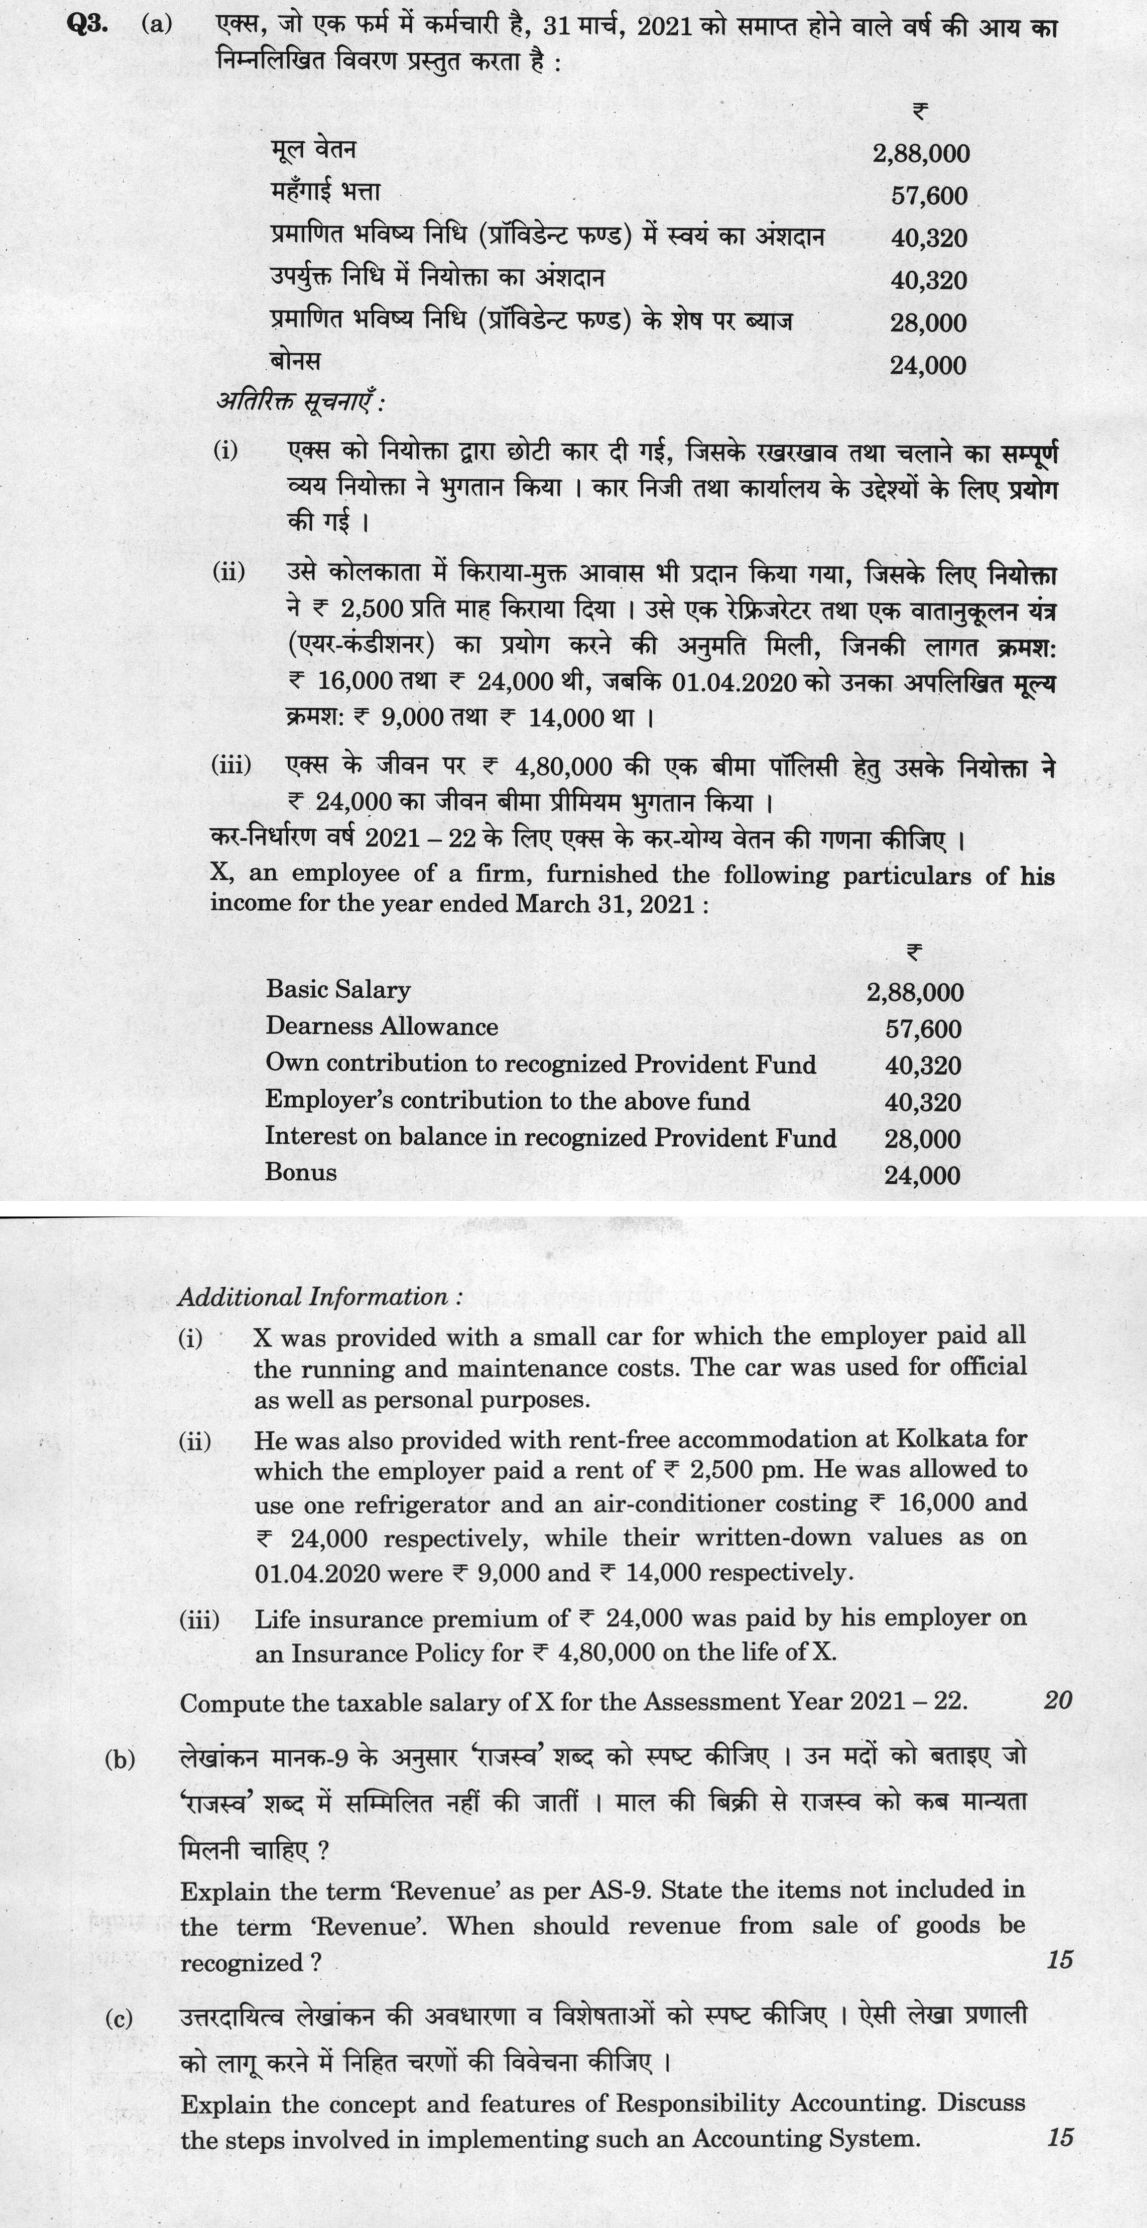
(a) X, an employee of a firm, furnished the following particulars of his income for the year ended March 31, 2021 : ₹ Basic…
X, an employee of a firm, furnished the following particulars of his income for the year ended March 31, 2021 :
₹
Basic Salary 2,88,000 Dearness Allowance 57,600 Own contribution to recognized Provident Fund 40,320 Employer's contribution to the above fund 40,320 Interest on balance in recognized Provident Fund 28,000 Bonus 24,000
Additional Information :
X was provided with a small car for which the employer paid all the running and maintenance costs. The car was used for official as well as personal purposes.
He was also provided with rent-free accommodation at Kolkata for which the employer paid a rent of ₹ 2,500 pm. He was allowed to use one refrigerator and an air-conditioner costing ₹ 16,000 and ₹ 24,000 respectively, while their written-down values as on 01.04.2020 were ₹ 9,000 and ₹ 14,000 respectively.
Life insurance premium of ₹ 24,000 was paid by his employer on an Insurance Policy for ₹ 4,80,000 on the life of X.
Compute the taxable salary of X for the Assessment Year 2021 – 22. 20 marks
Explain the term 'Revenue' as per AS-9. State the items not included in the term 'Revenue'. When should revenue from sale of goods be recognized ? 15 marks
Explain the concept and features of Responsibility Accounting. Discuss the steps involved in implementing such an Accounting System. 15 marks
हिंदी में प्रश्न पढ़ें
एक्स, जो एक फर्म में कर्मचारी है, 31 मार्च, 2021 को समाप्त होने वाले वर्ष की आय का निम्नलिखित विवरण प्रस्तुत करता है :
₹
मूल वेतन 2,88,000 महंगाई भत्ता 57,600 प्रमाणित भविष्य निधि (प्राविडेंट फण्ड) में स्वयं का अंशदान 40,320 उपर्युक्त निधि में नियोक्ता का अंशदान 40,320 प्रमाणित भविष्य निधि (प्राविडेंट फण्ड) के शेष पर ब्याज 28,000 बोनस 24,000
अतिरिक्त सूचनाएँ :
एक्स को नियोक्ता द्वारा छोटी कार दी गई, जिसके रखरखाव तथा चलाने का सम्पूर्ण व्यय नियोक्ता ने भुगतान किया। कार निजी तथा कार्यालय के उद्देश्यों के लिए प्रयोग की गई।
उसे कोलकाता में किराया-मुक्त आवास भी प्रदान किया गया, जिसके लिए नियोक्ता ने ₹ 2,500 प्रति माह किराया दिया। उसे एक रेफ्रिजरेटर तथा एक वातानुकूलन यंत्र (एयर-कंडीशनर) का प्रयोग करने की अनुमति मिली, जिनकी लागत क्रमशः: ₹ 16,000 तथा ₹ 24,000 थी, जबकि 01.04.2020 को उनका अपलिखित मूल्य क्रमशः: ₹ 9,000 तथा ₹ 14,000 था।
एक्स के जीवन पर ₹ 4,80,000 की एक बीमा पॉलिसी हेतु उसके नियोक्ता ने ₹ 24,000 का जीवन बीमा प्रीमियम भुगतान किया।
कर-निर्धारण वर्ष 2021 – 22 के लिए एक्स के कर-योग्य वेतन की गणना कीजिए। (20 अंक)
लेखांकन मानक-9 के अनुसार 'राजस्व' शब्द को स्पष्ट कीजिए। उन मदों को बताइए जो 'राजस्व' शब्द में सम्मिलित नहीं की जातीं। माल की बिक्री से राजस्व को कब मान्यता मिलनी चाहिए ? (15 अंक)
उत्तरदायित्व लेखांकन की अवधारणा व विशेषताओं को स्पष्ट कीजिए। ऐसी लेखा प्रणाली को लागू करने में निहित चरणों की विवेचना कीजिए। (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Table of income particulars for the year ended March 31, 2021: Basic Salary: 2,88,000 Dearness Allowance: 57,600 Own contribution to recognized Provident Fund: 40,320 Employer's contribution to the above fund: 40,320 Interest on balance in recognized Provident Fund: 28,000 Bonus: 24,000
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Computation of Taxable Salary of X for Assessment Year 2021 – 22
Assumptions: X opts for the normal (old) regime, because under s.115BAC as it stood for AY 2021-22 the standard deduction was not allowed, and DA forms part of salary for retirement benefits.
1. Gross Salary:
- Basic Salary: ₹ 2,88,000
- Dearness Allowance: ₹ 57,600
- Bonus: ₹ 24,000
- Total Gross Salary: ₹ 3,69,600
2. Perquisites:
- Small Car: Since the car is used for both official and personal purposes and the employer bears all running and maintenance costs, the value is fixed at ₹ 1,800 per month.
- Value = ₹ 1,800 × 12 = ₹ 21,600
- Rent-Free Accommodation (Kolkata): Kolkata is a metropolitan city. The perquisite is the lower of:
- (a) 15% of Salary (Basic + DA + Bonus) = 15% of ₹ 3,69,600 = ₹ 55,440
- (b) Actual Rent Paid = ₹ 2,500 × 12 = ₹ 30,000
- Value = ₹ 30,000
- Furniture: The value is 10% p.a. of the original cost of the furniture owned by the employer (Rule 3(1)).
- Cost of Refrigerator: ₹ 16,000
- Cost of Air-conditioner: ₹ 24,000
- Total Cost: ₹ 40,000
- Value = 10% of ₹ 40,000 = ₹ 4,000
- Life Insurance Premium: The premium of ₹ 24,000 paid by the employer on a policy of ₹ 4,80,000 on X's life is a taxable perquisite under Section 17(2)(v) of the Income Tax Act (X may claim deduction for it under Section 80C).
3. Provident Fund (PF):
- Employer’s Contribution: Taxable only if it exceeds 12% of the employee’s Basic + DA.
- 12% of (₹ 2,88,000 + ₹ 57,600) = 12% of ₹ 3,45,600 = ₹ 41,472.
- Since the actual contribution (₹ 40,320) is less than ₹ 41,472, it is fully exempt.
- Interest on PF: The interest of ₹ 28,000 credited to the recognised PF is exempt as it is taken to be credited at a rate not exceeding 9.5% p.a. (only interest above 9.5% is taxable).
- Taxable Interest = Nil
4. Statement of Taxable Salary (AY 2021-22):
- Basic Salary + DA + Bonus: ₹ 3,69,600
- Perquisite, car: ₹ 21,600
- Perquisite, rent-free accommodation: ₹ 30,000
- Perquisite, furniture: ₹ 4,000
- Perquisite, life insurance premium: ₹ 24,000
- Employer PF contribution and PF interest: exempt (Nil)
- Gross Salary: ₹ 4,49,200
- Less: Standard Deduction u/s 16(ia): ₹ 50,000
- Taxable Salary: ₹ 3,99,200
Own contribution of ₹ 40,320 and the LIC premium of ₹ 24,000 do not reduce salary income, they qualify under s.80C (overall limit ₹ 1,50,000) while computing total income. These figures follow the Income-tax Act, 1961, which governs AY 2021-22. The Income-tax Act, 2025 applies from 1.4.2026 and does not alter this computation.
(b) Revenue as per AS-9
Definition of Revenue: Under AS-9, Revenue is the gross inflow of cash, receivables or other consideration arising in the course of the ordinary activities of an enterprise from the sale of goods, the rendering of services, and the use by others of enterprise resources yielding interest, royalties and dividends. It is measured by the charges made to customers for goods supplied and services rendered. In an agency relationship, revenue is only the commission, not the gross amount collected.
Items Not Included in Revenue (AS-9):
- Realised gains from disposal of, and unrealised gains from holding, non-current assets, such as appreciation in the value of fixed assets.
- Unrealised holding gains from changes in the market prices of current assets.
- Realised or unrealised gains from translation of foreign currency accounts.
- Realised gains from discharge of an obligation at less than its carrying amount, and unrealised gains from restatement of the carrying amount of an obligation.
- Amounts collected on behalf of third parties, such as GST or other indirect taxes, and the gross collections of an agent.
- Items outside the scope of AS-9: revenue from construction contracts (AS-7), hire-purchase and lease agreements (AS-19), government grants (AS-12) and revenue of insurance companies from insurance contracts.
Recognition of Revenue from Sale of Goods (paras 10 and 11): Performance is regarded as achieved, and revenue is recognised, when both conditions are met:
- The seller has transferred to the buyer the property in the goods for a price, or all significant risks and rewards of ownership have been transferred, and the seller retains no effective control of the goods to a degree usually associated with ownership.
- No significant uncertainty exists regarding the amount of consideration that will be derived from the sale.
In addition, at the time of performance it must not be unreasonable to expect ultimate collection. If such uncertainty exists, recognition is postponed until it is reasonably certain that collection will be made.
(c) Responsibility Accounting
Concept and Features: Responsibility Accounting is a management accounting system that organizes an enterprise into distinct "responsibility centers." It is based on the principle that performance should be evaluated based on factors that a manager can actually control. The primary features include:
- Decentralization: It supports a decentralized structure where authority is delegated to lower levels of management.
- Responsibility Centers: The organization is divided into Cost Centers, Revenue Centers, Profit Centers, and Investment Centers.
- Controllability: Only "controllable costs" are charged to a manager. Uncontrollable costs (like allocated overheads) are excluded from performance evaluation.
- Performance Evaluation: It provides a framework for comparing actual performance against predetermined budgets to identify variances.
Steps in Implementation:
- Organizational Mapping: The first step is to define the organizational structure and identify the specific responsibility centers (e.g., a production department as a cost center).
- Identification of Controllable Items: For each center, the manager must identify which revenues, costs, or investments they have the authority to influence.
- Budgeting: Standard budgets or performance targets must be set for each center. These budgets serve as the "benchmarks" for evaluation.
- Data Collection and Reporting: Actual financial data must be collected and reported periodically (monthly or quarterly) for each center.
- Variance Analysis: The actual results are compared with the budgeted figures. Significant variances are investigated to determine if they were due to managerial efficiency or external factors.
- Feedback and Action: The results are used to provide feedback to managers, facilitating corrective actions and informing future decision-making.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Accurate calculations with workings; precise AS-9 definitions; clear distinction of responsibility centers.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute the taxable salary of X for AY 2021-22. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Car perquisite at ₹1,800 pm (small car, mixed use, employer bears running costs) = ₹21,600
- Rent-free accommodation (employer-leased): lower of actual rent ₹30,000 and 15% of salary ₹55,440 = ₹30,000
- Furniture perquisite at 10% of original cost (₹40,000) = ₹4,000, and LIC premium ₹24,000 taxable u/s 17(2)(v)
- Employer PF ₹40,320 within 12% of Basic+DA (₹41,472) so exempt, PF interest exempt, standard deduction ₹50,000, taxable salary ₹3,99,200
Loses marks
- Final figure without showing working notes
- Applying population-based percentage of salary instead of lower of actual rent and 15% for leased accommodation
- Failure to distinguish exempt vs taxable PF components
Earns more
- Treats life insurance premium paid by employer as a taxable perquisite (80C relief is outside salary)
- Correctly treat interest on PF as exempt
- Properly format the salary computation statement
Extra mark
- Cite specific Income Tax Act sections for exemptions
- (b) Explain 'Revenue' per AS-9, exclusions, and recognition criteria. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Define revenue as per AS-9 (gross inflow of economic benefits)
- Items excluded: gains on disposal or holding of non-current assets, unrealised holding gains, forex translation gains, gains on discharge of obligations, amounts collected for third parties
- Sale of goods: transfer of property or significant risks and rewards with no effective control retained, no significant uncertainty on consideration, collection reasonably expected
Loses marks
- Confusing revenue with capital receipts
- Omitting the specific conditions for sale of goods
Earns more
- Mentions that in agency only commission is revenue
- Reference to specific AS-9 paragraphs
Extra mark
- Comparison with Ind AS 115 (Revenue from Contracts)
- (c) Explain Responsibility Accounting concept, features, and implementation steps. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Define Responsibility Accounting (accounting for responsibility centers)
- List key features (e.g., decentralization, performance evaluation)
- Outline steps for implementing the system
Loses marks
- Treating it as a mere bookkeeping system
- Failing to link features to implementation steps
Earns more
- Distinguish between cost, profit, and investment centers
- Mention the role of budgeting in the system
Extra mark
- Example of a responsibility center structure
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q1 Answer the following questions in about 150 words each : (a) What are Sweat Equity Shares…
- Q2 (a) Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows: | | A Ltd. (…
- Q3 (a) X, an employee of a firm, furnished the following particulars of his income for the y…
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…