Paper I — Q4
(a) The following details have been extracted from the cost records of a company : Material : 5 lbs @ ₹ 5 – ₹ 25 Labour : 4 Hrs…
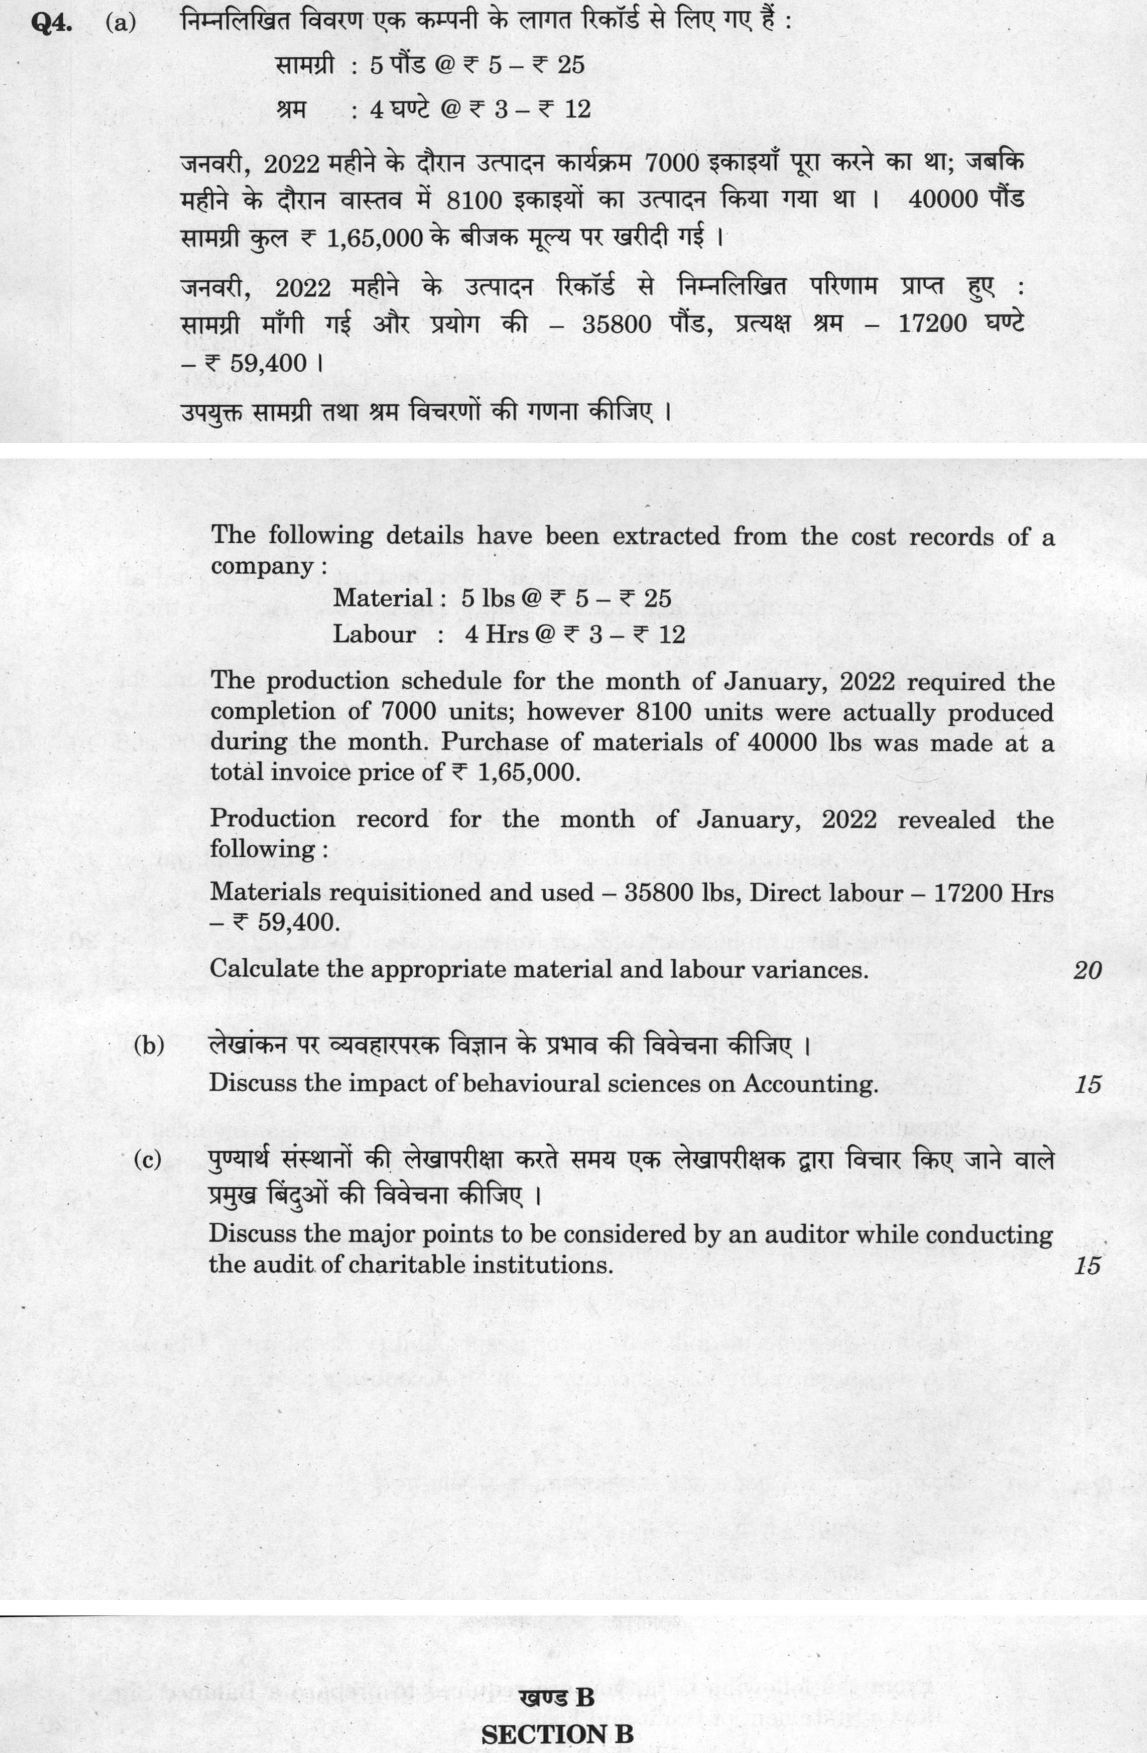
The following details have been extracted from the cost records of a company :
Material : 5 lbs @ ₹ 5 – ₹ 25 Labour : 4 Hrs @ ₹ 3 – ₹ 12
The production schedule for the month of January, 2022 required the completion of 7000 units; however 8100 units were actually produced during the month. Purchase of materials of 40000 lbs was made at a total invoice price of ₹ 1,65,000.
Production record for the month of January, 2022 revealed the following :
Materials requisitioned and used – 35800 lbs, Direct labour – 17200 Hrs – ₹ 59,400.
Calculate the appropriate material and labour variances. 20 marks
Discuss the impact of behavioural sciences on Accounting. 15 marks
Discuss the major points to be considered by an auditor while conducting the audit of charitable institutions. 15 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित विवरण एक कंपनी के लागत रिकॉर्ड से लिए गए हैं :
सामग्री : 5 पौंड @ ₹ 5 – ₹ 25 श्रम : 4 घंटे @ ₹ 3 – ₹ 12
जनवरी, 2022 महीने के दौरान उत्पादन कार्यक्रम 7000 इकाइयाँ पूरा करने का था; जबकि महीने के दौरान वास्तव में 8100 इकाइयों का उत्पादन किया गया था। 40000 पौंड सामग्री कुल ₹ 1,65,000 के बीजक मूल्य पर खरीदी गई।
जनवरी, 2022 महीने के उत्पादन रिकॉर्ड से निम्नलिखित परिणाम प्राप्त हुए : सामग्री माँगी गई और प्रयोग की – 35800 पौंड, प्रत्यक्ष श्रम – 17200 घंटे – ₹ 59,400।
उपर्युक्त सामग्री तथा श्रम विचरणों की गणना कीजिए। (20 अंक)
लेखांकन पर व्यवहारपरक विज्ञान के प्रभाव की विवेचना कीजिए। (15 अंक)
पुण्यार्थ संस्थानों की लेखापरीक्षा करते समय एक लेखापरीक्षक द्वारा विचार किए जाने वाले प्रमुख बिंदुओं की विवेचना कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Material and Labour Variances Variances are measured against standard allowed for actual output. Actual output = 8,100 units. F = favourable, A = adverse.
Standard data:
- Material: 5 lbs @ ₹5 = ₹25 per unit.
- Labour: 4 hrs @ ₹3 = ₹12 per unit.
- Standard material allowed = 8,100 × 5 = 40,500 lbs.
- Standard hours allowed = 8,100 × 4 = 32,400 hrs.
- Actual material price = ₹1,65,000 ÷ 40,000 lbs = ₹33/8 = ₹4.125 per lb.
- Actual material purchased = 40,000 lbs; actual material used = 35,800 lbs.
- Actual labour hours = 17,200 hrs; actual labour cost = ₹59,400; actual labour rate = ₹59,400 ÷ 17,200 = ₹297/86 = ₹3.4535 per hr.
Material variances:
- Material cost variance = (Standard quantity for actual output × Standard price) – (Actual quantity used × Actual price) = (40,500 × ₹5) – (35,800 × ₹33/8) = ₹2,02,500 – ₹1,47,675 = ₹54,825 F.
- Material price variance (on actual quantity purchased) = Actual quantity purchased × (Standard price – Actual price) = 40,000 × (₹5 – ₹33/8) = 40,000 × ₹7/8 = ₹35,000 F.
- Material usage variance = Standard price × (Standard quantity – Actual quantity used) = ₹5 × (40,500 – 35,800) = ₹5 × 4,700 = ₹23,500 F.
- Reconciliation: Material price variance on purchases + Material usage variance = ₹35,000 F + ₹23,500 F = ₹58,500 F. This exceeds material cost variance by ₹3,675 F, which is the price variance on closing inventory: (40,000 – 35,800) × ₹7/8 = 4,200 × ₹7/8 = ₹3,675 F. If price variance is required on quantity used, it is 35,800 × ₹7/8 = ₹31,325 F, and then ₹31,325 F + ₹23,500 F = ₹54,825 F.
Labour variances:
- Labour cost variance = (Standard hours for actual output × Standard rate) – Actual labour cost = (32,400 × ₹3) – ₹59,400 = ₹97,200 – ₹59,400 = ₹37,800 F.
- Labour rate variance = Actual hours × (Standard rate – Actual rate) = 17,200 × (₹3 – ₹297/86) = ₹51,600 – ₹59,400 = ₹7,800 A.
- Labour efficiency variance = Standard rate × (Standard hours – Actual hours) = ₹3 × (32,400 – 17,200) = ₹3 × 15,200 = ₹45,600 F.
- Check: ₹45,600 F – ₹7,800 A = ₹37,800 F.
(b) Impact of Behavioural Sciences on Accounting Behavioural sciences study how human cognition, motivation, group behaviour and biases affect decisions. Their impact on accounting is wide-ranging:
- Budgeting: participative budgeting can improve commitment and information flow, but may create budgetary slack and game-playing. Imposed budgets may strengthen control but reduce motivation.
- Performance evaluation: accounting measures such as ROI, residual income, EVA and variances influence managerial behaviour. If used mechanically, they can cause short-termism, dysfunctional cost-cutting, transfer-pricing conflicts and earnings manipulation.
- Financial reporting: preparers and auditors are subject to anchoring, overconfidence, confirmation bias, availability bias, framing and escalation of commitment. This affects provisions, impairment, going-concern assessment and fraud risk judgment.
- Management control: agency theory, goal congruence and expectancy theory explain why controls must balance monitoring with trust, autonomy and fairness. The balanced scorecard and non-financial measures reduce excessive focus on profit.
- Ethical culture: tone at the top, incentives, whistle-blower protection and organisational norms shape accounting choices and compliance.
- Human resource accounting and responsibility accounting draw on the same insight, that people respond to how they are measured (Argyris, 1952, on budget pressure, Hopwood, 1972, on styles of using accounting data).
(c) Audit of Charitable Institutions
- Governing documents: examine trust deed, society registration, memorandum and articles, rules, bye-laws and amendments. Confirm activities are within the charitable objects.
- Legal and tax compliance: verify registration under the applicable Act, Income-tax registration under s.12AB (re-registration regime from 1.4.2021), approval under 80G, FCRA registration if foreign contributions are received (FCRA account at SBI New Delhi Main Branch and administrative expenses within 20% after the 2020 amendment), and GST/TDS compliance. Under the Income-tax Act, 2025, applicable from 1.4.2026, these provisions are carried into a consolidated scheme for registered non-profit organisations, so the auditor checks the corresponding new provisions.
- Receipts and funds: check donations, subscriptions, grants, corpus, restricted and unrestricted funds, foreign contributions, anonymous cash donations, donation receipts and bank deposits. Verify application of 85% of income, accumulation under Section 11(2) with Form 10, investments in modes under Section 11(5), and tax on anonymous donations under Section 115BBC.
- Expenditure: vouch payments for charitable objects, salaries, administration, projects and capital expenditure. Ensure no undue benefit to trustees or related parties; review minutes for approvals.
- Internal control: review cash handling, receipt books, bank reconciliation, segregation of duties, asset register, inventory of relief material and controls over fund-raising.
- Investments and assets: verify ownership, title, valuation and whether investments are permitted.
- Financial statements and reporting: check fund-wise disclosure, comparative figures, audit report wording, Form 10B or 10BB (as revised from AY 2023-24), FCRA return FC-4 and statutory filings.
- Fraud risk: remain alert to diversion of funds, bogus vouchers, inflated bills, related-party transactions and non-charitable use of funds.
- Minutes and representations: review trustees’ meetings, project reports and obtain written representations on compliance and related-party transactions.
How this answer will be evaluated
Framework: Cost Accounting Variance Analysis
What earns full marks: Accurate calculations with workings; comprehensive discussion with examples; specific audit points for charities.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute material and labour variances using standard cost data. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Material price variance ₹35,000 F on 40,000 lbs purchased (or ₹31,325 F on 35,800 lbs used), actual price ₹4.125
- Material usage variance ₹23,500 F (standard 40,500 lbs vs 35,800 lbs), material cost variance ₹54,825 F
- Labour rate variance ₹7,800 A (17,200 hrs × ₹3 = ₹51,600 vs ₹59,400)
- Labour efficiency variance ₹45,600 F (32,400 vs 17,200 hrs), labour cost variance ₹37,800 F
Loses marks
- Using 7000 units for standard quantity
- Omitting working notes for actual rates
- Final figures without calculation steps
Earns more
- Correct standard quantity for actual output (8100 units)
- Actual price per unit derived from invoice
- Actual rate per hour derived from total wages
- Clear statement of each variance with F/A and reconciliation, including treatment of price variance on 4,200 lbs closing stock
Extra mark
- Explicit statement of favourable/adverse nature
- Reconciliation of total variance
- (b) Explain the impact of behavioural sciences on accounting. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Definition of behavioural sciences in accounting context
- Impact on management accounting and decision making
- Influence on human behaviour and motivation
- Application in budgeting and performance evaluation
Loses marks
- Generic discussion without accounting link
- Ignoring the 'impact' aspect
- No structure or flow in argument
Earns more
- Reference to Maslow's hierarchy or Herzberg's theory
- Discussion of participative budgeting
- Impact on audit and internal control
- Balanced view of limitations
Extra mark
- Specific example of behavioural accounting application
- Reference to a specific study or author
- (c) List major points for auditing charitable institutions. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Verification of trust deed and compliance
- Audit of income and expenditure accounts
- Verification of assets and liabilities
- Tax and FCRA compliance: 12AB registration, 80G, 85% application, Form 10B/10BB, FCRA account and returns
Loses marks
- Generic audit points not specific to charities
- Ignoring the 'charitable' nature of the institution
- No mention of compliance or legal aspects
Earns more
- Discussion of fund-specific audits
- Verification of donations and grants
- Review of internal controls
- Reporting on restricted funds
Extra mark
- Reference to specific audit standards for NGOs
- Mention of specific legal provisions
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q1 Answer the following questions in about 150 words each : (a) What are Sweat Equity Shares…
- Q2 (a) Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows: | | A Ltd. (…
- Q3 (a) X, an employee of a firm, furnished the following particulars of his income for the y…
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…
- Q7 (a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment…