Paper I — Q7
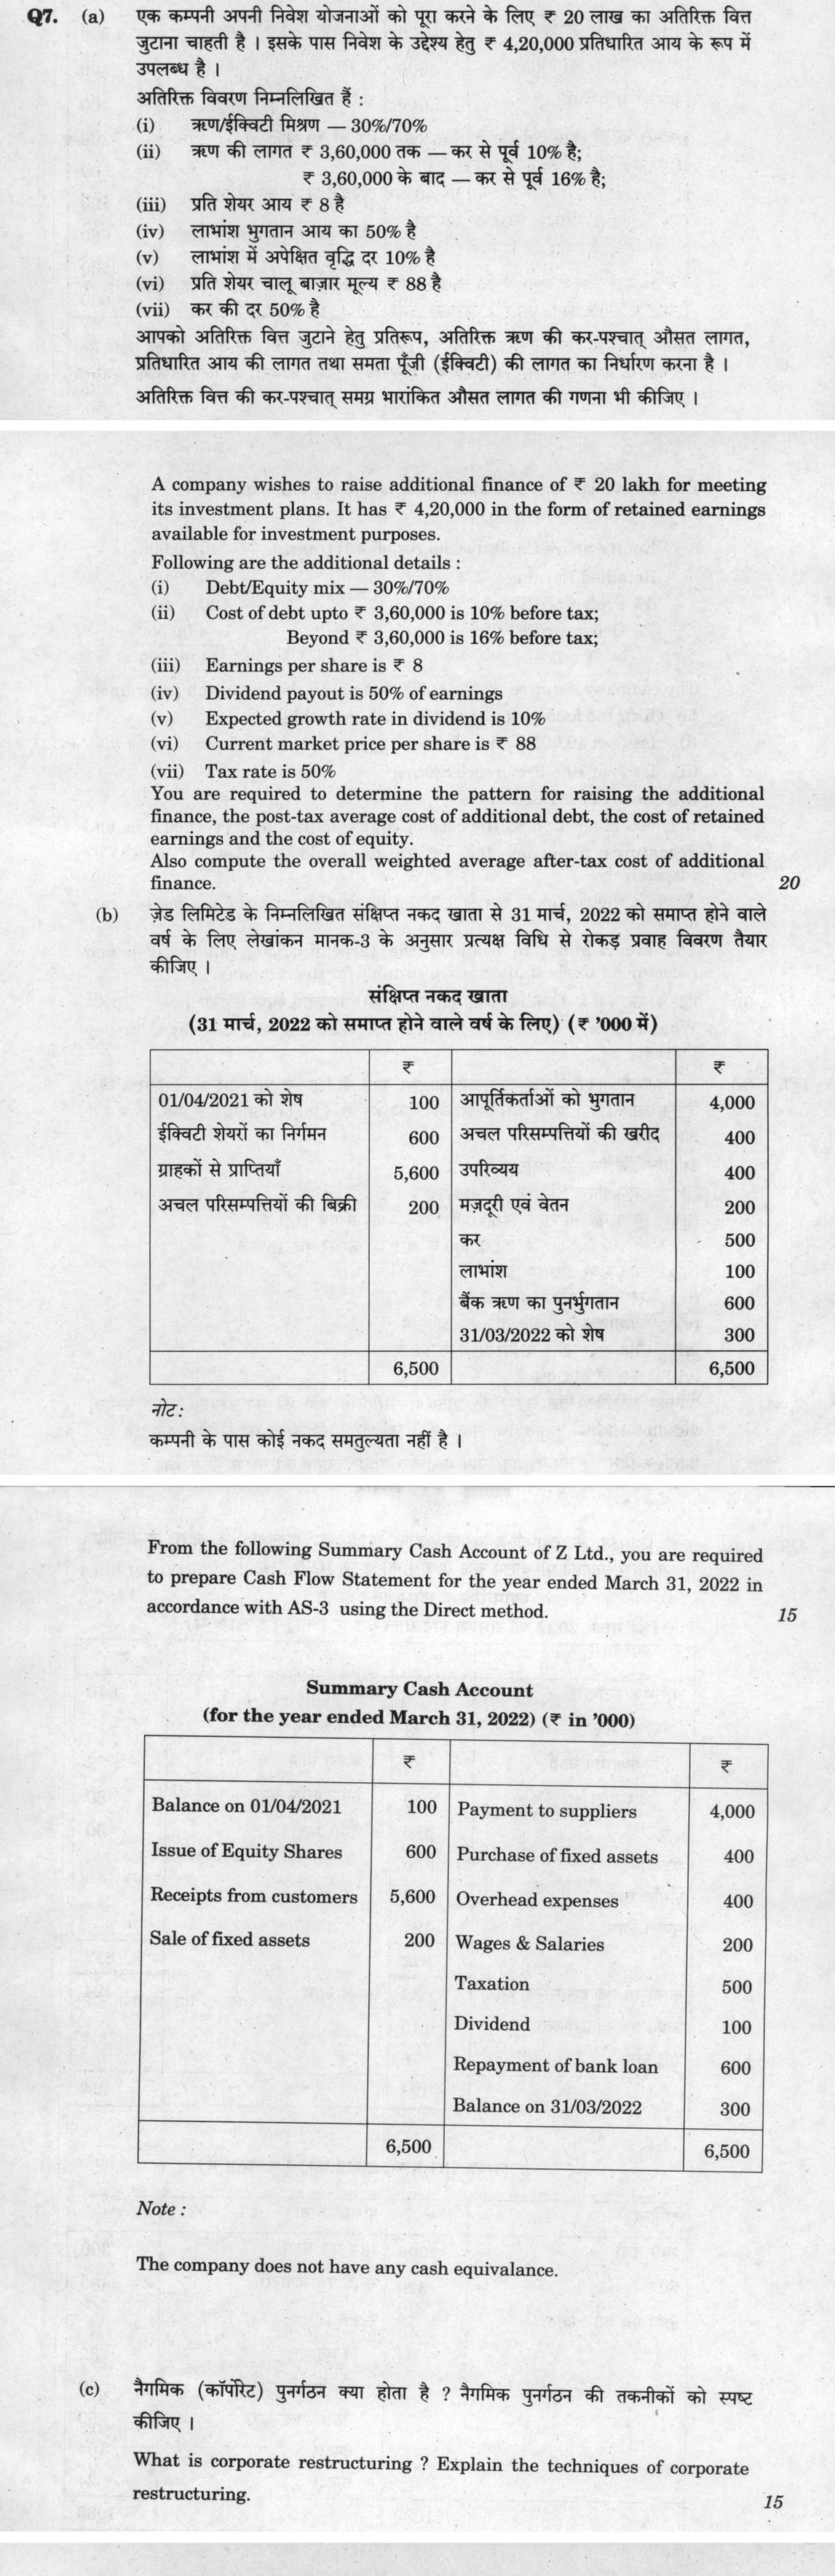
(a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment plans. It has ₹ 4,20,000 in the form of…
A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment plans. It has ₹ 4,20,000 in the form of retained earnings available for investment purposes.
Following are the additional details :
Debt/Equity mix — 30%/70%
Cost of debt upto ₹ 3,60,000 is 10% before tax; Beyond ₹ 3,60,000 is 16% before tax;
Earnings per share is ₹ 8
Dividend payout is 50% of earnings
Expected growth rate in dividend is 10%
Current market price per share is ₹ 88
Tax rate is 50%
You are required to determine the pattern for raising the additional finance, the post-tax average cost of additional debt, the cost of retained earnings and the cost of equity.
Also compute the overall weighted average after-tax cost of additional finance. 20 marks
From the following Summary Cash Account of Z Ltd., you are required to prepare Cash Flow Statement for the year ended March 31, 2022 in accordance with AS-3 using the Direct method. 15 marks
Summary Cash Account (for the year ended March 31, 2022) (₹ in '000)
Balance on 01/04/2021 100 Payment to suppliers 4,000 Issue of Equity Shares 600 Purchase of fixed assets 400 Receipts from customers 5,600 Overhead expenses 400 Sale of fixed assets 200 Wages & Salaries 200 Taxation 500 Dividend 100 Repayment of bank loan 600 Balance on 31/03/2022 300 6,500 6,500
Note :
The company does not have any cash equivalence.
What is corporate restructuring ? Explain the techniques of corporate restructuring. 15 marks
हिंदी में प्रश्न पढ़ें
एक कम्पनी अपनी निवेश योजनाओं को पूरा करने के लिए ₹ 20 लाख का अतिरिक्त वित्त जुटाना चाहती है । इसके पास निवेश के उद्देश्य हेतु ₹ 4,20,000 प्रतिधारित आय के रूप में उपलब्ध है ।
अतिरिक्त विवरण निम्नलिखित हैं :
ऋण/इक्विटी मिश्रण — 30%/70%
ऋण की लागत ₹ 3,60,000 तक — कर से पूर्व 10% है; ₹ 3,60,000 के बाद — कर से पूर्व 16% है;
प्रति शेयर आय ₹ 8 है
लाभांश भुगतान आय का 50% है
लाभांश में अपेक्षित वृद्धि दर 10% है
प्रति शेयर चालू बाजार मूल्य ₹ 88 है
कर की दर 50% है
आपको अतिरिक्त वित्त जुटाने हेतु प्रतिरूप, अतिरिक्त ऋण की कर-पश्चात् औसत लागत, प्रतिधारित आय की लागत तथा समता पूँजी (इक्विटी) की लागत का निर्धारण करना है ।
अतिरिक्त वित्त की कर-पश्चात् समग्र भारांकित औसत लागत की गणना भी कीजिए । (20 अंक)
जेड लिमिटेड के निम्नलिखित संक्षिप्त नकद खाता से 31 मार्च, 2022 को समाप्त होने वाले वर्ष के लिए लेखांकन मानक-3 के अनुसार प्रत्यक्ष विधि से रोकड़ प्रवाह विवरण तैयार कीजिए । (15 अंक)
संक्षिप्त नकद खाता (31 मार्च, 2022 को समाप्त होने वाले वर्ष के लिए) (₹ '000 में)
01/04/2021 को शेष 100 आपूर्तिकर्ताओं को भुगतान 4,000 इक्विटी शेयरों का निर्गमन 600 अचल परिसंपत्तियों की खरीद 400 ग्राहकों से प्राप्तियां 5,600 उपरिव्यय 400 अचल परिसंपत्तियों की बिक्री 200 मजदूरी एवं वेतन 200 कर 500 लाभांश 100 बैंक ऋण का पुनर्भुगतान 600 31/03/2022 को शेष 300 6,500 6,500
नोट:
कंपनी के पास कोई नकद समतुल्यता नहीं है ।
नैगमिक (कॉर्पोरेट) पुनर्गठन क्या होता है ? नैगमिक पुनर्गठन की तकनीकों को स्पष्ट कीजिए । (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Financing Pattern and Cost of Additional Finance Total additional finance required = ₹20,00,000. Retained earnings available = ₹4,20,000. Debt-equity mix = 30% debt and 70% equity.
Pattern for raising additional finance:
- Debt = 30% of ₹20,00,000 = ₹6,00,000.
- Equity = 70% of ₹20,00,000 = ₹14,00,000.
- Equity will consist of retained earnings ₹4,20,000 and fresh equity shares ₹14,00,000 − ₹4,20,000 = ₹9,80,000.
- Debt will be split as: first ₹3,60,000 at 10% before tax; balance ₹6,00,000 − ₹3,60,000 = ₹2,40,000 at 16% before tax.
Thus the financing pattern is: debt ₹6,00,000, fresh equity ₹9,80,000 and retained earnings ₹4,20,000.
Post-tax average cost of additional debt: After-tax cost of first slab = 10% × (1 − 0.50) = 5%. After-tax cost of second slab = 16% × (1 − 0.50) = 8%. Average post-tax cost of debt = (₹3,60,000 × 5% + ₹2,40,000 × 8%) ÷ ₹6,00,000 = (₹18,000 + ₹19,200) ÷ ₹6,00,000 = ₹37,200 ÷ ₹6,00,000 = 0.062 = 6.2%.
Cost of equity: Dividend per share, D0 = EPS × payout ratio = ₹8 × 50% = ₹4. Expected dividend, D1 = D0(1 + g) = ₹4 × 1.10 = ₹4.40. Using dividend growth model: Ke = D1 ÷ P0 + g = ₹4.40 ÷ ₹88 + 0.10 = 0.05 + 0.10 = 0.15 = 15%. (If the ₹4 dividend is read as the next dividend D1, Ke = 4/88 + 0.10 = 14.55%, and the WACC becomes 12.04%.)
Cost of retained earnings: In the absence of personal tax, brokerage or flotation cost, cost of retained earnings equals cost of equity. Kr = Ke = 15%.
Overall weighted average after-tax cost of additional finance: Since no flotation cost is given, cost of fresh equity is also taken as 15%. Weights: debt = 30%, equity including retained earnings = 70%. WACC = 0.30 × 6.2% + 0.70 × 15% = 1.86% + 10.50% = 12.36%. Alternatively, using source amounts: (₹6,00,000 × 6.2% + ₹4,20,000 × 15% + ₹9,80,000 × 15%) ÷ ₹20,00,000 = 12.36%.
(b) Cash Flow Statement (Direct Method, AS-3) Under AS-3, using the direct method (₹ in '000):
Cash flows from operating activities:
- Cash received from customers: 5,600
- Cash paid to suppliers: (4,000)
- Wages and salaries paid: (200)
- Overhead expenses paid: (400) Cash generated from operations: 1,000
- Income tax paid: (500) Net cash from operating activities: 500
Cash flows from investing activities:
- Purchase of fixed assets: (400)
- Sale of fixed assets: 200 Net cash used in investing activities: (200)
Cash flows from financing activities:
- Issue of equity shares: 600
- Repayment of bank loan: (600)
- Dividend paid: (100) Net cash used in financing activities: (100)
Net increase in cash and cash equivalents = 500 − 200 − 100 = 200. Cash and cash equivalents at beginning = 100. Cash and cash equivalents at end = 100 + 200 = 300, which agrees with the closing balance. The company has no cash equivalents.
(c) Corporate Restructuring and its Techniques Corporate restructuring means redesigning the capital structure, business portfolio, ownership pattern, organisational setup or operations of a company to improve efficiency, competitiveness, profitability, survival or shareholder value. It may be financial, organisational, operational or portfolio restructuring.
Techniques of corporate restructuring include:
- Merger or amalgamation: two or more companies combine into one entity to achieve synergies, economies of scale and tax benefits.
- Acquisition or takeover: one company purchases controlling interest in another, either friendly or hostile.
- Demerger, spin-off, split-off or hive-off: a division, subsidiary or undertaking is separated into an independent entity or transferred to another company.
- Divestiture or disinvestment: sale of a division, subsidiary, brand or asset to focus on core activities.
- Slump sale: transfer of a whole undertaking or division for a lump-sum consideration without individually valuing assets and liabilities.
- Strategic alliance and joint venture: two or more firms cooperate or form a new entity for a specific project while retaining separate identities.
- Leveraged buyout and management buyout: acquisition financed mainly by debt, often by existing management.
- Financial restructuring: debt-equity swap, refinancing, rescheduling, share buyback, rights issue, bonus issue, capital reduction or recapitalisation.
- Organisational and operational restructuring: downsizing, outsourcing, business process reengineering, voluntary retirement schemes and closure of unviable units.
- Reverse merger: a private company merges with a listed shell company to obtain listing without an IPO.
In India the legal routes are compromises and arrangements under sections 230-232 of the Companies Act, 2013 (NCLT sanction), fast-track mergers of small companies, start-ups and wholly owned subsidiaries under section 233, capital reduction under section 66, buy-back under section 68, SEBI Takeover Regulations 2011 for listed targets, CCI approval of combinations above thresholds (including the deal-value test from 2024), and resolution plans under the Insolvency and Bankruptcy Code, 2016.
How this answer will be evaluated
Framework: AS-3 (Cash Flow Statements)
What earns full marks: Accurate calculations with workings; perfect AS-3 format; comprehensive theory with legal references.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Determine financing pattern, cost of debt, cost of equity, and WACC. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Split 20L into 6L debt and 14L equity
- Post-tax cost of debt: ₹3,60,000 at 5% and ₹2,40,000 at 8%, average 6.2%
- Cost of equity and retained earnings by dividend growth model: D1 = ₹4.40, Ke = 4.40/88 + 10% = 15% (Kr = Ke)
- Weighted average after-tax cost 12.36% (accept 12.04% if ₹4 treated as D1)
Loses marks
- Ignoring the 3.6L debt threshold for cost
- Using pre-tax cost of debt in WACC
- Failing to distinguish retained earnings from new equity
Earns more
- Correctly identifies 4.2L as retained earnings
- Shows working for average cost of debt
- Explicitly states the 30/70 mix application
Extra mark
- Mention of marginal cost of capital concept
- (b) Prepare Cash Flow Statement using Direct Method per AS-3. 15 marks
describe— define → structure or process in order → labelled diagram → significance
Must cover
- Operating 500, investing (200), financing (100), net increase 200, closing 300
- Use Direct Method for Operating Activities
- Correctly classify 'Sale of fixed assets' as Investing
- Correctly classify 'Issue of shares' as Financing
Loses marks
- Using Indirect Method instead of Direct
- Classifying 'Sale of fixed assets' as Operating
- Missing the 'Net increase/decrease in cash' line
Earns more
- Proper presentation of net cash flow from each head
- Reconciliation of opening and closing balances
Extra mark
- Explicit citation of AS-3 in the heading
- (c) Define corporate restructuring and explain its techniques. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Provide a clear definition of corporate restructuring
- List and explain at least 3-4 techniques (e.g., merger, demerger)
- Distinguish between financial and operational restructuring
- Mention the objective (e.g., efficiency, survival)
Loses marks
- Confusing restructuring with mere reorganization
- Listing techniques without explanation
- Ignoring the 'why' (objectives) of restructuring
Earns more
- Reference to Companies Act, 2013 sections
- Brief example of a restructuring technique
Extra mark
- Mention of 'Scheme of Arrangement' under Section 230-232
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…
- Q7 (a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment…
- Q8 (a) From the following information as contained in the Trading and Profit & Loss Account…