Paper I — Q8
(a) From the following information as contained in the Trading and Profit & Loss Account and Balance Sheet of X Ltd., you are…
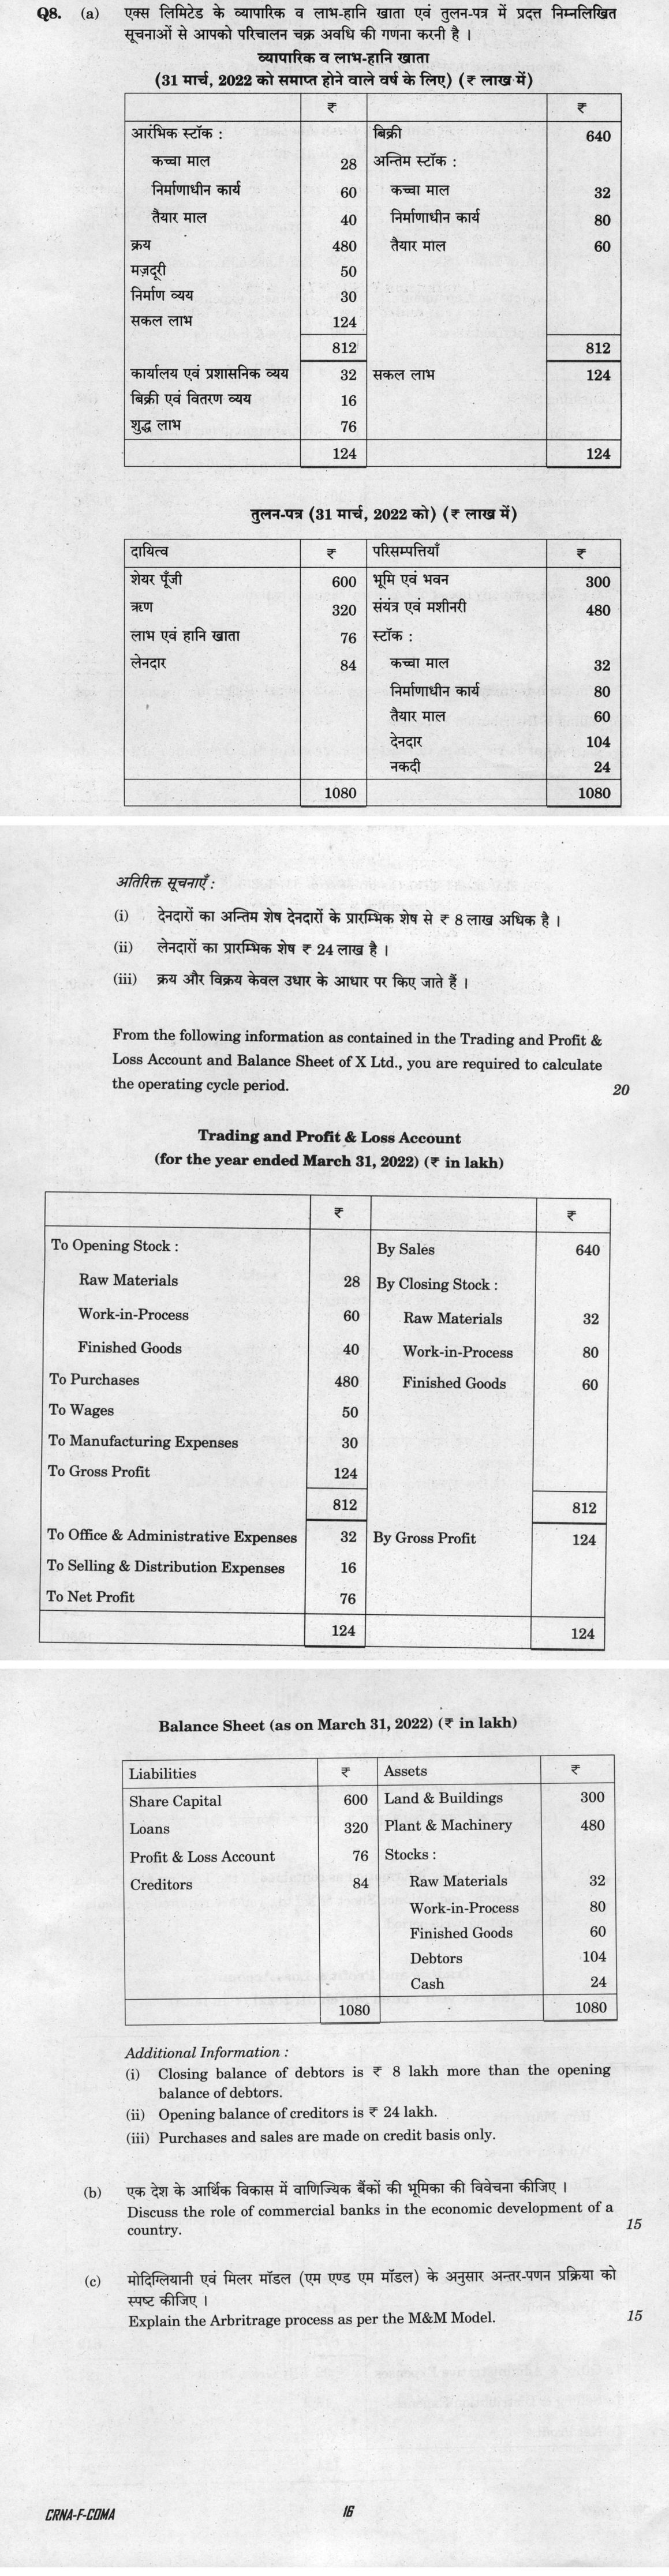
From the following information as contained in the Trading and Profit & Loss Account and Balance Sheet of X Ltd., you are required to calculate the operating cycle period. 20 marks
Trading and Profit & Loss Account (for the year ended March 31, 2022) (₹ in lakh)
To Opening Stock : Raw Materials 28 Work-in-Process 60 Finished Goods 40 To Purchases 480 To Wages 50 To Manufacturing Expenses 30 To Gross Profit 124
812
To Office & Administrative Expenses 32 To Selling & Distribution Expenses 16 To Net Profit 76
124
By Sales 640 By Closing Stock : Raw Materials 32 Work-in-Process 80 Finished Goods 60
812
By Gross Profit 124
124
Balance Sheet (as on March 31, 2022) (₹ in lakh)
Liabilities | ₹ | Assets | ₹ ---|---|---|--- Share Capital | 600 | Land & Buildings | 300 Loans | 320 | Plant & Machinery | 480 Profit & Loss Account | 76 | Stocks : | Creditors | 84 | Raw Materials | 32
| Work-in-Process | 80 | |
|---|---|---|
| Finished Goods | 60 | |
| Debtors | 104 | |
| Cash | 24 | |
| 1080 | 1080 |
Additional Information : Closing balance of debtors is ₹ 8 lakh more than the opening balance of debtors.
Opening balance of creditors is ₹ 24 lakh.
Purchases and sales are made on credit basis only.
Discuss the role of commercial banks in the economic development of a country. 15 marks
Explain the Arbitrage process as per the M&M Model. 15 marks
हिंदी में प्रश्न पढ़ें
एक्स लिमिटेड के व्यापारिक व लाभ-हानि खाता एवं तुलन-पत्र में प्रदत निम्नलिखित सूचनाओं से आपको परिचालन चक्र अवधि की गणना करनी है । (20 अंक)
व्यापारिक व लाभ-हानि खाता (31 मार्च, 2022 को समाप्त होने वाले वर्ष के लिए) (₹ लाख में)
| ₹ | ₹ | ||
|---|---|---|---|
| आरंभिक स्टॉक : | बिक्री | 640 | |
| कच्चा माल | 28 | अंतिम स्टॉक : | |
| निर्माणाधीन कार्य | 60 | कच्चा माल | 32 |
| तैयार माल | 40 | निर्माणाधीन कार्य | 80 |
| क्रय | 480 | तैयार माल | 60 |
| मजदूरी | 50 | ||
| निर्माण व्यय | 30 | ||
| सकल लाभ | 124 | ||
| 812 | 812 | ||
| कार्यालय एवं प्रशासनिक व्यय | 32 | सकल लाभ | 124 |
| बिक्री एवं वितरण व्यय | 16 | ||
| शुद्ध लाभ | 76 | ||
| 124 | 124 |
तुलन-पत्र (31 मार्च, 2022 को) (₹ लाख में)
| दायित्व | ₹ | परिसंपत्तियाँ | ₹ |
|---|---|---|---|
| शेयर पूंजी | 600 | भूमि एवं भवन | 300 |
| ऋण | 320 | संयंत्र एवं मशीनरी | 480 |
| लाभ एवं हानि खाता | 76 | स्टॉक : | |
| लेनदार | 84 | कच्चा माल | 32 |
| निर्माणाधीन कार्य | 80 | ||
| तैयार माल | 60 | ||
| देनदार | 104 | ||
| नकदी | 24 | ||
| 1080 | 1080 |
अतिरिक्त सूचनाएं :
देनदारों का अंतिम शेष देनदारों के प्रारंभिक शेष से ₹ 8 लाख अधिक है ।
लेनदारों का प्रारंभिक शेष ₹ 24 लाख है ।
क्रय और विक्रय केवल उधार के आधार पर किए जाते हैं ।
एक देश के आर्थिक विकास में वाणिज्यिक बैंकों की भूमिका की विवेचना कीजिए । (15 अंक)
मोदिग्लियानी एवं मिलर मॉडल (एम एंड एम मॉडल) के अनुसार अंतर-पणन प्रक्रिया को स्पष्ट कीजिए । (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Operating Cycle Period Method used: Net Operating Cycle = Raw Material Storage Period + Work-in-Process Period + Finished Goods Period + Debtors Collection Period − Creditors Payment Period. All periods are in days. Assuming a 360-day year, as is conventional in working capital management.
First compute cost figures (₹ in lakh):
- Raw material consumed = Opening RM + Purchases − Closing RM = 28 + 480 − 32 = 476.
- Cost of production = RM consumed + Wages + Manufacturing expenses + Opening WIP − Closing WIP = 476 + 50 + 30 + 60 − 80 = 536.
- Cost of goods sold = Cost of production + Opening FG − Closing FG = 536 + 40 − 60 = 516. Check: Sales − Gross Profit = 640 − 124 = 516.
From additional information: (i) Closing debtors = Opening debtors + 8, so Opening debtors = 104 − 8 = ₹96 lakh. (ii) Opening creditors = ₹24 lakh. (iii) Purchases and sales are credit only; hence credit purchases = ₹480 lakh and credit sales = ₹640 lakh.
Now calculate periods:
- Raw material storage period = Average RM / RM consumed × 360 = [(28 + 32) / 2] / 476 × 360 = 30 / 476 × 360 = 10800 / 476 = 22.689 days ≈ 22.69 days.
- WIP period = Average WIP / Cost of production × 360 = [(60 + 80) / 2] / 536 × 360 = 70 / 536 × 360 = 25200 / 536 = 47.015 days ≈ 47.01 days.
- Finished goods period = Average FG / COGS × 360 = [(40 + 60) / 2] / 516 × 360 = 50 / 516 × 360 = 18000 / 516 = 34.884 days ≈ 34.88 days.
- Debtors collection period = Average debtors / Credit sales × 360 = [(96 + 104) / 2] / 640 × 360 = 100 / 640 × 360 = 36000 / 640 = 56.25 days.
- Creditors payment period = Average creditors / Credit purchases × 360 = [(24 + 84) / 2] / 480 × 360 = 54 / 480 × 360 = 19440 / 480 = 40.5 days.
Gross operating cycle = 22.689 + 47.015 + 34.884 + 56.25 = 160.838 days. Net operating cycle = 160.838 − 40.5 = 120.338 days ≈ 120 days.
With a 365-day year the same ratios give a net operating cycle of about 122 days. Opening debtors (₹96 lakh) and opening creditors (₹24 lakh) are used to form averages.
(b) Role of Commercial Banks in Economic Development Commercial banks play a central role in economic development by mobilising savings and channelling them into productive investment. They collect small, scattered deposits and convert them into larger loans for agriculture, industry, trade, infrastructure, and services. This financial intermediation reduces the cost of capital and promotes capital formation.
They provide short-term, medium-term, and long-term credit to entrepreneurs, MSMEs, and corporate houses, thereby supporting production, employment, and innovation. Bank finance helps new enterprises overcome initial capital shortages and enables existing firms to expand capacity and adopt modern technology.
Banks also promote balanced regional development through branch expansion, rural credit, priority-sector lending, and financial inclusion. Schemes such as SHG-bank linkage, Kisan Credit Card, and MUDRA loans support agriculture, small business, and weaker sections. They facilitate trade and commerce through bills discounting, letters of credit, remittances, foreign exchange, and export finance.
As agents of monetary policy, commercial banks transmit central bank decisions to the real economy by adjusting lending and deposit rates. They also support government development programmes, infrastructure financing, and digital payments. Their developmental role depends on balance-sheet health: the gross NPA ratio of Indian scheduled commercial banks fell from about 11.2% in March 2018 to 2.3% in March 2025 (RBI Financial Stability Report, June 2025), after recapitalisation, the IBC and the asset quality review, which restored their capacity to lend.
(c) Arbitrage Process under the M&M Model The M&M arbitrage process explains why, under perfect capital markets and no taxes, a firm’s value is independent of its capital structure. According to M&M Proposition I, V_U = V_L, where V_U is the value of an unlevered firm and V_L is the value of a levered firm with identical operating income and risk.
Suppose two firms have the same expected EBIT, X, but one is unlevered (U) and the other is levered (L) with debt D and interest rate r. If the market temporarily values the levered firm more, so V_L > V_U, an investor can use “home-made leverage” to earn a higher return without extra risk.
Let an investor hold α fraction of L’s equity. His investment is αE_L = α(V_L − D). His return is α(X − rD). He sells these shares, borrows αD personally at the same rate r, and buys α fraction of U’s equity. Since V_L > V_U, he has surplus α(V_L − V_U), which he invests in risk-free securities.
His new return = αX − αrD + rα(V_L − V_U). This exceeds the old return α(X − rD) by rα(V_L − V_U). Thus, investors shift from L to U, raising U’s price and lowering L’s price until V_L = V_U.
The reverse arbitrage works if V_U > V_L. The process assumes perfect markets, homogeneous risk classes, no taxes, no bankruptcy costs, and equal borrowing rates for firms and investors. Hence, arbitrage restores equilibrium and makes capital structure irrelevant to firm value.
How this answer will be evaluated
What earns full marks: All parts fully addressed with correct calculations, detailed discussion, and clear explanations.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Operating cycle period in days using working capital components. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Calculate average debtors and creditors
- Periods: RM 22.69, WIP 47.01, FG 34.88, debtors 56.25, creditors 40.5 days (360-day year)
- Net operating cycle ≈ 120 days (gross 160.84 less 40.5), about 122 days on a 365-day basis
- Show working notes for all calculations
Loses marks
- Final figure without working notes
- Incorrect calculation of average balances
- Omission of any component in operating cycle
Earns more
- Correctly identifies credit sales and purchases
- Uses average stock for inventory period
- Uses RM consumed, cost of production and COGS (516) as the correct denominators
- Final answer stated in days
Extra mark
- Mentions impact of operating cycle on liquidity
- Compares with industry standard
- (b) Role of commercial banks in economic development. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Mobilisation of savings and financial intermediation into capital formation
- 3-4 dimensions of their role
- Example of a specific role
- Role in financial inclusion, priority-sector credit and monetary transmission
Loses marks
- Generic statements without specific roles
- No examples provided
- Lack of structure in discussion
Earns more
- Mentions credit creation function
- Discusses role in industrial development
- References government policies
- Includes recent examples
Extra mark
- Cites specific RBI guidelines
- References a specific economic study
- (c) Arbitrage process as per the M&M Model. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Definition of M&M Model
- Step-by-step arbitrage process
- Small example of arbitrage
- Arbitrage continues until V_L = V_U, making capital structure irrelevant (no taxes)
Loses marks
- Vague description of arbitrage
- No reference to M&M Model specifics
- Lack of logical sequence in explanation
Earns more
- Mentions assumptions of M&M Model
- Explains how arbitrage restores equilibrium
- References Modigliani and Miller
- Includes numerical example
Extra mark
- Cites the original 1958 paper
- Mentions limitations of the model
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…
- Q7 (a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment…
- Q8 (a) From the following information as contained in the Trading and Profit & Loss Account…