Paper I — Q6
(a) From the following data, you are required to prepare a Balance Sheet and a Statement of Profit and Loss : (a) Share Capital…
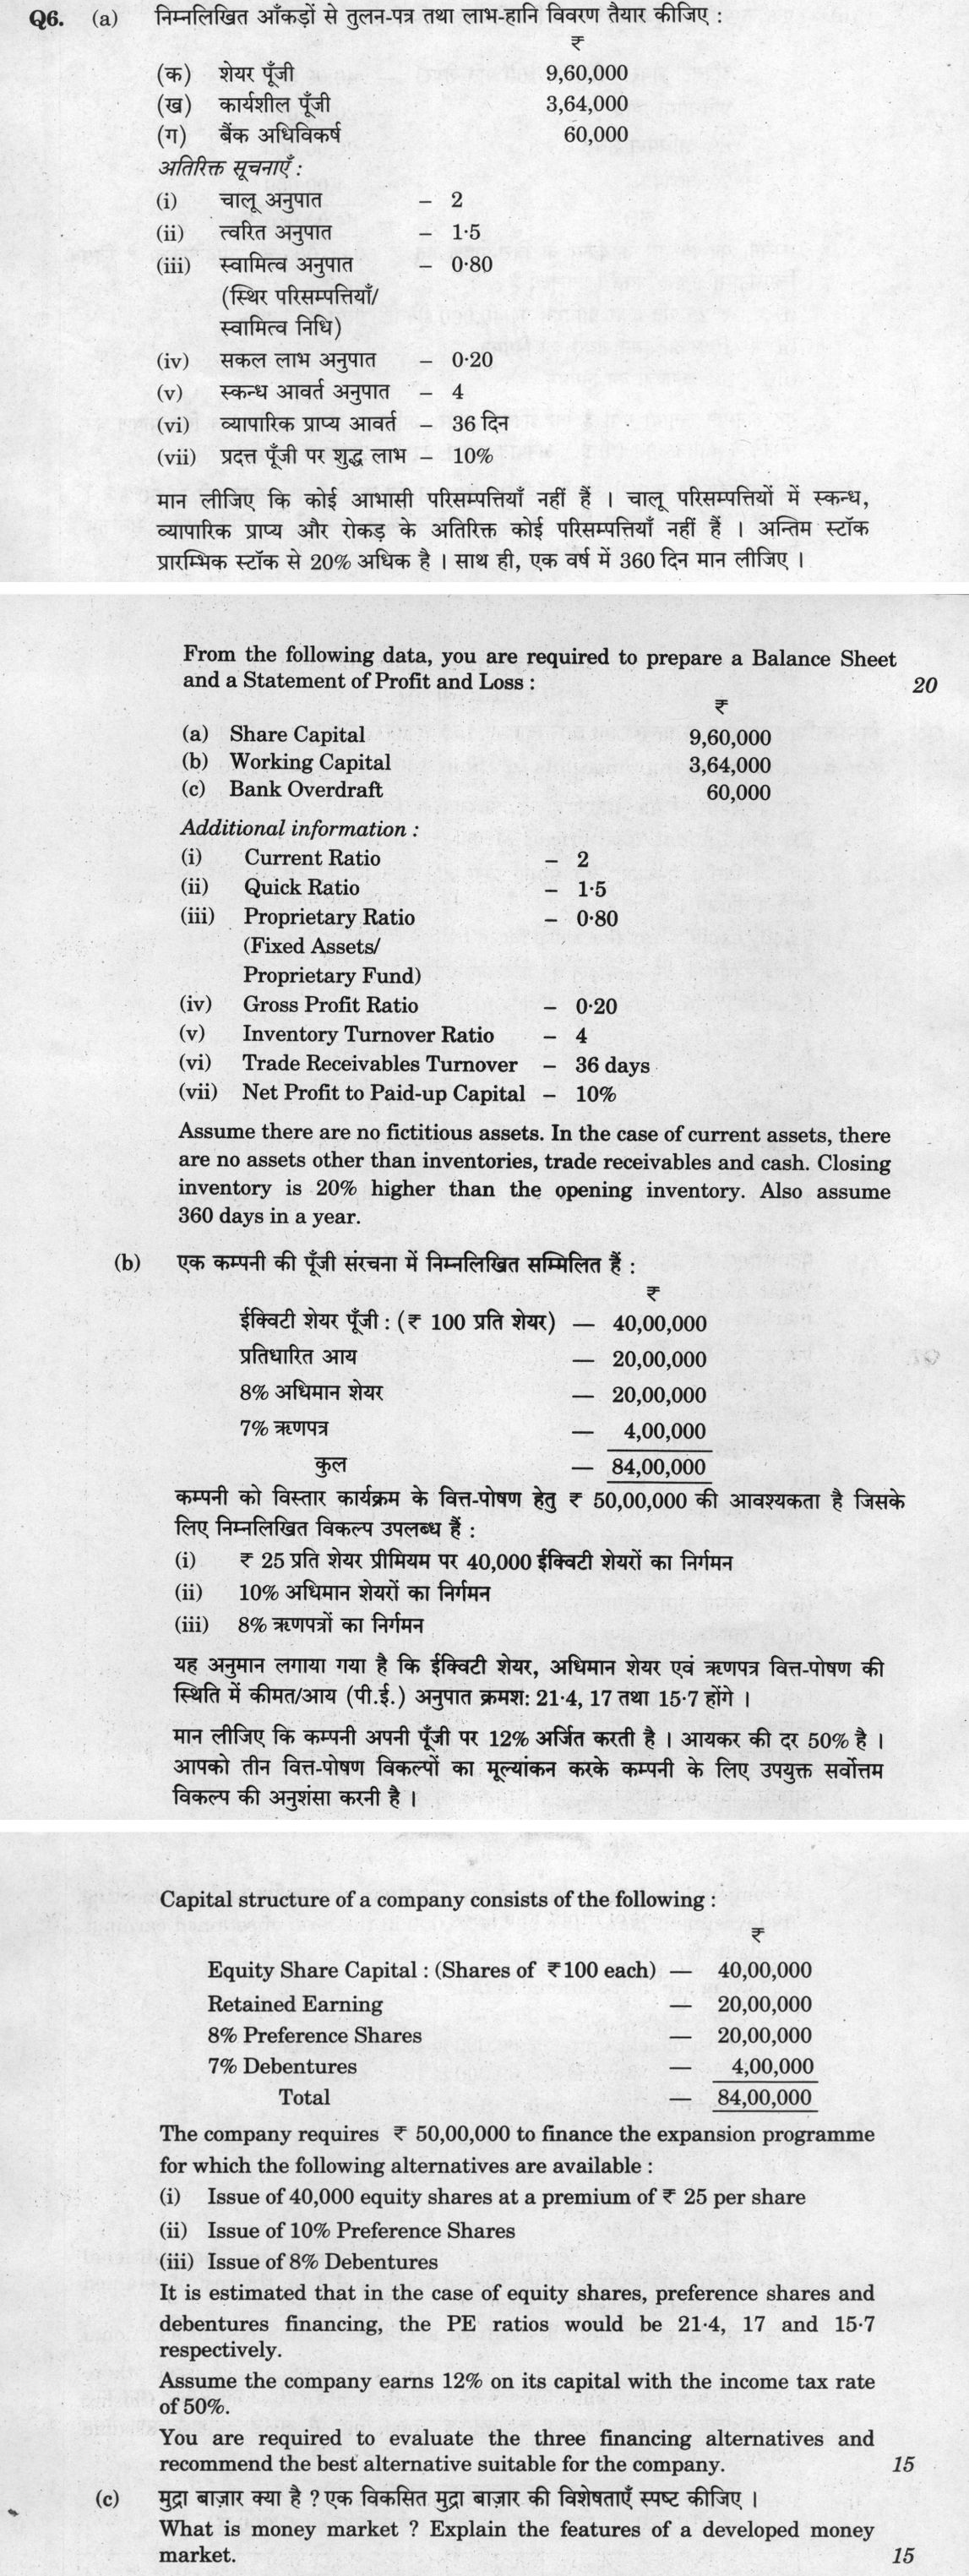
From the following data, you are required to prepare a Balance Sheet and a Statement of Profit and Loss :
Share Capital 9,60,000
Working Capital 3,64,000
Bank Overdraft 60,000
Additional information : Current Ratio – 2
Quick Ratio – 1·5
Proprietary Ratio – 0·80 (Fixed Assets/Proprietary Fund)
Gross Profit Ratio – 0·20
Inventory Turnover Ratio – 4
Trade Receivables Turnover – 36 days
Net Profit to Paid-up Capital – 10%
Assume there are no fictitious assets. In the case of current assets, there are no assets other than inventories, trade receivables and cash. Closing inventory is 20% higher than the opening inventory. Also assume 360 days in a year.
Capital structure of a company consists of the following :
Equity Share Capital : (Shares of ₹100 each) — 40,00,000 Retained Earning — 20,00,000 8% Preference Shares — 20,00,000 7% Debentures — 4,00,000 Total — 84,00,000
The company requires ₹ 50,00,000 to finance the expansion programme for which the following alternatives are available : Issue of 40,000 equity shares at a premium of ₹ 25 per share
Issue of 10% Preference Shares
Issue of 8% Debentures
It is estimated that in the case of equity shares, preference shares and debentures financing, the PE ratios would be 21·4, 17 and 15·7 respectively.
Assume the company earns 12% on its capital with the income tax rate of 50%.
You are required to evaluate the three financing alternatives and recommend the best alternative suitable for the company. 15 marks
What is money market ? Explain the features of a developed money market. 15 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित आँकड़ों से तुलन-पत्र तथा लाभ-हानि विवरण तैयार कीजिए :
(क) शेयर पूँजी 9,60,000 (ख) कार्यशील पूँजी 3,64,000 (ग) बैंक अधिविकर्ष 60,000
अतिरिक्त सूचनाएँ : चालू अनुपात – 2
त्वरित अनुपात – 1·5
स्वामित्व अनुपात – 0·80 (स्थिर परिसम्पत्तियाँ/स्वामित्व निधि)
सकल लाभ अनुपात – 0·20
स्कन्ध आवर्त अनुपात – 4
व्यापारिक प्राप्य आवर्त – 36 दिन
प्रदत्त पूँजी पर शुद्ध लाभ – 10%
मान लीजिए कि कोई आभासी परिसम्पत्तियाँ नहीं हैं । चालू परिसम्पत्तियों में स्कन्ध, व्यापारिक प्राप्य और रोकड़ के अतिरिक्त कोई परिसम्पत्तियाँ नहीं हैं । अंतिम स्टॉक प्रारंभिक स्टॉक से 20% अधिक है । साथ ही, एक वर्ष में 360 दिन मान लीजिए ।
एक कम्पनी की पूँजी संरचना में निम्नलिखित सम्मिलित हैं :
इक्विटी शेयर पूँजी : (₹ 100 प्रति शेयर) — 40,00,000 प्रतिधारित आय — 20,00,000 8% अधिमान शेयर — 20,00,000 7% ऋणपत्र — 4,00,000 कुल — 84,00,000
कम्पनी को विस्तार कार्यक्रम के वित्त-पोषण हेतु ₹ 50,00,000 की आवश्यकता है जिसके लिए निम्नलिखित विकल्प उपलब्ध हैं : ₹ 25 प्रति शेयर प्रीमियम पर 40,000 इक्विटी शेयरों का निर्गमन
10% अधिमान शेयरों का निर्गमन
8% ऋणपत्रों का निर्गमन
यह अनुमान लगाया गया है कि इक्विटी शेयर, अधिमान शेयर एवं ऋणपत्र वित्त-पोषण की स्थिति में कीमत/आय (पी.ई.) अनुपात क्रमशः 21·4, 17 तथा 15·7 होंगे ।
मान लीजिए कि कम्पनी अपनी पूँजी पर 12% अर्जित करती है । आयकर की दर 50% है । आपको तीन वित्त-पोषण विकल्पों का मूल्यांकन करके कम्पनी के लिए उपयुक्त सर्वोत्तम विकल्प की अनुशंसा करनी है । 15
मुद्रा बाजार क्या है ? एक विकसित मुद्रा बाजार की विशेषताएँ स्पष्ट कीजिए । 15
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Balance Sheet and Statement of Profit and Loss Using Current Ratio and Working Capital: Current Ratio = Current Assets / Current Liabilities = 2, so Current Assets = 2 × Current Liabilities. Working Capital = Current Assets − Current Liabilities = ₹3,64,000. Thus 2 × Current Liabilities − Current Liabilities = ₹3,64,000, so Current Liabilities = ₹3,64,000 and Current Assets = ₹7,28,000. Bank Overdraft = ₹60,000, hence other current liabilities = ₹3,64,000 − ₹60,000 = ₹3,04,000.
Using Quick Ratio = (Current Assets − Inventory) / Current Liabilities = 1.5: Current Assets − Inventory = 1.5 × ₹3,64,000 = ₹5,46,000. Closing Inventory = ₹7,28,000 − ₹5,46,000 = ₹1,82,000. Closing inventory is 20% higher than opening, so Opening Inventory = ₹1,82,000 / 1.2 = ₹1,51,666⅔. Average Inventory = (₹1,82,000 + ₹1,51,666⅔) / 2 = ₹1,66,833⅓. Inventory Turnover = Cost of Goods Sold / Average Inventory = 4, so Cost of Goods Sold = 4 × ₹1,66,833⅓ = ₹6,67,333⅓. Gross Profit Ratio = 0.20, so Cost of Goods Sold = 0.80 × Sales. Sales = ₹6,67,333⅓ / 0.80 = ₹8,34,166⅔. Gross Profit = ₹8,34,166⅔ − ₹6,67,333⅓ = ₹1,66,833⅓.
Trade Receivables Turnover = (Trade Receivables / Sales) × 360 = 36 days. Trade Receivables = ₹8,34,166⅔ × 36/360 = ₹83,416⅔. Quick Assets = Trade Receivables + Cash = ₹5,46,000, so Cash = ₹5,46,000 − ₹83,416⅔ = ₹4,62,583⅓.
Net Profit = 10% of Paid-up Capital = 10% × ₹9,60,000 = ₹96,000. Operating Expenses = Gross Profit − Net Profit = ₹1,66,833⅓ − ₹96,000 = ₹70,833⅓.
Proprietary Ratio is given as Fixed Assets / Proprietary Fund = 0.80. Let Proprietary Fund = PF. Then Fixed Assets = 0.80 PF. Balance Sheet identity: PF + Current Liabilities = Fixed Assets + Current Assets. PF + ₹3,64,000 = 0.80 PF + ₹7,28,000. 0.20 PF = ₹3,64,000, so PF = ₹18,20,000. Fixed Assets = 0.80 × ₹18,20,000 = ₹14,56,000. Reserves and Surplus = PF − Share Capital = ₹18,20,000 − ₹9,60,000 = ₹8,60,000, including current year profit ₹96,000.
Purchases = Cost of Goods Sold + Closing Inventory − Opening Inventory = ₹6,67,333⅓ + ₹1,82,000 − ₹1,51,666⅔ = ₹6,97,666⅔.
Statement of Profit and Loss
- Sales: ₹8,34,166⅔
- Less: Opening Inventory: ₹1,51,666⅔
- Add: Purchases: ₹6,97,666⅔
- Goods available: ₹8,49,333⅓
- Less: Closing Inventory: ₹1,82,000
- Cost of Goods Sold: ₹6,67,333⅓
- Gross Profit: ₹1,66,833⅓
- Less: Operating Expenses: ₹70,833⅓
- Net Profit: ₹96,000
Balance Sheet Liabilities
- Share Capital: ₹9,60,000
- Reserves and Surplus: ₹8,60,000
- Bank Overdraft: ₹60,000
- Other Current Liabilities: ₹3,04,000
- Total: ₹21,84,000
Assets
- Fixed Assets: ₹14,56,000
- Inventory: ₹1,82,000
- Trade Receivables: ₹83,416⅔
- Cash: ₹4,62,583⅓
- Total: ₹21,84,000
(b) Evaluation of Financing Alternatives Existing equity shares = ₹40,00,000 / ₹100 = 40,000 shares. Existing debenture interest = 7% × ₹4,00,000 = ₹28,000. Existing preference dividend = 8% × ₹20,00,000 = ₹1,60,000. Total capital after expansion = ₹84,00,000 + ₹50,00,000 = ₹1,34,00,000. EBIT = 12% × ₹1,34,00,000 = ₹16,08,000. Tax rate = 50%.
(b)(i) Issue of 40,000 equity shares at premium of ₹25 per share Funds raised = 40,000 × ₹125 = ₹50,00,000. Total equity shares = 40,000 + 40,000 = 80,000. PBT = ₹16,08,000 − ₹28,000 = ₹15,80,000. Tax = ₹7,90,000; PAT = ₹7,90,000. Equity earnings = ₹7,90,000 − ₹1,60,000 = ₹6,30,000. EPS = ₹6,30,000 / 80,000 = ₹7.875. Market Price = ₹7.875 × 21.4 = ₹168.53.
(b)(ii) Issue of 10% Preference Shares New preference dividend = 10% × ₹50,00,000 = ₹5,00,000. Total preference dividend = ₹1,60,000 + ₹5,00,000 = ₹6,60,000. PBT = ₹15,80,000; Tax = ₹7,90,000; PAT = ₹7,90,000. Equity earnings = ₹7,90,000 − ₹6,60,000 = ₹1,30,000. EPS = ₹1,30,000 / 40,000 = ₹3.25. Market Price = ₹3.25 × 17 = ₹55.25.
(b)(iii) Issue of 8% Debentures New interest = 8% × ₹50,00,000 = ₹4,00,000. Total interest = ₹28,000 + ₹4,00,000 = ₹4,28,000. PBT = ₹16,08,000 − ₹4,28,000 = ₹11,80,000. Tax = ₹5,90,000; PAT = ₹5,90,000. Equity earnings = ₹5,90,000 − ₹1,60,000 = ₹4,30,000. EPS = ₹4,30,000 / 40,000 = ₹10.75. Market Price = ₹10.75 × 15.7 = ₹168.78.
Recommendation: The 8% debenture alternative gives the highest EPS, ₹10.75, and the highest market price, ₹168.78, slightly above equity financing. It is also tax-efficient because interest is deductible. Hence, on the given evaluation, the company should choose (iii) Issue of 8% Debentures, subject to acceptance of higher financial risk.
(c) Money Market and Features of a Developed Money Market A money market is a market for short-term funds, generally up to one year. It deals in highly liquid near-money instruments such as call and notice money, Treasury bills, commercial paper, certificates of deposit, commercial bills, and repo/reverse repo. It is not a single physical place but a network of institutions including the central bank, commercial banks, financial institutions, primary dealers, discount houses, and brokers. In India it is regulated by the RBI under section 45W (Chapter IIID) of the RBI Act, 1934, and the main segments are call money, TREPS, market repo, T-bills of 91, 182 and 364 days, CP and CD.
Features of a developed money market:
- Highly organised and integrated, with close links among sub-markets such as call money, bill market, and gilt-edged market.
- Wide range of short-term instruments with high liquidity and negotiability.
- Active presence of the central bank as regulator, lender of last resort, and monetary policy operator.
- Strong and sound banking system with a large number of participants.
- Efficient discounting, acceptance, and rediscounting facilities for trade bills.
- Depth and liquidity: large transaction volumes, narrow bid-ask spreads, and quick execution.
- Competitive and integrated interest rates reflecting demand, supply, and policy signals.
- Developed secondary market for short-term instruments.
- Adequate legal and regulatory framework and credit rating institutions.
- Advanced payment, clearing, and settlement infrastructure.
- Presence of specialised institutions such as discount houses, primary dealers, and money market mutual funds.
- Efficient information system providing timely data on rates, volumes, and issuers.
- Integration with the forex market and international money markets.
- Overall monetary stability and confidence among participants.
How this answer will be evaluated
What earns full marks: All parts fully answered with correct workings, clear presentation, and accurate application of concepts.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Prepare Balance Sheet and Statement of P&L from ratios and data. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Working notes for all derived figures
- GP ₹1,66,833⅓ (sales ₹8,34,166⅔, COGS ₹6,67,333⅓ from inventory turnover on average inventory) and NP ₹96,000
- Balance Sheet totals ₹21,84,000 (fixed assets ₹14,56,000 from proprietary fund ₹18,20,000)
- Statement of P&L format with Gross and Net Profit
Loses marks
- Final figures without working notes
- Incorrect statement format
- Arithmetic errors in ratio application
Earns more
- Correct derivation of Sales from Inventory Turnover
- Correct calculation of Trade Receivables
- Correct calculation of Fixed Assets
- Correct calculation of Current Assets
Extra mark
- Explicit statement of assumptions used
- Clear labeling of working notes
- (b) Evaluate three financing alternatives and recommend the best one. 15 marks
evaluate— criteria → evidence → balanced judgment
Must cover
- EPS: equity ₹7.875, preference ₹3.25, debentures ₹10.75 (EBIT ₹16,08,000 at 12% on ₹1,34,00,000)
- MPS: equity ₹168.53, preference ₹55.25, debentures ₹168.78
- Comparison of Market Prices to determine best option
- Recommends 8% debentures (highest MPS), noting higher financial risk
Loses marks
- Failure to calculate Market Price per Share
- Incorrect application of PE ratio formula
- No clear recommendation
Earns more
- Correct calculation of Earnings Available to Equity Shareholders
- Correct application of PE ratios
- Correct calculation of number of shares for each option
- Clear presentation of comparative table
Extra mark
- Mention of dilution effect on equity
- Brief comment on cost of capital
- (c) Define money market and explain features of a developed money market. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Clear definition of money market
- Explanation of at least 4-5 features of developed money market
- Mention of short-term nature of instruments
- Reference to high liquidity and low risk
Loses marks
- Confusing money market with capital market
- Vague or generic features without specific context
- No clear definition
Earns more
- Mention of specific instruments (T-bills, CP, etc.)
- Reference to role of central bank
- Mention of secondary market operations
- Clear structure with headings
Extra mark
- Example of a specific money market instrument
- Reference to RBI's role in India
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q3 (a) X, an employee of a firm, furnished the following particulars of his income for the y…
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…
- Q7 (a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment…
- Q8 (a) From the following information as contained in the Trading and Profit & Loss Account…