Paper I — Q5
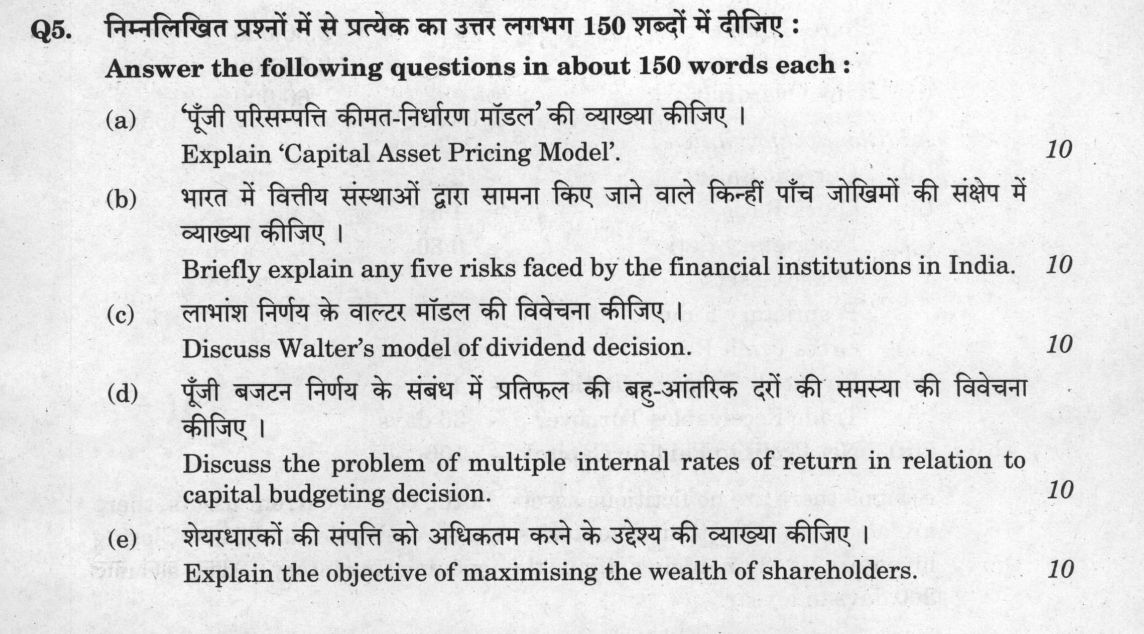
(a) Explain 'Capital Asset Pricing Model'. 10 (b) Briefly explain any five risks faced by the financial institutions in India…
Answer the following questions in about 150 words each :
Explain 'Capital Asset Pricing Model'. 10 marks
Briefly explain any five risks faced by the financial institutions in India. 10 marks
Discuss Walter's model of dividend decision. 10 marks
Discuss the problem of multiple internal rates of return in relation to capital budgeting decision. 10 marks
Explain the objective of maximising the wealth of shareholders. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए :
'पूँजी परिसम्पत्ति कीमत-निर्धारण मॉडल' की व्याख्या कीजिए । 10
भारत में वित्तीय संस्थाओं द्वारा सामना किए जाने वाले किन्हीं पाँच जोखिमों की संक्षेप में व्याख्या कीजिए । 10
लाभांश निर्णय के वाल्टर मॉडल की विवेचना कीजिए । 10
पूँजी बजटन निर्णय के संबंध में प्रतिफल की बहु-आंतरिक दरों की समस्या की विवेचना कीजिए । 10
शेयरधारकों की संपत्ति को अधिकतम करने के उद्देश्य की व्याख्या कीजिए । 10
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Capital Asset Pricing Model (CAPM)
The Capital Asset Pricing Model, developed by William Sharpe (1964), John Lintner (1965) and Jan Mossin (1966), establishes a linear relationship between the required rate of return of an asset and its systematic risk. The model is expressed as:
E(Rᵢ) = R_f + βᵢ [E(Rₘ) - R_f]
where E(Rᵢ) is the expected return, R_f is the risk-free rate (e.g., Indian 91-day Treasury Bills), E(Rₘ) is the expected market return, and [E(Rₘ) - R_f] is the equity risk premium.
CAPM bifurcates total risk into unsystematic (diversifiable/firm-specific) risk and systematic (non-diversifiable/market) risk. Because rational investors eliminate unsystematic risk through diversification, the market prices only systematic risk. Beta (βᵢ) quantifies this sensitivity relative to the market index. Graphically, this relationship forms the Security Market Line (SML).
While CAPM offers a clear benchmark for project appraisal and hurdle rates, it assumes frictionless markets, homogeneous expectations, and a single-period horizon, which often deviate from empirical market realities.
(b) Five Risks Faced by Financial Institutions in India
Financial institutions (FIs) in India navigate a complex operational and macroeconomic environment, exposing them to five key risks:
- Credit Risk: The risk of loss arising from borrower default on interest or principal repayments. This manifests in elevated Non-Performing Assets (NPAs), necessitating higher provisioning under RBI guidelines and resolution via the Insolvency and Bankruptcy Code (IBC).
- Liquidity Risk: Arises from an Asset-Liability Mismatch (ALM) when short-term liabilities (e.g., commercial papers) fund long-term illiquid assets, as observed during the IL&FS crisis.
- Market Risk: Vulnerability of the trading book to adverse fluctuations in interest rates, equity prices, and foreign exchange rates, which affects the valuation of government securities and foreign currency exposures.
- Operational Risk: Losses resulting from inadequate internal controls, technical disruptions, and cyber threats (e.g., payment gateway breaches or fraudulent issuance of Letters of Undertaking).
- Regulatory and Compliance Risk: Financial and reputational penalties from non-compliance with evolving norms, such as Basel III capital adequacy ratios, Prompt Corrective Action (PCA) frameworks, and dynamic CRR/SLR mandates.
(c) Walter's Model of Dividend Decision
James E. Walter’s model posits that dividend policy directly influences firm valuation by linking the internal rate of return on investment (r) with the firm's cost of capital (kₑ). The valuation formula is:
P = [D + (r/kₑ)(E − D)] ÷ kₑ
where P is market price per share, D is dividend per share, and E is earnings per share.
The causal mechanism dictates three distinct strategic scenarios:
- Growth Firm (r > kₑ): The firm generates superior returns compared to what shareholders can earn externally. Maximum value is achieved by retaining all earnings (optimum payout ratio = 0%).
- Declining Firm (r < kₑ): External market opportunities yield higher returns than the firm's reinvestments. Value is maximized by distributing all earnings (optimum payout ratio = 100%).
- Normal Firm (r = kₑ): Internal returns match external expectations. The dividend payout is irrelevant, and P remains constant across all distribution ratios.
The model assumes 100% internal equity financing (no external debt or equity) and constant values of r and kₑ.
(d) Problem of Multiple Internal Rates of Return (IRR)
The Internal Rate of Return (IRR) is the discount rate that equates the Net Present Value (NPV) of a project to zero.
The problem of multiple IRRs arises in non-conventional (non-normal) cash flow streams, where the sequence of net cash inflows and outflows changes signs more than once across the project lifecycle (e.g., initial investment followed by inflows, and subsequent major decommissioning costs). By Descartes’ Rule of Signs, the number of positive real roots (IRRs) cannot exceed the number of sign reversals, so two reversals can give two IRRs, and some streams give no real IRR at all. Example: −1,600, +10,000, −10,000 gives IRRs of 25% and 400%.
Consequently, the project’s NPV profile intersects the horizontal discount-rate axis multiple times, so the decision rule (accept if IRR > cost of capital) becomes ambiguous, a project may have positive NPV only between the two IRRs. Furthermore, standard IRR unrealistically assumes reinvestment of interim cash inflows at the internal rate itself.
This structural defect is resolved by adopting the Net Present Value (NPV) criterion or computing the Modified Internal Rate of Return (MIRR), which assumes reinvestment at the firm's cost of capital.
(e) Objective of Maximising Shareholders' Wealth
Wealth maximisation represents the primary operational objective of modern financial management, operationalised as maximising the market value of the firm's equity shares. It is mathematically measured as maximizing the Net Present Value (NPV) of all corporate decisions:
W = Σₜ₌₁ⁿ (CFₜ)/((1+k)^t) - C₀
Wealth maximisation is conceptually superior to profit maximisation due to the following reasons:
- Time Value of Money: Profit maximisation focuses on accounting profit and ignores the timing of cash inflows, whereas wealth maximisation discounts expected future cash flows over time.
- Explicit Handling of Risk: Profit maximisation treats uncertain and certain earnings equally. Wealth maximisation incorporates business and financial risk through risk-adjusted discount rates (k).
- Ambiguity and Scale: "Profit" is subject to accounting interpretations (e.g., depreciation methods) and ignores the capital outlay required. Wealth maximisation relies on objective, verifiable cash flows.
- Agency and stakeholders: managers may pursue their own goals, so incentives, monitoring and governance align them with owners, and long-run value requires fair treatment of creditors, employees and customers.
How this answer will be evaluated
What earns full marks: Precise definitions, correct formulas, clear distinctions, and relevant examples.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Definition, formula, and key assumptions of CAPM. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- State CAPM formula (E(R) = Rf + β(Rm - Rf))
- Define beta (β) as systematic risk measure
- List at least two key assumptions (e.g., risk aversion)
- Briefly mention the Security Market Line (SML)
Loses marks
- Confusing CAPM with CML
- Omitting the risk-free rate from the formula
Earns more
- Distinguish between systematic and unsystematic risk
- Mention the Capital Market Line (CML)
Extra mark
- Provide a simple numerical example of CAPM calculation
- (b) Five specific risks faced by Indian financial institutions. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Identify five distinct risks (e.g., Credit, Market, Liquidity)
- Briefly define each identified risk
- Contextualize risks within the Indian financial system
- Ensure all five risks are clearly distinguished
Loses marks
- Listing fewer than five risks
- Vague definitions without specific risk names
Earns more
- Mention specific Indian regulatory context (RBI/SEBI)
- Link risks to recent economic events
Extra mark
- Reference specific RBI guidelines on risk management
- (c) Walter's model logic: r vs k and dividend policy. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Define r (return on investment) and k (cost of equity)
- Explain the 'Growth' case (r > k)
- Explain the 'Maturity' case (r < k)
- Explain the 'Indifference' case (r = k)
Loses marks
- Confusing r and k definitions
- Failing to distinguish the three cases
Earns more
- Mention the limitations of Walter's model
- States the valuation formula P = [D + (r/ke)(E − D)]/ke
Extra mark
- Provide a simple numerical illustration of r vs k
- (d) Problem of multiple IRRs in capital budgeting. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Define multiple IRRs (non-conventional cash flows)
- Explain why multiple IRRs occur (sign changes)
- Discuss the ambiguity in accept/reject decisions
- Suggest NPV as the resolution method
Loses marks
- Failing to link multiple IRRs to sign changes
- Not mentioning NPV as the alternative
Earns more
- Mention the 'reinvestment rate' assumption of IRR
- Provides a small example of non-conventional cash flows (e.g. −1,600, +10,000, −10,000 giving 25% and 400%)
Extra mark
- Reference the 'modified IRR' (MIRR) as a solution
- (e) Objective of maximizing shareholder wealth. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Define shareholder wealth (market value of shares)
- Contrast with profit maximization
- Explain why it is the primary financial objective
- Mention the role of time value of money
Loses marks
- Confusing shareholder wealth with profit maximization
- Ignoring the time value of money aspect
Earns more
- Discuss the agency problem briefly
- Mention the role of dividends and capital gains
Extra mark
- Reference the 'efficient market hypothesis' in this context
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2022 Paper I
- Q2 (a) Balance Sheets of A Ltd. and B Ltd. as on March 31, 2021 are as follows: | | A Ltd. (…
- Q3 (a) X, an employee of a firm, furnished the following particulars of his income for the y…
- Q4 (a) The following details have been extracted from the cost records of a company : Materi…
- Q5 Answer the following questions in about 150 words each : (a) Explain 'Capital Asset Prici…
- Q6 (a) From the following data, you are required to prepare a Balance Sheet and a Statement…
- Q7 (a) A company wishes to raise additional finance of ₹ 20 lakh for meeting its investment…
- Q8 (a) From the following information as contained in the Trading and Profit & Loss Account…