Paper I — Q6
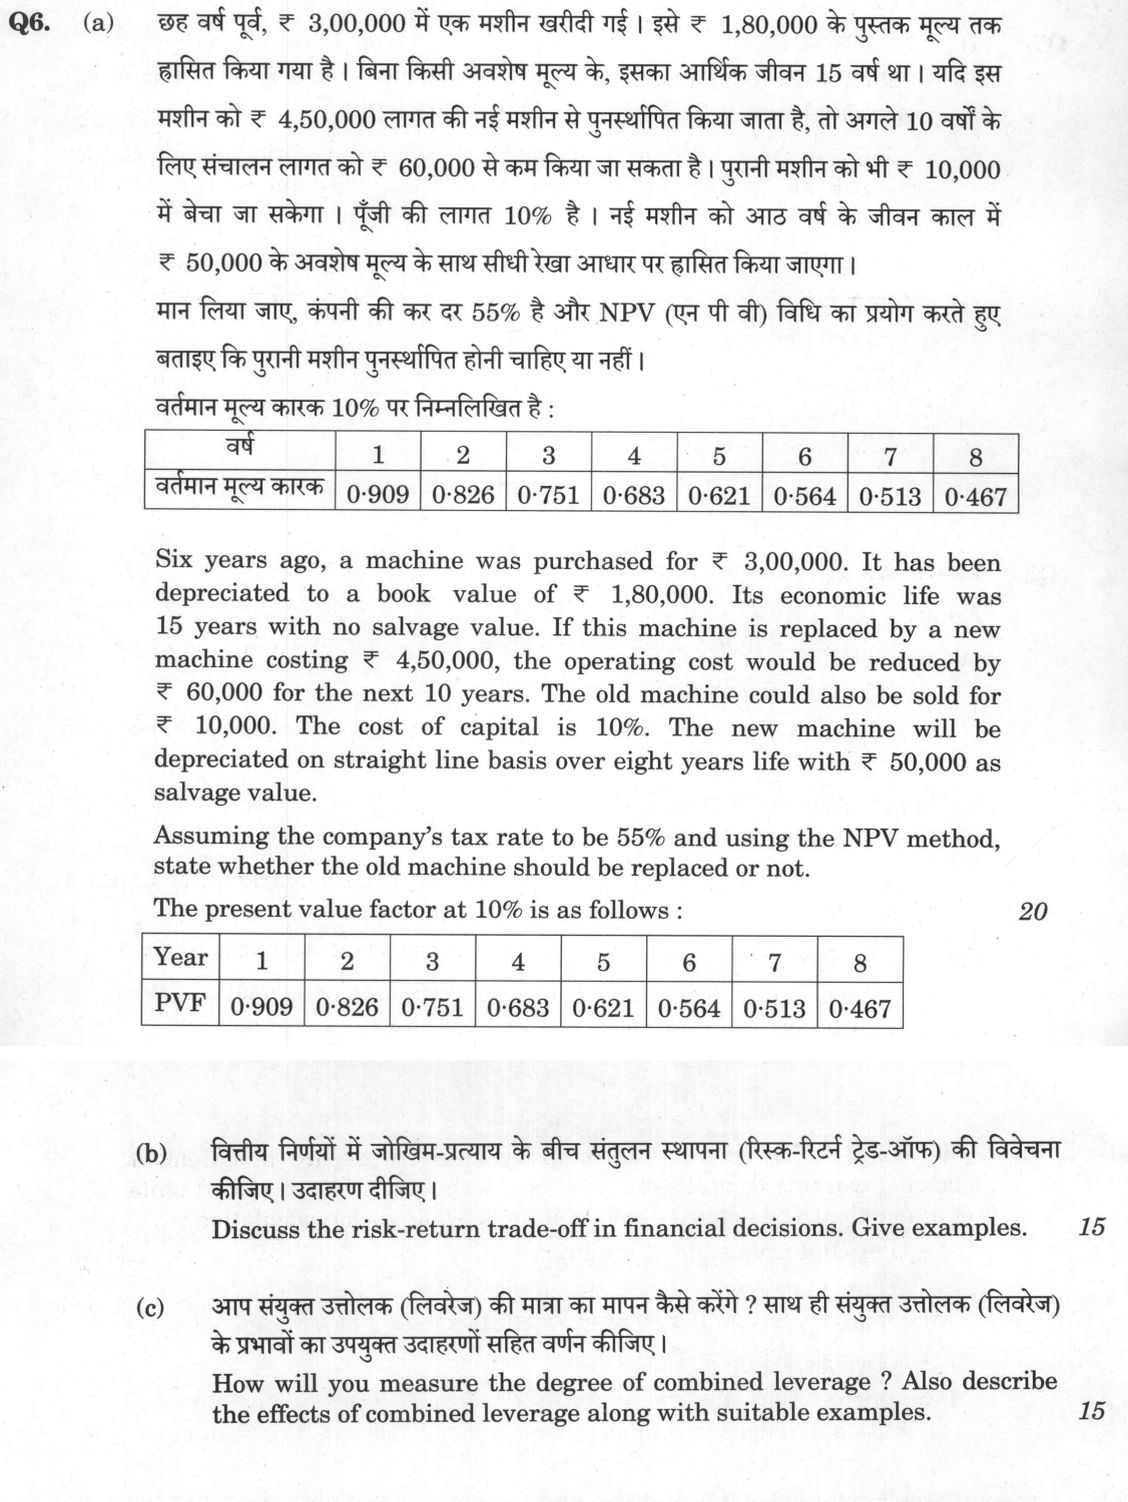
(a) Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a book value of ₹ 1,80,000. Its economic…
Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a book value of ₹ 1,80,000. Its economic life was 15 years with no salvage value. If this machine is replaced by a new machine costing ₹ 4,50,000, the operating cost would be reduced by ₹ 60,000 for the next 10 years. The old machine could also be sold for ₹ 10,000. The cost of capital is 10%. The new machine will be depreciated on straight line basis over eight years life with ₹ 50,000 as salvage value.
Assuming the company's tax rate to be 55% and using the NPV method, state whether the old machine should be replaced or not.
The present value factors at 10% are : - Year 1: 0·909; Year 2: 0·826; Year 3: 0·751; Year 4: 0·683 - Year 5: 0·621; Year 6: 0·564; Year 7: 0·513; Year 8: 0·467 20 marks
Discuss the risk-return trade-off in financial decisions. Give examples. 15 marks
How will you measure the degree of combined leverage ? Also describe the effects of combined leverage along with suitable examples. 15 marks
हिंदी में प्रश्न पढ़ें
(क) छह वर्ष पूर्व, ₹ 3,00,000 में एक मशीन खरीदी गई। इसे ₹ 1,80,000 के पुस्तक मूल्य तक ह्रासित किया गया है। बिना किसी अवशेष मूल्य के, इसका आर्थिक जीवन 15 वर्ष था। यदि इस मशीन को ₹ 4,50,000 लागत की नई मशीन से पुनर्स्थापित किया जाता है, तो अगले 10 वर्षों के लिए संचालन लागत को ₹ 60,000 से कम किया जा सकता है। पुरानी मशीन को भी ₹ 10,000 में बेचा जा सकेगा। पूँजी की लागत 10% है। नई मशीन को आठ वर्ष के जीवन काल में ₹ 50,000 के अवशेष मूल्य के साथ सीधी रेखा आधार पर ह्रासित किया जाएगा।
मान लिया जाए, कंपनी की कर दर 55% है और NPV (एन पी वी) विधि का प्रयोग करते हुए बताइए कि पुरानी मशीन पुनर्स्थापित होनी चाहिए या नहीं।
वर्तमान मूल्य कारक 10% पर निम्नलिखित हैं : - वर्ष 1: 0·909; वर्ष 2: 0·826; वर्ष 3: 0·751; वर्ष 4: 0·683 - वर्ष 5: 0·621; वर्ष 6: 0·564; वर्ष 7: 0·513; वर्ष 8: 0·467 (20 अंक)
(ख) वित्तीय निर्णयों में जोखिम-प्रत्याय के बीच संतुलन स्थापना (रिस्क-रिटर्न ट्रेड-ऑफ) की विवेचना कीजिए। उदाहरण दीजिए। (15 अंक)
(ग) आप संयुक्त उत्तोलक (लिवरेज) की मात्रा का मापन कैसे करेंगे ? साथ ही संयुक्त उत्तोलक (लिवरेज) के प्रभावों का उपयुक्त उदाहरणों सहित वर्णन कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Evaluation of Replacement Decision
To evaluate the replacement proposal, incremental cash flows are computed over the 8-year economic life of the new machine at a 10% discount rate. Although the question mentions savings for 10 years, only 8 years can be counted, because the new machine producing them lasts 8 years and PV factors are given only up to year 8. The loss on sale of the old machine is assumed to give an immediate tax saving, as in the usual textbook treatment.
The initial cash outlay involves the acquisition cost of the new machine of ₹4,50,000 less the salvage value of the old machine of ₹10,000 and the tax shield arising from the loss on sale of the old machine. The book value of the old machine is ₹1,80,000, yielding a capital loss of ₹1,70,000 (₹1,80,000 − ₹10,000). At a 55% tax rate, this generates a tax saving of ₹93,500 (₹1,70,000 × 0.55). Thus, Net Initial Outlay = ₹4,50,000 − ₹10,000 − ₹93,500 = ₹3,46,500.
Annual depreciation on the old machine is ₹20,000 (₹3,00,000 / 15 years), while annual straight-line depreciation for the new machine is ₹50,000 [(₹4,50,000 − ₹50,000) / 8 years], generating an incremental depreciation of ₹30,000. Annual Incremental Operating Cash Flow After Tax (CFAT for Years 1–8) is calculated as: CFAT = Δ Operating Savings × (1 - t) + Δ Depreciation × t CFAT = (₹60,000 × 0.45) + (₹30,000 × 0.55) = ₹27,000 + ₹16,500 = ₹43,500 per annum.
Cumulative PV factor (Years 1–8 at 10%) = 0.909 + 0.826 + 0.751 + 0.683 + 0.621 + 0.564 + 0.513 + 0.467 = 5.334. Present value of operating cash inflows = ₹43,500 × 5.334 = ₹2,32,029. Present value of terminal salvage value at Year 8 = ₹50,000 × 0.467 = ₹23,350. Total Present Value of Inflows = ₹2,32,029 + ₹23,350 = ₹2,55,379. Net Present Value (NPV) = ₹2,55,379 − ₹3,46,500 = -₹91,121.
Since the NPV is negative, the replacement proposal is financially unviable over the 8-year cycle. When adjusted for unequal lives (old machine having 9 remaining years versus 8 years for the new asset) via the Equivalent Annual Annuity (EAA) approach, the annualized loss confirms that retaining the existing machine is value-maximizing.
(b) Risk-Return Trade-Off in Financial Decisions
The risk-return trade-off dictates that higher expected returns necessitate assuming greater risk. In corporate financial management, this governs three core decisions: In capital structure decisions, debt financing lowers the weighted average cost of capital due to the interest tax shield under Section 36(1)(iii) of the Income Tax Act, but elevates financial risk and bankruptcy costs compared to conservative equity financing. In working capital management, an aggressive policy (maintaining minimal current assets financed through short-term debt) enhances profitability and Return on Capital Employed (ROCE) at the cost of severe liquidity risk, whereas a conservative policy holds excess liquid buffers, depressing returns. In capital budgeting and portfolio selection, total risk splits into systematic risk (market-wide, non-diversifiable) and unsystematic risk (firm-specific, diversifiable). Sectoral capital allocation in India reflects this: low-risk, asset-light IT firms (e.g., Infosys, TCS) command stable cash flows and moderate returns, whereas long-gestation infrastructure and power projects (e.g., Adani Ports, NTPC) carry higher systematic regulatory and demand risk, demanding higher hurdle rates.
(c) Measurement and Effects of Combined Leverage
Degree of Combined Leverage (DCL) measures the total sensitivity of earnings per share (EPS) to variations in sales revenue. It synthesises operating leverage (fixed operating costs) and financial leverage (fixed financing charges): DCL = Degree of Operating Leverage (DOL) × Degree of Financial Leverage (DFL) DCL = (% Change in EBIT)/(% Change in Sales) × (% Change in EPS)/(% Change in EBIT) = (% Change in EPS)/(% Change in Sales) = (Contribution)/(EBT)
Numerical illustration: sales Rs 10,00,000 less variable costs Rs 6,00,000 give a contribution of Rs 4,00,000; fixed operating costs are Rs 1,50,000 so EBIT is Rs 2,50,000, and interest of Rs 50,000 leaves EBT of Rs 2,00,000. Then DOL = 4,00,000/2,50,000 = 1.60, DFL = 2,50,000/2,00,000 = 1.25, and DCL = 1.60 x 1.25 = 4,00,000/2,00,000 = 2.0. A 10% rise in sales therefore lifts EPS by 20%, and a 10% fall cuts EPS by 20%.
Combined leverage acts as a two-way multiplier. A high DCL accelerates EPS growth rapidly when sales expand above the financial break-even point. Conversely, during demand contractions, high fixed operating and interest costs cause a steep drop in profitability, magnifying default risk.
In India, capital-intensive conglomerates such as Tata Steel and Reliance Industries, as well as telecom operators (e.g., Vodafone Idea), operate with high DCL due to heavy plant depreciation and high debt servicing. When capacity utilisation drops, these firms experience sharp drops in net earnings, demonstrating why firms with high operating leverage must temper their financial leverage to maintain solvency.
Verdict
On quantitative evaluation, the negative NPV of ₹91,121 establishes that the old machine should not be replaced. Strategically, corporate financial health requires maintaining an optimal leverage mix that balances tax shields against downside financial distress.
How this answer will be evaluated
What earns full marks: Complete workings, correct calculations, clear examples, precise terminology
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Using NPV at 10% and 55% tax, decide whether to replace the old machine with the new one. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Initial outlay: 4,50,000 − sale proceeds 10,000 − tax saving on loss (1,80,000 − 10,000) × 55% = 93,500 → ₹3,46,500
- Depreciation: old ₹20,000 p.a., new (4,50,000 − 50,000)/8 = ₹50,000; incremental ₹30,000
- CFAT = 60,000 × 0.45 + 30,000 × 0.55 = ₹43,500 for 8 years; PV = 43,500 × 5.334 = ₹2,32,029; salvage PV 50,000 × 0.467 = ₹23,350
- NPV = 2,55,379 − 3,46,500 = −₹91,121, so do not replace
Loses marks
- Ignoring tax effects of depreciation or of the loss on sale
- Counting 10 years of savings with an 8-year machine without comment
Earns more
- Explains using 8 years although savings are stated for 10
- States the assumption about the tax treatment of the loss on sale
Extra mark
- Mentions equivalent annual annuity for unequal lives
- (b) Discuss the risk-return trade-off in financial decisions with examples. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Concept: higher expected return requires bearing higher risk; decision seeks the best return for acceptable risk
- Financing decision: debt raises EPS/ROE through leverage but adds financial risk
- Working capital and investment decisions: aggressive vs conservative policies; project risk and hurdle rates
- Examples (Indian or general) and the implication for value maximisation
Loses marks
- Only defining risk and return without decisions
- No examples
Earns more
- Systematic vs unsystematic risk and diversification
- CAPM or risk-adjusted discount rate
Extra mark
- Numerical illustration of leverage effect on ROE
- (c) Explain how the degree of combined leverage is measured and describe its effects with examples. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- DCL = DOL × DFL = % change in EPS ÷ % change in sales = contribution ÷ EBT (PBT)
- DOL = contribution/EBIT (fixed operating costs); DFL = EBIT/EBT (fixed interest)
- Numerical example (e.g., contribution 4,00,000, EBIT 2,50,000, EBT 2,00,000: DOL 1.6, DFL 1.25, DCL 2)
- Effects: magnifies EPS changes both ways; high DOL should be paired with low DFL; business risk plus financial risk
Loses marks
- Adding DOL and DFL instead of multiplying
- No example
Earns more
- Industry examples (capital-intensive firms)
- Links to break-even point and risk of insolvency
Extra mark
- Preference dividend adjustment in DFL
What "Evaluate" is asking you to do
Judge how well something has performed against the standard it set for itself — its stated aim, mandate or promise — and commit to a verdict. Name the yardstick before you judge; an unanchored judgement reads as opinion.
Structure that answers it
Name the yardstick — stated aim, mandate or benchmark → performance against it → shortfall against it → why the gap exists → verdict
Where marks are lost
Presenting both sides and then declining to decide, or delivering a verdict against a standard you never stated, which makes it look arbitrary.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…
- Q5 Answer the following questions in about 150 words each : (10×5=50) (a) Define corporate r…
- Q6 (a) Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a b…
- Q7 (a) The Board of Directors of a company asks to prepare a statement showing working capit…
- Q8 (a) Explain the key classification of the Indian financial system. Make a diagram that de…