Paper I — Q4
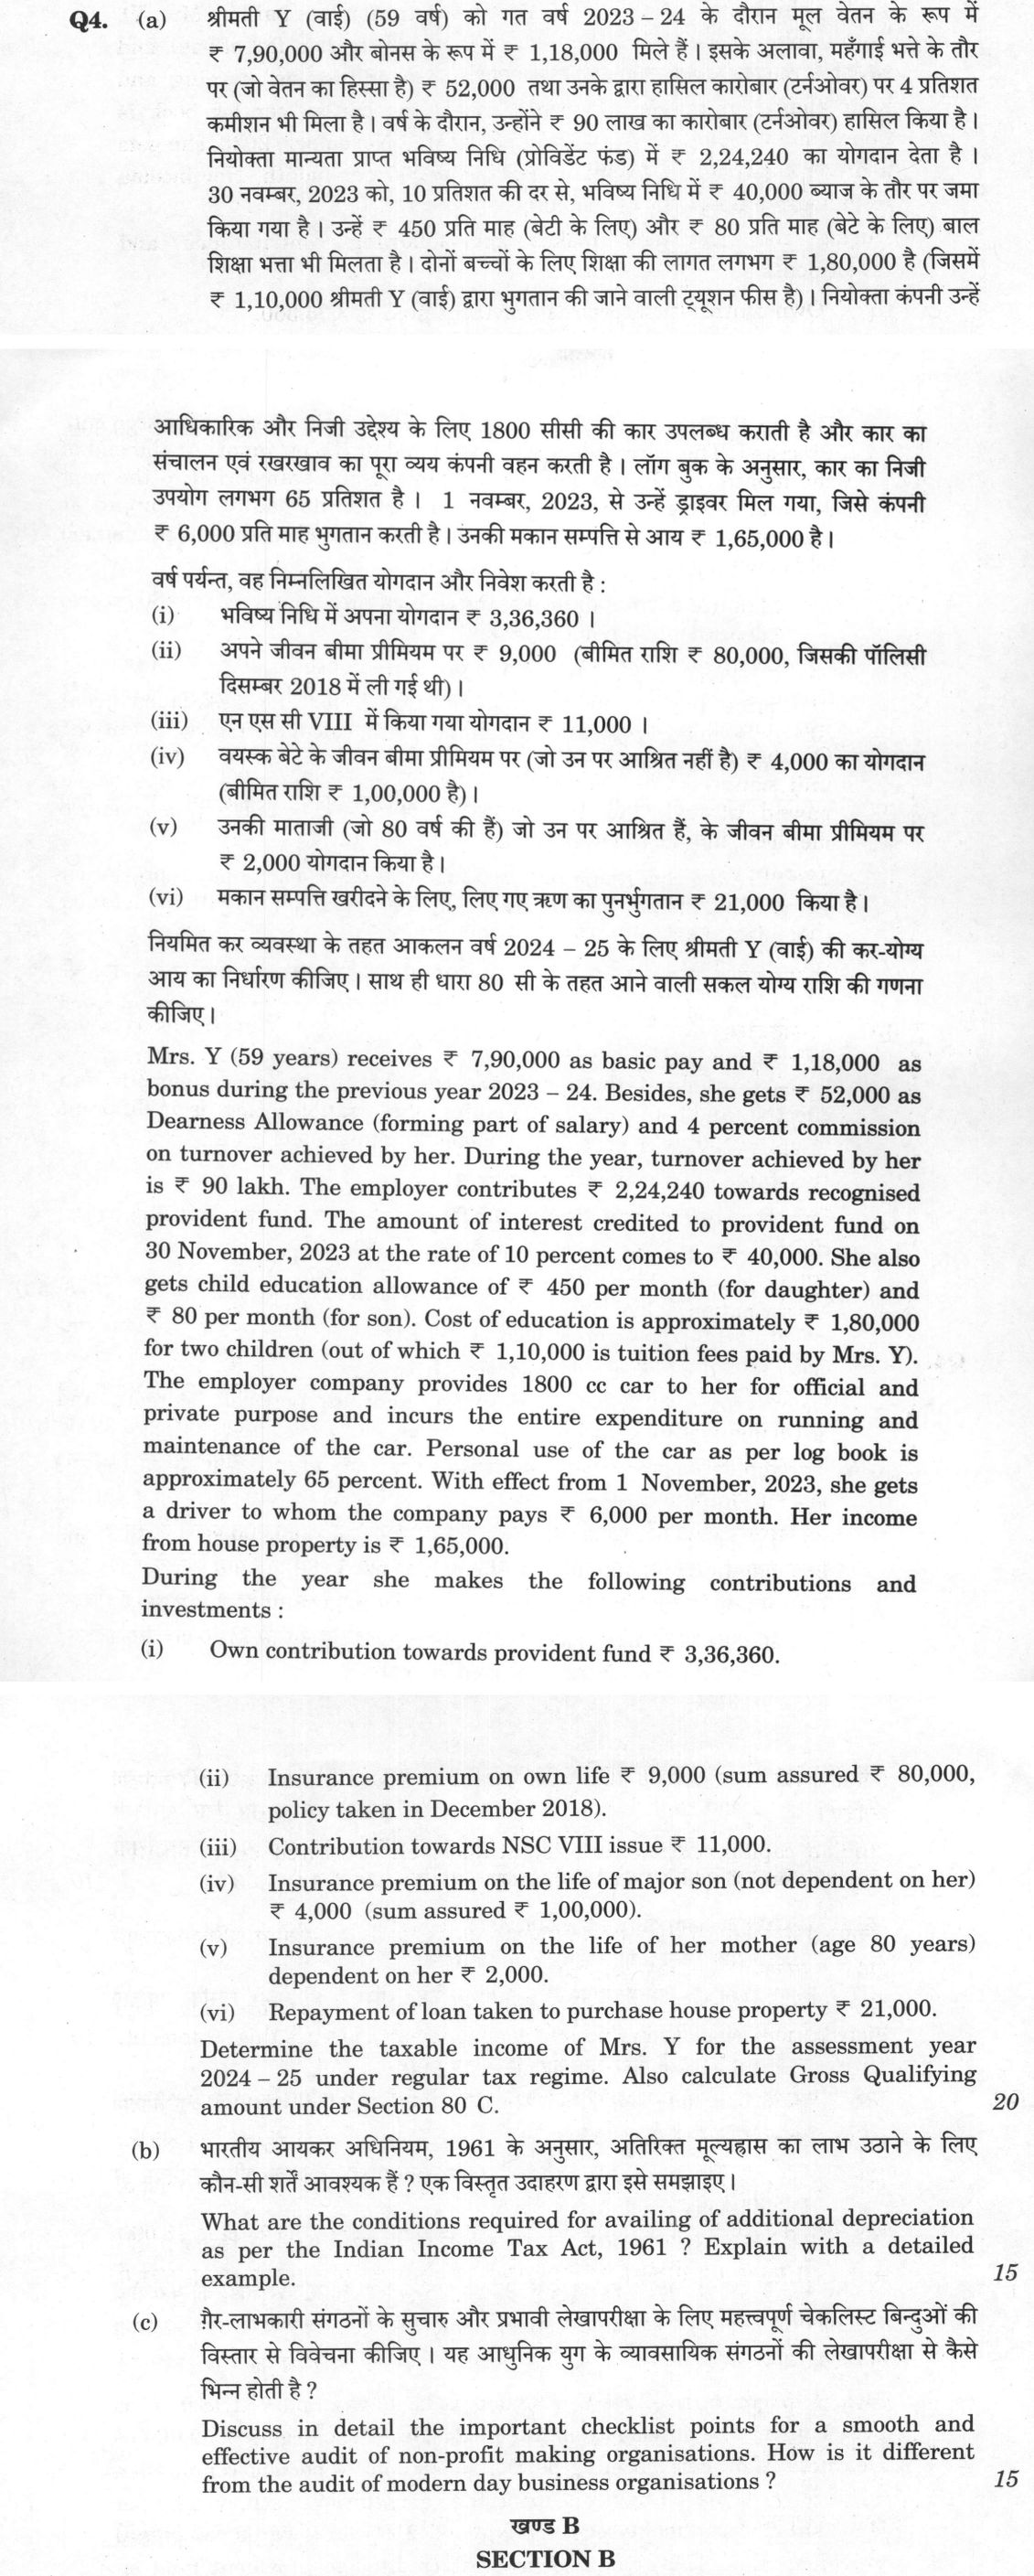
(a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the previous year 2023 – 24. Besides, she…
Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the previous year 2023 – 24. Besides, she gets ₹ 52,000 as Dearness Allowance (forming part of salary) and 4 percent commission on turnover achieved by her. During the year, turnover achieved by her is ₹ 90 lakh. The employer contributes ₹ 2,24,240 towards recognised provident fund. The amount of interest credited to provident fund on 30 November, 2023 at the rate of 10 percent comes to ₹ 40,000. She also gets child education allowance of ₹ 450 per month (for daughter) and ₹ 80 per month (for son). Cost of education is approximately ₹ 1,80,000 for two children (out of which ₹ 1,10,000 is tuition fees paid by Mrs. Y). The employer company provides 1800 cc car to her for official and private purpose and incurs the entire expenditure on running and maintenance of the car. Personal use of the car as per log book is approximately 65 percent. With effect from 1 November, 2023, she gets a driver to whom the company pays ₹ 6,000 per month. Her income from house property is ₹ 1,65,000. During the year she makes the following contributions and investments: (i) Own contribution towards provident fund ₹ 3,36,360; (ii) Insurance premium on own life ₹ 9,000 (sum assured ₹ 80,000, policy taken in December 2018); (iii) Contribution towards NSC VIII issue ₹ 11,000; (iv) Insurance premium on the life of major son (not dependent on her) ₹ 4,000 (sum assured ₹ 1,00,000); (v) Insurance premium on the life of her mother (age 80 years) dependent on her ₹ 2,000; (vi) Repayment of loan taken to purchase house property ₹ 21,000. Determine the taxable income of Mrs. Y for the assessment year 2024 – 25 under regular tax regime. Also calculate Gross Qualifying amount under Section 80 C. 20 marks
What are the conditions required for availing of additional depreciation as per the Indian Income Tax Act, 1961? Explain with a detailed example. 15 marks
Discuss in detail the important checklist points for a smooth and effective audit of non-profit making organisations. How is it different from the audit of modern day business organisations? 15 marks
हिंदी में प्रश्न पढ़ें
(क) श्रीमती Y (वाई) (59 वर्ष) को गत वर्ष 2023-24 के दौरान मूल वेतन के रूप में ₹ 7,90,000 और बोनस के रूप में ₹ 1,18,000 मिले हैं। इसके अलावा, महंगाई भत्ते के तौर पर (जो वेतन का हिस्सा है) ₹ 52,000 तथा उनके द्वारा हासिल कारोबार (टर्नओवर) पर 4 प्रतिशत कमीशन भी मिला है। वर्ष के दौरान, उन्होंने ₹ 90 लाख का कारोबार (टर्नओवर) हासिल किया है। नियोक्ता मान्यता प्राप्त भविष्य निधि (प्रोविडेंट फंड) में ₹ 2,24,240 का योगदान देता है। 30 नवंबर, 2023 को, 10 प्रतिशत की दर से, भविष्य निधि में ₹ 40,000 ब्याज के तौर पर जमा किया गया है। उन्हें ₹ 450 प्रति माह (बेटी के लिए) और ₹ 80 प्रति माह (बेटे के लिए) बाल शिक्षा भत्ता भी मिलता है। दोनों बच्चों के लिए शिक्षा की लागत लगभग ₹ 1,80,000 है (जिसमें ₹ 1,10,000 श्रीमती Y (वाई) द्वारा भुगतान की जाने वाली ट्यूशन फीस है)। नियोक्ता कंपनी उन्हें आधिकारिक और निजी उद्देश्य के लिए 1800 सीसी की कार उपलब्ध कराती है और कार का संचालन एवं रखरखाव का पूरा व्यय कंपनी वहन करती है। लॉग बुक के अनुसार, कार का निजी उपयोग लगभग 65 प्रतिशत है। 1 नवंबर, 2023, से उन्हें ड्राइवर मिल गया, जिसे कंपनी ₹ 6,000 प्रति माह भुगतान करती है। उनकी मकान संपत्ति से आय ₹ 1,65,000 है। वर्ष पर्यंत, वह निम्नलिखित योगदान और निवेश करती है: (i) भविष्य निधि में अपना योगदान ₹ 3,36,360; (ii) अपने जीवन बीमा प्रीमियम पर ₹ 9,000 (बीमित राशि ₹ 80,000, जिसकी पॉलिसी दिसंबर 2018 में ली गई थी); (iii) एन एस सी VIII में किया गया योगदान ₹ 11,000; (iv) वयस्क बेटे के जीवन बीमा प्रीमियम पर (जो उन पर आश्रित नहीं है) ₹ 4,000 का योगदान (बीमित राशि ₹ 1,00,000 है); (v) उनकी माताजी (जो 80 वर्ष की हैं) जो उन पर आश्रित हैं, के जीवन बीमा प्रीमियम पर ₹ 2,000 योगदान किया है; (vi) मकान संपत्ति खरीदने के लिए, लिए गए ऋण का पुनर्भुगतान ₹ 21,000 किया है। नियमित कर व्यवस्था के तहत आकलन वर्ष 2024 – 25 के लिए श्रीमती Y (वाई) की कर-योग्य आय का निर्धारण कीजिए। साथ ही धारा 80 सी के तहत आने वाली सकल योग्य राशि की गणना कीजिए। (20 अंक)
(ख) भारतीय आयकर अधिनियम, 1961 के अनुसार, अतिरिक्त मूल्यह्रास का लाभ उठाने के लिए कौन-सी शर्तें आवश्यक हैं? एक विस्तृत उदाहरण द्वारा इसे समझाइए। (15 अंक)
(ग) गैर-लाभकारी संगठनों के सुचारु और प्रभावी लेखापरीक्षा के लिए महत्वपूर्ण चेकलिस्ट बिन्दुओं की विस्तार से विवेचना कीजिए। यह आधुनिक युग के व्यावसायिक संगठनों की लेखापरीक्षा से कैसे भिन्न होती है? (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Taxable income of Mrs. Y for AY 2024‑25 (regular regime) and Gross Qualifying Amount under Section 80C
"Regular tax regime" is read as the old (normal) regime, since the question asks for the Section 80C deduction, which is not available under the default regime of Section 115BAC. The taxable income is obtained by first building the gross salary income under Section 17 (including the perquisites under Section 17(2)), adding the house‑property income to reach the Gross Total Income (GTI), and then deducting the Section 80C amount, which is the lesser of the Gross Qualifying Amount (GQA) and ₹1,50,000. The commission is 4% of the ₹90,00,000 turnover, i.e. ₹3,60,000. The recognised provident fund (RPF) base is basic pay plus DA plus commission (₹7,90,000 + ₹52,000 + ₹3,60,000 = ₹12,02,000); the employer's statutory 12% is ₹1,44,240, so the excess of the ₹2,24,240 actually contributed, namely ₹80,000, is taxable. The interest credited of ₹40,000 at 10% implies a fund balance of ₹4,00,000; the exempt interest at 9.5% is ₹38,000, leaving ₹2,000 taxable. Child education allowance received is (₹450 + ₹80) × 12 = ₹6,360, against an exemption of the lower of the allowance and ₹100 per child per month (₹1,200 for the daughter + ₹960 for the son = ₹2,160), so ₹4,200 is taxable. For the 1800 cc car, where the employer bears all running and maintenance costs, the perquisite is a flat ₹2,400 per month irrespective of the extent of personal use, i.e. ₹2,400 × 12 = ₹28,800. The driver, provided from 1 November 2023 (five months), is valued at ₹900 per month, i.e. ₹4,500. Total perquisite is therefore ₹33,300.
Computation of total income (₹)
- Basic pay: 7,90,000
- Bonus: 1,18,000
- Dearness allowance: 52,000
- Commission (4% of 90,00,000): 3,60,000
- Employer's RPF contribution in excess of 12% of salary: 80,000
- RPF interest in excess of 9.5%: 2,000
- Child education allowance, taxable part: 4,200
- Perquisite (car 28,800 + driver 4,500): 33,300
- Gross salary: 14,39,500
- Less: standard deduction u/s 16(ia): 50,000
- Income from salary: 13,89,500
- Income from house property: 1,65,000
- Gross Total Income: 15,54,500
For Section 80C, the eligible items are: own RPF ₹3,36,360; life insurance on self capped at 10% of the ₹80,000 sum assured, i.e. ₹8,000; NSC ₹11,000; life insurance on the son ₹4,000; housing‑loan principal ₹21,000; and tuition fees for two children ₹1,10,000. The premium on the mother is excluded because Section 80C covers only self, spouse and children (a child need not be dependent). The GQA is therefore ₹4,90,360, but the deduction is restricted to ₹1,50,000.
Conclusion: Taxable income = ₹15,54,500 − ₹1,50,000 = ₹14,04,500, and the Gross Qualifying Amount under Section 80C is ₹4,90,360 (deduction allowed ₹1,50,000).
(b) Conditions for additional depreciation under Section 32(1)(iia)
Additional depreciation is a one‑time incentive under Section 32(1)(iia) of the Income Tax Act, 1961, intended to encourage the adoption of new plant and machinery and the modernisation of industry; it permits an extra 20% depreciation on the actual cost of a new asset over and above the normal written‑down value (WDV) depreciation. The conditions that must be satisfied are: (i) the plant or machinery must be new, meaning it has not been used by any other person; (ii) it must be owned by the assessee who claims the depreciation; (iii) it must be installed and put to use during the relevant previous year; (iv) the assessee must be engaged in the manufacture or production of any article or thing, or in the generation, transmission or distribution of power, and the asset must be used in that business; (v) the incentive does not extend to ships, aircraft, office appliances or road‑transport vehicles; and (vi) where the asset is put to use for less than 180 days in the year of acquisition, additional depreciation is restricted to 10% of the actual cost in that year, and the balance 10% is allowed in the next year. It is also not allowed on second-hand machinery, machinery installed in an office or residential accommodation (including a guest house), or machinery whose whole cost is allowed as a deduction in one year, and it is not available to assessees opting for the concessional regimes under Sections 115BAA, 115BAB or 115BAC.
Detailed example. A manufacturing company purchases a new CNC machine for ₹50,00,000 and puts it to use on 1 October 2023, so it is used for six months (183 days, i.e. not less than 180 days) and is owned, new and installed. The additional depreciation is 20% of ₹50,00,000 = ₹10,00,000, claimed in full in that year. Normal WDV depreciation is computed separately on the actual cost of ₹50,00,000; at a 15% rate this gives 15% × ₹50,00,000 = ₹7,50,000. The total depreciation charge for the year is therefore ₹10,00,000 + ₹7,50,000 = ₹17,50,000, which is deducted from the business income and materially lowers the tax outgo while improving cash flow. Had the machine been used for only four months (under 180 days), the additional depreciation would have been only 10%, i.e. ₹5,00,000, in that year, with the remaining ₹5,00,000 claimed in the next year.
Conclusion: Additional depreciation is thus a conditional, front‑loaded relief that rewards the acquisition and early use of new, owned, business‑used plant and machinery, subject to the 180‑day rule and the listed exclusions.
(c) Audit checklist for non‑profit organisations and its contrast with business audit
The audit of a non‑profit making organisation (NPO) differs in purpose from a commercial audit because the entity exists to fulfil a charitable or social mission rather than to maximise profit; the auditor's central question is therefore whether the funds were applied to the objects for which they were received, not whether a true and fair profit was earned. A smooth and effective NPO audit should follow a structured checklist across several dimensions. First, the governing instrument and registrations: the auditor verifies the trust deed or memorandum of association and confirms compliance with its provisions, and checks the validity of the 12AB (income‑tax exemption) and 80G (donor‑deduction) registrations, since loss of either has direct tax consequences. Second, fund accounting and donor utilisation: the audit must distinguish restricted (earmarked) funds from unrestricted funds and trace that money received for a specific project was actually spent on that project, with supporting vouchers. Third, statutory and regulatory compliance: for NPOs receiving foreign contributions, compliance with the Foreign Contribution (Regulation) Act is examined, and it is ensured that at least 85% of the income is applied to charitable purposes as required by law, with any accumulation properly justified. Fourth, internal controls and documentation: the auditor reviews the bank reconciliations, the custody of securities, the authorisation of payments and the completeness of the records of donors and beneficiaries. Fifth, reporting: a trust or institution whose income before exemption exceeds the basic exemption limit must get its accounts audited and file the audit report in Form 10B or 10BB, and the auditor checks that anonymous donations, corpus donations and accumulations under Section 11(2) are correctly treated.
These points contrast sharply with the audit of a modern business organisation. In a business audit the objective is the true and fair view of profit and the going‑concern assumption, equity is examined as shareholders' funds, and performance is judged by return on investment and profit margins under commercial accounting standards. In an NPO audit, by contrast, the focus is on the application of funds and adherence to the trust deed, the balance sheet presents various funds and reserves held for specific causes rather than shareholder equity, and performance is measured by the impact of social programmes and the efficiency of fund utilisation, guided by the ICAI guidance notes on non‑profit entities rather than purely commercial standards.
Conclusion: An NPO audit is therefore a purpose‑driven, compliance‑heavy exercise centred on the correct application of restricted funds and statutory registrations, whereas a business audit is a profit‑ and equity‑centred exercise; a competent auditor must shift from a value‑creation mindset to a fund‑utilisation and accountability mindset when auditing a non‑profit.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Complete workings, correct statutory references, detailed examples, clear structure
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute Mrs. Y's taxable income for AY 2024-25 under the regular (old) regime and her gross qualifying amount under Section 80C. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Salary: basic 7,90,000 + bonus 1,18,000 + DA 52,000 + commission 3,60,000 (4% of ₹90 lakh)
- RPF: employer's excess over 12% of 12,02,000 = 80,000 taxable; interest excess over 9.5% = 2,000; CEA taxable 4,200 (₹100 per child per month exempt)
- Perquisites: car above 1.6 litres used partly for private purposes, expenses by employer, ₹2,400 × 12 = 28,800; driver ₹900 × 5 = 4,500; gross salary 14,39,500, less standard deduction 50,000
- GTI 15,54,500; 80C GQA 4,90,360 (own PF, LIC self capped at 8,000, NSC, son's policy, housing principal, tuition 1,10,000; mother excluded) restricted to 1,50,000; taxable income 14,04,500
Loses marks
- Taking the car perquisite on the 65% log-book basis
- Allowing the full ₹9,000 LIC premium or the mother's premium
Earns more
- States that 'regular regime' is read as the old regime because 80C is asked
- Explains why the mother's premium is excluded and the son's included
Extra mark
- Computes tax liability on ₹14,04,500
- (b) State the conditions for additional depreciation under Section 32(1)(iia) with a detailed example. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Assessee engaged in manufacture/production of an article or thing, or generation/transmission/distribution of power
- New plant or machinery acquired and installed after 31 March 2005, owned and put to use for that business
- Exclusions: ships, aircraft, second-hand machinery, office/residential installations, road transport vehicles, 100%-deduction assets; not under Sections 115BAA/115BAB/115BAC
- Rate 20% of actual cost; if used < 180 days, 10% in year one and balance 10% next year; worked example with normal plus additional depreciation
Loses marks
- Omitting the manufacturing/power condition
- Saying the balance 10% is lost when use is under 180 days
Earns more
- Example showing both the ≥180-day and <180-day cases
- Rate 35% for backward areas of AP, Telangana, Bihar and West Bengal (Section 32(1)(iia) proviso)
Extra mark
- Shows WDV carried forward after the first year
- (c) Discuss an audit checklist for non-profit organisations and how it differs from the audit of a business. 15 marks
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Constitution and registrations: trust deed/MoA objects, 12A/12AB and 80G validity, FCRA registration where relevant
- Receipts and funds: donations, grants, corpus and restricted funds traced to their use; anonymous donations; 85% application and accumulation
- Payments, fixed assets, internal controls, bank reconciliation and audit report in Form 10B/10BB
- Contrast with business audit: fund utilisation and compliance vs true and fair profit, fund balances vs shareholders' equity, different users
Loses marks
- Checklist without the business-audit contrast
- Generic audit points with no NPO specifics
Earns more
- Examples: school, hospital or NGO specific checks
- ICAI guidance on audit of NPOs or SA-based approach
Extra mark
- Mentions risks such as diversion of funds or related-party payments to trustees
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q1 Answer the following questions in about 150 words each : (10×5=50) (a) Briefly explain th…
- Q2 (a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 202…
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…
- Q5 Answer the following questions in about 150 words each : (10×5=50) (a) Define corporate r…
- Q6 (a) Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a b…
- Q7 (a) The Board of Directors of a company asks to prepare a statement showing working capit…