Paper I — Q3
(a) During the month of May 2024, total 2000 units were introduced into Process-I. The normal loss was estimated at 5% on input…
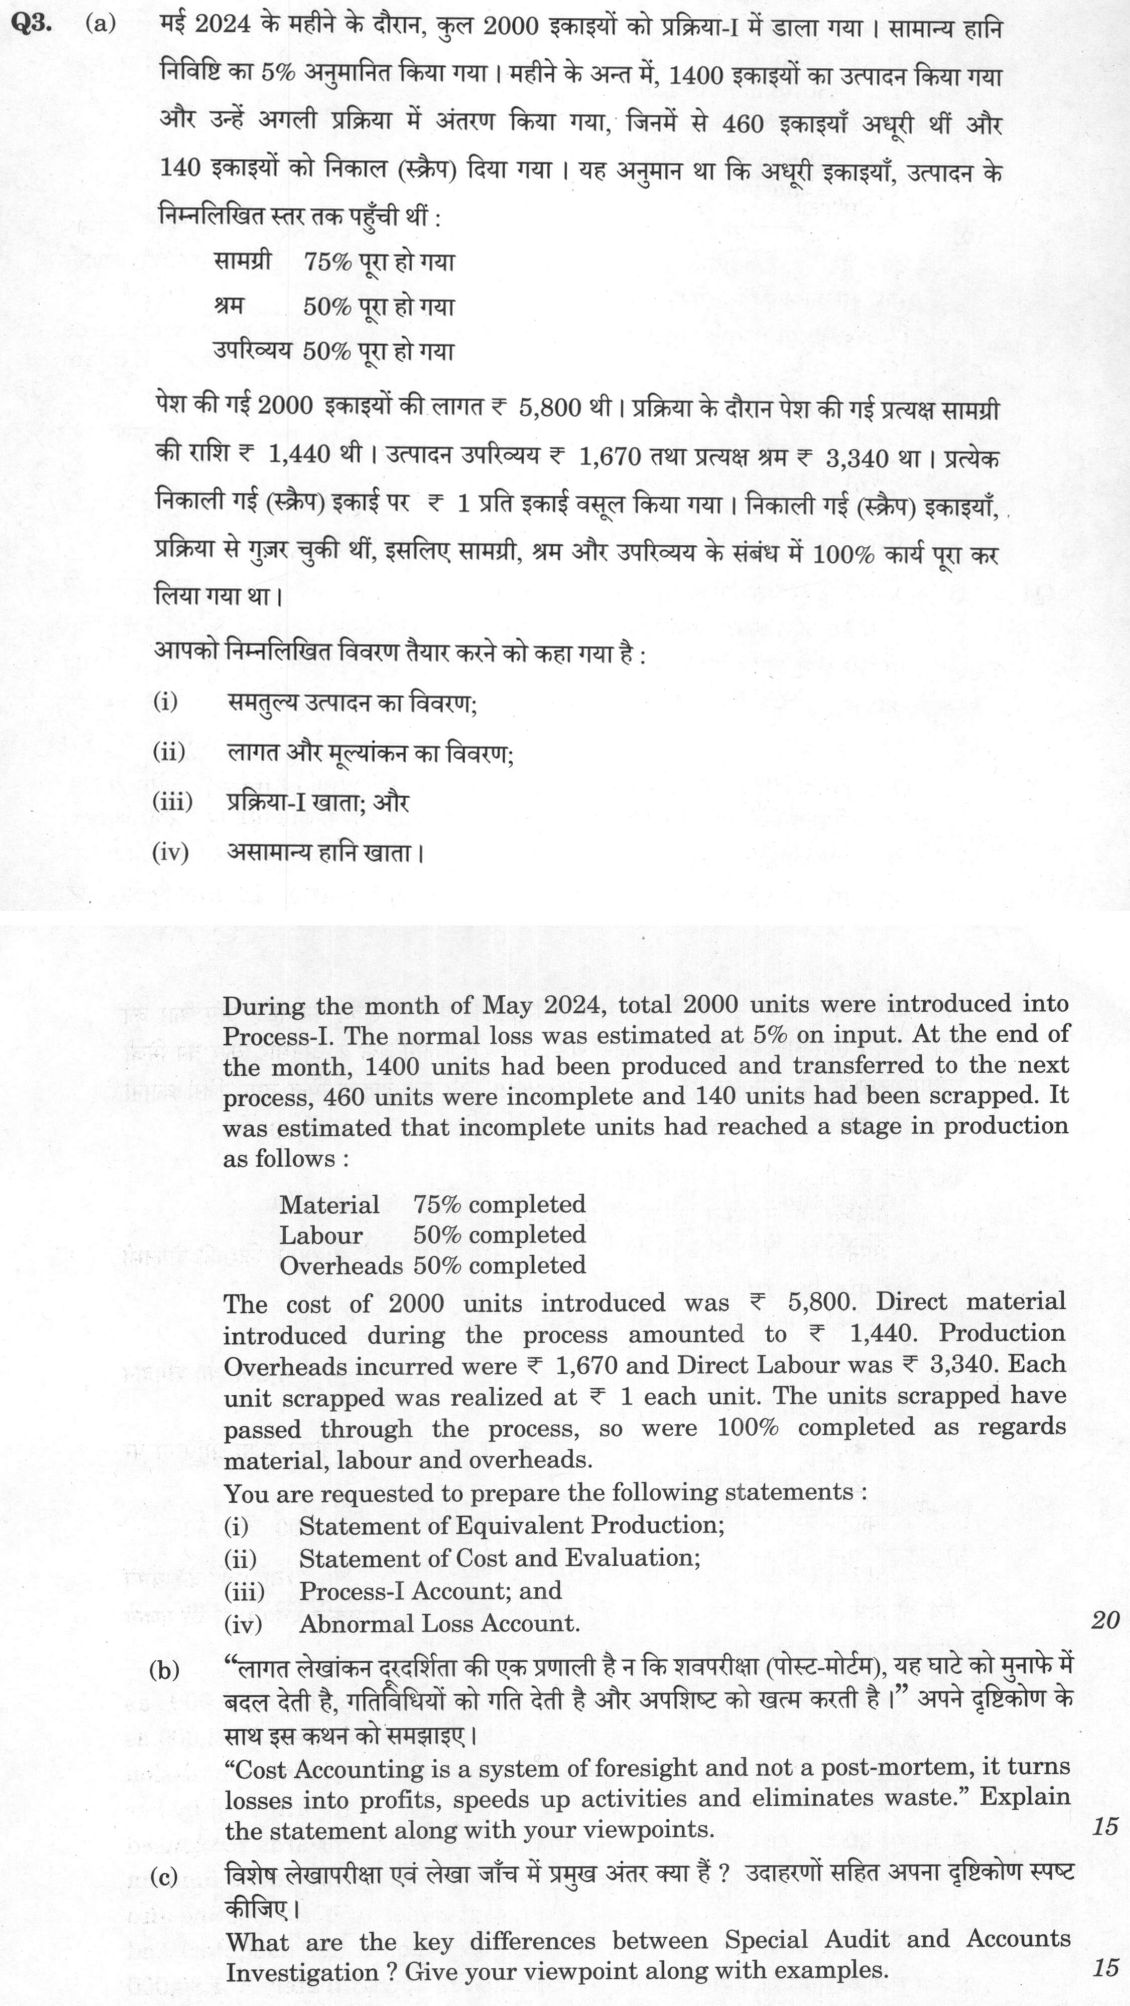
During the month of May 2024, total 2000 units were introduced into Process-I. The normal loss was estimated at 5% on input. At the end of the month, 1400 units had been produced and transferred to the next process, 460 units were incomplete and 140 units had been scrapped. It was estimated that incomplete units had reached a stage in production as follows: Material 75% completed, Labour 50% completed, Overheads 50% completed. The cost of 2000 units introduced was ₹ 5,800. Direct material introduced during the process amounted to ₹ 1,440. Production Overheads incurred were ₹ 1,670 and Direct Labour was ₹ 3,340. Each unit scrapped was realized at ₹ 1 each unit. The units scrapped have passed through the process, so were 100% completed as regards material, labour and overheads. You are requested to prepare the following statements: (i) Statement of Equivalent Production; (ii) Statement of Cost and Evaluation; (iii) Process-I Account; and (iv) Abnormal Loss Account. 20 marks
"Cost Accounting is a system of foresight and not a post-mortem, it turns losses into profits, speeds up activities and eliminates waste." Explain the statement along with your viewpoints. 15 marks
What are the key differences between Special Audit and Accounts Investigation? Give your viewpoint along with examples. 15 marks
हिंदी में प्रश्न पढ़ें
(क) मई 2024 के महीने के दौरान, कुल 2000 इकाइयों को प्रक्रिया-I में डाला गया। सामान्य हानि निविष्टि का 5% अनुमानित किया गया। महीने के अंत में, 1400 इकाइयों का उत्पादन किया गया और उन्हें अगली प्रक्रिया में अंतरण किया गया, जिनमें से 460 इकाइयाँ अधूरी थीं और 140 इकाइयों को निकाल (स्क्रैप) दिया गया। यह अनुमान था कि अधूरी इकाइयाँ, उत्पादन के निम्नलिखित स्तर तक पहुँची थीं: सामग्री 75% पूरा हो गया, श्रम 50% पूरा हो गया, उपरिव्यय 50% पूरा हो गया। पेश की गई 2000 इकाइयों की लागत ₹ 5,800 थी। प्रक्रिया के दौरान पेश की गई प्रत्यक्ष सामग्री की राशि ₹ 1,440 थी। उत्पादन उपरिव्यय ₹ 1,670 तथा प्रत्यक्ष श्रम ₹ 3,340 था। प्रत्येक निकाली गई (स्क्रैप) इकाई पर ₹ 1 प्रति इकाई वसूल किया गया। निकाली गई (स्क्रैप) इकाइयाँ, प्रक्रिया से गुजर चुकी थीं, इसलिए सामग्री, श्रम और उपरिव्यय के संबंध में 100% कार्य पूरा कर लिया गया था। आपको निम्नलिखित विवरण तैयार करने को कहा गया है: (i) समतुल्य उत्पादन का विवरण; (ii) लागत और मूल्यांकन का विवरण; (iii) प्रक्रिया-I खाता; और (iv) असामान्य हानि खाता। (20 अंक)
(ख) "लागत लेखांकन दूरदर्शिता की एक प्रणाली है न कि शवपरीक्षा (पोस्ट-मॉर्टम), यह घाटे को मुनाफे में बदल देती है, गतिविधियों को गति देती है और अपशिष्ट को खत्म करती है।" अपने दृष्टिकोण के साथ इस कथन को समझाइए। (15 अंक)
(ग) विशेष लेखापरीक्षा एवं लेखा जाँच में प्रमुख अंतर क्या हैं? उदाहरणों सहित अपना दृष्टिकोण स्पष्ट कीजिए। (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Normal loss = 5% × 2,000 = 100 units. Abnormal loss = actual scrapped 140 units − normal loss 100 units = 40 units.
(i) Statement of Equivalent Production
- Material: completed output 1,400 × 100% = 1,400; closing WIP 460 × 75% = 345; abnormal loss 40 × 100% = 40; total = 1,785 equivalent units (EU). Normal loss 100 units = nil EU.
- Labour: 1,400 + 230 (460 × 50%) + 40 = 1,670 EU.
- Overheads: same as labour = 1,670 EU.
(ii) Statement of Cost and Evaluation The cost of units introduced and the material added in the process are taken together as material (WIP 75% complete for material), as the data give one material stage of completion. Material cost = ₹5,800 + ₹1,440 = ₹7,240. Less: normal-loss scrap value = 100 units × ₹1 = ₹100. Net material cost = ₹7,140.
- Material cost per EU = 7,140 ÷ 1,785 = ₹4.00.
- Labour cost per EU = 3,340 ÷ 1,670 = ₹2.00.
- Overhead cost per EU = 1,670 ÷ 1,670 = ₹1.00. Total cost per fully completed unit = ₹4 + ₹2 + ₹1 = ₹7.00.
Evaluation:
- Transferred to next process: 1,400 × ₹7 = ₹9,800.
- Closing WIP: material 345 × ₹4 = ₹1,380; labour 230 × ₹2 = ₹460; overhead 230 × ₹1 = ₹230; total = ₹2,070.
- Abnormal loss: 40 × ₹7 = ₹280.
- Normal-loss scrap: 100 × ₹1 = ₹100. Check: 9,800 + 2,070 + 280 + 100 = ₹12,250.
(iii) Process-I Account Dr side:
- To Units introduced: ₹5,800
- To Direct material: ₹1,440
- To Direct labour: ₹3,340
- To Production overheads: ₹1,670 Total = ₹12,250
Cr side:
- By Normal loss: 100 units × ₹1 = ₹100
- By Abnormal loss A/c: 40 units × ₹7 = ₹280
- By Process-II A/c: 1,400 units × ₹7 = ₹9,800
- By Closing WIP A/c: 460 units = ₹2,070 Total = ₹12,250
(iv) Abnormal Loss Account Dr side:
- To Process-I A/c: 40 units × ₹7 = ₹280
Cr side:
- By Scrap realisation: 40 units × ₹1 = ₹40
- By Profit and Loss A/c: net abnormal loss = ₹240 Total = ₹280
(b) Cost accounting is not merely a record of past costs; it is a managerial system of foresight. Historical costing gives feedback, but standard costing, budgetary control, variance analysis, marginal costing, target costing and life-cycle costing help estimate costs before they are incurred. Thus it prevents losses rather than only explaining them after the event.
It turns losses into profits by identifying unprofitable products, processes, departments and orders; by fixing standards; and by taking corrective action on material, labour and overhead variances. For example, an adverse material-usage variance may show pilferage or defective material, prompting purchase or production correction.
It speeds up activities through process costing, operation costing, activity-based costing, just-in-time systems and throughput accounting. By locating bottlenecks and reducing cycle time, it improves capacity utilisation and delivery.
It eliminates waste by reporting scrap, spoilage, rework, idle time and abnormal loss. Value analysis, value engineering, lean accounting and Six Sigma use cost information to remove non-value-added activities.
Viewpoint: the statement is largely true for management accounting, but historical cost records remain the base. Foresight is useful only if data are timely, reliable and acted upon. Excessive cost-cutting can harm quality, employee morale and innovation. Hence cost accounting should support strategy, sustainability and ethical decision-making.
(c) Key differences between Special Audit and Accounts Investigation:
- Meaning and basis: Special audit is a statutory or specially ordered audit under a specific law, such as Section 142(2A) of the Income-tax Act, 1961. Accounts investigation is a fact-finding or forensic probe into suspected fraud, misstatement or misappropriation.
- Objective: Special audit gives an opinion on specified accounts, compliance or true and fair view. Investigation seeks to establish hidden facts, intent, responsibility and quantum of loss.
- Appointment: Special auditor is appointed by a government, tribunal or authority. Investigation may be ordered by the Central Government under Sections 210–213 of the Companies Act, 2013 (including by the SFIO under Section 212), or conducted by SEBI, tax authorities, police, forensic accountants or management.
- Scope: Special audit is usually limited to a specified period, unit or transaction. Investigation is wider and may examine bank accounts, e-mails, interviews, related parties and external evidence.
- Procedure: Special audit follows auditing standards and evidence rules. Investigation uses forensic, legal and investigative techniques.
- Reporting: Special audit report goes to the appointing authority. Investigation report may be used for prosecution, recovery or disciplinary action.
Examples: A special audit under Section 142(2A) of the Income-tax Act of an assessee’s accounts on the Assessing Officer’s direction; an SFIO investigation into accounting fraud, as in the Satyam case, or a SEBI investigation into insider trading.
Viewpoint: The two overlap because both examine accounts critically. A special audit may reveal issues that trigger an investigation, and an investigation often uses audit techniques. The main distinction lies in purpose, legal consequence and depth of enquiry.
How this answer will be evaluated
Framework: Process Costing (Equivalent Production Method)
What earns full marks: Part (a) has all 4 statements with correct workings; Parts (b) & (c) are well-structured with specific legal references and examples.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Prepare the statements of equivalent production and of cost and evaluation, the Process-I account and the abnormal loss account. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Normal loss 5% × 2,000 = 100 units; abnormal loss 140 − 100 = 40 units
- Equivalent production: material 1,400 + 345 + 40 = 1,785; labour and overheads 1,400 + 230 + 40 = 1,670
- Cost per EU: material (5,800 + 1,440 − 100)/1,785 = ₹4; labour 3,340/1,670 = ₹2; overheads 1,670/1,670 = ₹1; total ₹7
- Evaluation: transfer 9,800; closing WIP 2,070; abnormal loss 280; Process-I account totals ₹12,250; abnormal loss account: scrap 40, P&L 240
Loses marks
- Giving equivalent units to normal loss
- Crediting abnormal-loss scrap in the process account
Earns more
- Scrap value of normal loss deducted from material cost
- Abnormal loss valued like good units and fully complete
Extra mark
- Brief note on why normal loss gets no equivalent units
- (b) Explain, with your view, how cost accounting is a system of foresight that turns losses into profits, speeds up activities and eliminates waste. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Foresight: standard costing, budgetary control and marginal costing set costs before they are incurred
- Turning losses into profits: identifying unprofitable products, processes and orders; variance analysis and corrective action
- Speeding up activities and eliminating waste: bottlenecks, idle time, scrap and spoilage reporting, ABC, JIT, value analysis
- Own viewpoint: largely true but depends on timely reliable data, management action and not cutting costs at the expense of quality
Loses marks
- Only defining cost accounting without addressing the statement
- No personal viewpoint or critique
Earns more
- Concrete example (e.g., material usage variance revealing pilferage)
- Contrast with historical costing as post-mortem
Extra mark
- Link to target costing or life-cycle costing
- (c) Distinguish special audit from accounts investigation with examples and your view. 15 marks
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- Special audit: audit ordered under a specific law/authority for a specific purpose (e.g., Section 142(2A) Income-tax Act; RBI/CAG special audit)
- Investigation: fact-finding enquiry into suspected fraud or specific matters (e.g., Sections 210–213 Companies Act, SFIO, SEBI), possibly forensic
- Differences in objective (opinion vs establishing facts/responsibility), scope, appointing authority, procedure and use of the report
- Examples and a view that the two overlap: a special audit can trigger an investigation
Loses marks
- Treating the two as identical
- No examples
Earns more
- Investigation is not bound by a fixed period and has wider evidence sources
- Special audit follows auditing standards and gives a report to the appointing authority
Extra mark
- Mention of forensic accounting tools or a real case (e.g., Satyam, IL&FS)
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q1 Answer the following questions in about 150 words each : (10×5=50) (a) Briefly explain th…
- Q2 (a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 202…
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…
- Q5 Answer the following questions in about 150 words each : (10×5=50) (a) Define corporate r…
- Q6 (a) Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a b…