Paper I — Q2
(a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 2024 is as under : I – Equity and…
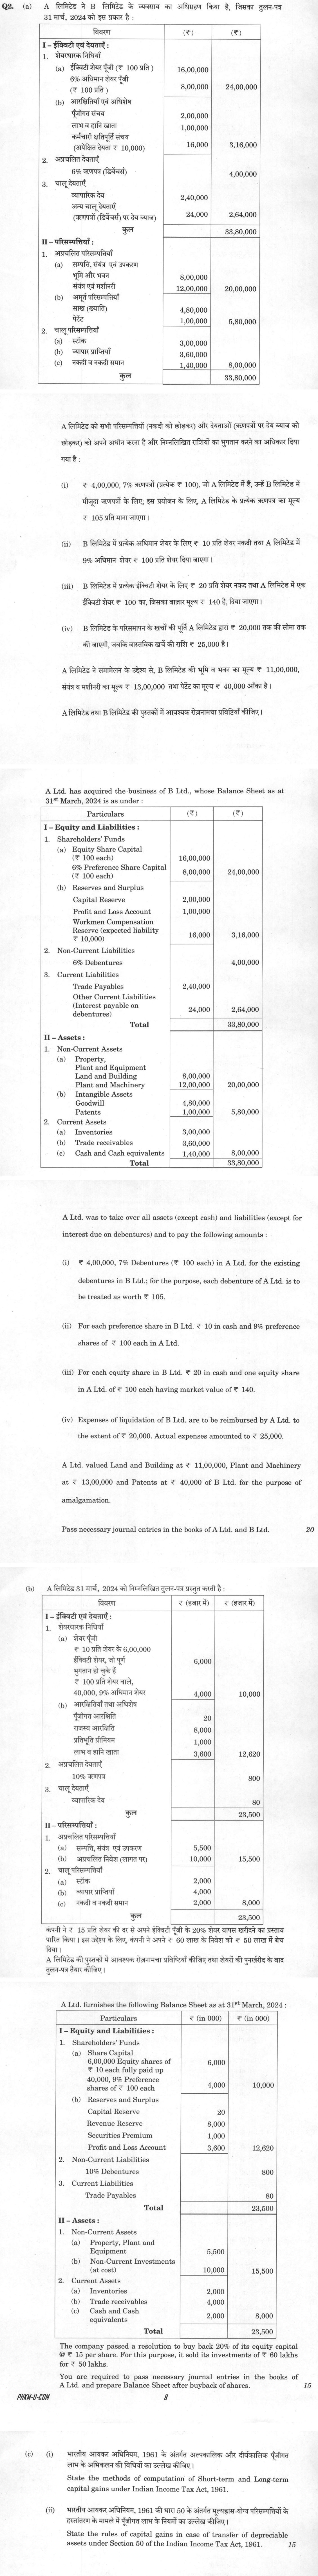
A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 2024 is as under :
I – Equity and Liabilities - Shareholders' Funds: Equity Share Capital (₹ 100 each) ₹ 16,00,000; 6% Preference Share Capital (₹ 100 each) ₹ 8,00,000; total ₹ 24,00,000 - Reserves and Surplus: Capital Reserve ₹ 2,00,000; Profit and Loss Account ₹ 1,00,000; Workmen Compensation Reserve (expected liability ₹ 10,000) ₹ 16,000; total ₹ 3,16,000 - Non-Current Liabilities: 6% Debentures ₹ 4,00,000 - Current Liabilities: Trade Payables ₹ 2,40,000; Other Current Liabilities (interest payable on debentures) ₹ 24,000; total ₹ 2,64,000 - Total ₹ 33,80,000
II – Assets - Property, Plant and Equipment: Land and Building ₹ 8,00,000; Plant and Machinery ₹ 12,00,000; total ₹ 20,00,000 - Intangible Assets: Goodwill ₹ 4,80,000; Patents ₹ 1,00,000; total ₹ 5,80,000 - Current Assets: Inventories ₹ 3,00,000; Trade receivables ₹ 3,60,000; Cash and cash equivalents ₹ 1,40,000; total ₹ 8,00,000 - Total ₹ 33,80,000
A Ltd. was to take over all assets (except cash) and liabilities (except for interest due on debentures) and to pay the following amounts : ₹ 4,00,000, 7% Debentures (₹ 100 each) in A Ltd. for the existing debentures in B Ltd.; for the purpose, each debenture of A Ltd. is to be treated as worth ₹ 105.
For each preference share in B Ltd. ₹ 10 in cash and 9% preference shares of ₹ 100 each in A Ltd.
For each equity share in B Ltd. ₹ 20 in cash and one equity share in A Ltd. of ₹ 100 each having market value of ₹ 140.
Expenses of liquidation of B Ltd. are to be reimbursed by A Ltd. to the extent of ₹ 20,000. Actual expenses amounted to ₹ 25,000.
A Ltd. valued Land and Building at ₹ 11,00,000, Plant and Machinery at ₹ 13,00,000 and Patents at ₹ 40,000 of B Ltd. for the purpose of amalgamation.
Pass necessary journal entries in the books of A Ltd. and B Ltd. 20 marks
A Ltd. furnishes the following Balance Sheet as at 31st March, 2024 (₹ in thousands) :
I – Equity and Liabilities - Share Capital: 6,00,000 equity shares of ₹ 10 each, fully paid up 6,000; 40,000 9% preference shares of ₹ 100 each 4,000; total 10,000 - Reserves and Surplus: Capital Reserve 20; Revenue Reserve 8,000; Securities Premium 1,000; Profit and Loss Account 3,600; total 12,620 - Non-Current Liabilities: 10% Debentures 800 - Current Liabilities: Trade Payables 80 - Total 23,500
II – Assets - Non-Current Assets: Property, Plant and Equipment 5,500; Non-current Investments (at cost) 10,000; total 15,500 - Current Assets: Stock 2,000; Trade Receivables 4,000; Cash and Cash Equivalents 2,000; total 8,000 - Total 23,500
The company passed a resolution to buy back 20% of its equity capital @ ₹ 15 per share. For this purpose, it sold its investments of ₹ 60 lakhs for ₹ 50 lakhs.
You are required to pass necessary journal entries in the books of A Ltd. and prepare Balance Sheet after buyback of shares. 15 marks
State the methods of computation of Short-term and Long-term capital gains under Indian Income Tax Act, 1961.
State the rules of capital gains in case of transfer of depreciable assets under Section 50 of the Indian Income Tax Act, 1961. 15 marks
हिंदी में प्रश्न पढ़ें
(क) A लिमिटेड ने B लिमिटेड के व्यवसाय का अधिग्रहण किया है, जिसका तुलन-पत्र 31 मार्च, 2024 को इस प्रकार है :
I – ईक्विटी एवं देयताएँ - शेयरधारक निधियाँ: ईक्विटी शेयर पूँजी (₹ 100 प्रति) ₹ 16,00,000; 6% अधिमान शेयर पूँजी (₹ 100 प्रति) ₹ 8,00,000; कुल ₹ 24,00,000 - आरक्षितियाँ एवं अधिशेष: पूँजीगत संचय ₹ 2,00,000; लाभ व हानि खाता ₹ 1,00,000; कर्मचारी क्षतिपूर्ति संचय (अपेक्षित देयता ₹ 10,000) ₹ 16,000; कुल ₹ 3,16,000 - अप्रचलित देयताएँ: 6% ऋणपत्र (डिबेंचर्स) ₹ 4,00,000 - चालू देयताएँ: व्यापारिक देय ₹ 2,40,000; अन्य चालू देयताएँ (ऋणपत्रों पर देय ब्याज) ₹ 24,000; कुल ₹ 2,64,000 - कुल ₹ 33,80,000
II – परिसम्पत्तियाँ - सम्पत्ति, संयंत्र एवं उपकरण: भूमि और भवन ₹ 8,00,000; संयंत्र एवं मशीनरी ₹ 12,00,000; कुल ₹ 20,00,000 - अमूर्त परिसम्पत्तियाँ: साख (ख्याति) ₹ 4,80,000; पेटेंट ₹ 1,00,000; कुल ₹ 5,80,000 - चालू परिसम्पत्तियाँ: स्टॉक ₹ 3,00,000; व्यापार प्राप्तियाँ ₹ 3,60,000; नकदी व नकदी समान ₹ 1,40,000; कुल ₹ 8,00,000 - कुल ₹ 33,80,000
A लिमिटेड को सभी परिसम्पत्तियों (नकदी को छोड़कर) और देयताओं (ऋणपत्रों पर देय ब्याज को छोड़कर) को अपने अधीन करना है और निम्नलिखित राशियों का भुगतान करना है : ₹ 4,00,000, 7% ऋणपत्रों (प्रत्येक ₹ 100), जो A लिमिटेड में हैं, उन्हें B लिमिटेड में मौजूदा ऋणपत्रों के लिए; इस प्रयोजन के लिए, A लिमिटेड के प्रत्येक ऋणपत्र का मूल्य ₹ 105 प्रति माना जाएगा।
B लिमिटेड में प्रत्येक अधिमान शेयर के लिए ₹ 10 प्रति शेयर नकदी तथा A लिमिटेड में 9% अधिमान शेयर ₹ 100 प्रति शेयर दिया जाएगा।
B लिमिटेड में प्रत्येक ईक्विटी शेयर के लिए ₹ 20 प्रति शेयर नकद तथा A लिमिटेड में एक ईक्विटी शेयर ₹ 100 का, जिसका बाज़ार मूल्य ₹ 140 है, दिया जाएगा।
B लिमिटेड के परिसमापन के खर्चों की पूर्ति A लिमिटेड द्वारा ₹ 20,000 तक की सीमा तक की जाएगी, जबकि वास्तविक खर्चे की राशि ₹ 25,000 है।
A लिमिटेड ने समामेलन के उद्देश्य से, B लिमिटेड की भूमि व भवन का मूल्य ₹ 11,00,000, संयंत्र व मशीनरी का मूल्य ₹ 13,00,000 तथा पेटेंट का मूल्य ₹ 40,000 आँका है।
A लिमिटेड तथा B लिमिटेड की पुस्तकों में आवश्यक रोज़नामचा प्रविष्टियाँ कीजिए। (20 अंक)
(ख) A लिमिटेड 31 मार्च, 2024 को निम्नलिखित तुलन-पत्र प्रस्तुत करती है (₹ हज़ार में) :
I – ईक्विटी एवं देयताएँ - शेयर पूँजी: ₹ 10 प्रति शेयर के 6,00,000 ईक्विटी शेयर, जो पूर्ण भुगतान हो चुके हैं 6,000; ₹ 100 प्रति शेयर वाले 40,000, 9% अधिमान शेयर 4,000; कुल 10,000 - आरक्षितियाँ तथा अधिशेष: पूँजीगत आरक्षिति 20; राजस्व आरक्षिति 8,000; प्रतिभूति प्रीमियम 1,000; लाभ व हानि खाता 3,600; कुल 12,620 - अप्रचलित देयताएँ: 10% ऋणपत्र 800 - चालू देयताएँ: व्यापारिक देय 80 - कुल 23,500
II – परिसम्पत्तियाँ - अप्रचलित परिसम्पत्तियाँ: सम्पत्ति, संयंत्र एवं उपकरण 5,500; अप्रचलित निवेश (लागत पर) 10,000; कुल 15,500 - चालू परिसम्पत्तियाँ: स्टॉक 2,000; व्यापार प्राप्तियाँ 4,000; नकदी व नकदी समान 2,000; कुल 8,000 - कुल 23,500
कंपनी ने ₹ 15 प्रति शेयर की दर से अपने ईक्विटी पूँजी के 20% शेयर वापस खरीदने का प्रस्ताव पारित किया। इस उद्देश्य के लिए, कंपनी ने अपने ₹ 60 लाख के निवेश को ₹ 50 लाख में बेच दिया।
A लिमिटेड की पुस्तकों में आवश्यक रोज़नामचा प्रविष्टियाँ कीजिए तथा शेयरों की पुनर्खरीद के बाद तुलन-पत्र तैयार कीजिए। (15 अंक)
(ग) (i) भारतीय आयकर अधिनियम, 1961 के अंतर्गत अल्पकालिक और दीर्घकालिक पूँजीगत लाभ के अभिकलन की विधियों का उल्लेख कीजिए।
भारतीय आयकर अधिनियम, 1961 की धारा 50 के अंतर्गत मूल्यह्रास-योग्य परिसम्पत्तियों के हस्तांतरण के मामले में पूँजीगत लाभ के नियमों का उल्लेख कीजिए। (15 अंक)
The figure this question refers to, in words
The question paper is a scan and the diagram did not survive as text. This is the figure as read from the original page — every component, value and label — so the question can be worked from the text below.
(a) Balance Sheet of B Ltd. as at 31st March, 2024:
I - Equity and Liabilities:
- Shareholders' Funds (a) Equity Share Capital (₹ 100 each): 16,00,000 6% Preference Share Capital (₹ 100 each): 8,00,000 Total (a): 24,00,000 (b) Reserves and Surplus Capital Reserve: 2,00,000 Profit and Loss Account: 1,00,000 Workmen Compensation Reserve (expected liability ₹ 10,000): 16,000 Total (b): 3,16,000
- Non-Current Liabilities 6% Debentures: 4,00,000
- Current Liabilities Trade Payables: 2,40,000 Other Current Liabilities (Interest payable on debentures): 24,000 Total (3): 2,64,000 Total Equity and Liabilities: 33,80,000
II - Assets:
- Non-Current Assets (a) Property, Plant and Equipment Land and Building: 8,00,000 Plant and Machinery: 12,00,000 Total (a): 20,00,000 (b) Intangible Assets Goodwill: 4,80,000 Patents: 1,00,000 Total (b): 5,80,000
- Current Assets (a) Inventories: 3,00,000 (b) Trade receivables: 3,60,000 (c) Cash and Cash equivalents: 1,40,000 Total (2): 8,00,000 Total Assets: 33,80,000
(b) Table titled 'A Ltd. furnishes the following Balance Sheet as at 31st March, 2024 :'. Columns are 'Particulars', '₹ (in 000)', '₹ (in 000)'.
I - Equity and Liabilities :
- Shareholders' Funds (a) Share Capital 6,00,000 Equity shares of ₹ 10 each fully paid up: 6,000 40,000, 9% Preference shares of ₹ 100 each: 4,000 Subtotal: 10,000 (b) Reserves and Surplus Capital Reserve: 20 Revenue Reserve: 8,000 Securities Premium: 1,000 Profit and Loss Account: 3,600 Subtotal: 12,620
- Non-Current Liabilities 10% Debentures: 800
- Current Liabilities Trade Payables: 80 Total: 23,500
II - Assets :
- Non-Current Assets (a) Property, Plant and Equipment: 5,500 (b) Non-Current Investments (at cost): 10,000 Subtotal: 15,500
- Current Assets (a) Inventories: 2,000 (b) Trade receivables: 4,000 (c) Cash and Cash equivalents: 2,000 Subtotal: 8,000 Total: 23,500
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Amalgamation of B Ltd. with A Ltd.
Method. B Ltd.'s equity shareholders receive cash as well as shares, so the conditions for an amalgamation in the nature of merger under AS 14 are not met. This is an amalgamation in the nature of purchase. A Ltd. records B Ltd.'s identifiable assets and liabilities at the agreed values; B Ltd.'s goodwill and reserves are not carried over. Of the workmen compensation reserve, only the expected liability of ₹10,000 is taken over. The debentures are a liability taken over and settled separately, so they are not part of the purchase consideration.
Purchase consideration
- Preference shareholders: 8,000 shares × (₹10 cash + one 9% preference share of ₹100) = ₹80,000 cash + ₹8,00,000 shares = ₹8,80,000
- Equity shareholders: 16,000 shares × (₹20 cash + one equity share worth ₹140) = ₹3,20,000 cash + ₹22,40,000 shares = ₹25,60,000
- Total = ₹34,40,000 (cash ₹4,00,000; shares ₹30,40,000)
Goodwill
- Assets taken over at agreed values: L&B 11,00,000 + P&M 13,00,000 + Patents 40,000 + Inventories 3,00,000 + Receivables 3,60,000 = ₹31,00,000
- Less liabilities taken over: Debentures 4,20,000 (4,000 × ₹105) + Trade payables 2,40,000 + Workmen compensation claim 10,000 = ₹6,70,000
- Net assets = ₹24,30,000
- Goodwill = 34,40,000 − 24,30,000 = ₹10,10,000, plus liquidation expenses reimbursed ₹20,000, so total goodwill = ₹10,30,000
Journal entries in the books of A Ltd.
- Business Purchase A/c Dr ₹34,40,000; To Liquidator of B Ltd. ₹34,40,000 (purchase consideration due)
- Land & Building A/c Dr ₹11,00,000; Plant & Machinery A/c Dr ₹13,00,000; Patents A/c Dr ₹40,000; Inventories A/c Dr ₹3,00,000; Trade Receivables A/c Dr ₹3,60,000; Goodwill A/c Dr ₹10,10,000; To Trade Payables A/c ₹2,40,000; To Provision for Workmen Compensation Claim A/c ₹10,000; To Debentureholders of B Ltd. A/c ₹4,20,000; To Business Purchase A/c ₹34,40,000
- Liquidator of B Ltd. Dr ₹34,40,000; To 9% Preference Share Capital A/c ₹8,00,000; To Equity Share Capital A/c ₹16,00,000; To Securities Premium A/c ₹6,40,000 (16,000 × ₹40); To Bank A/c ₹4,00,000
- Debentureholders of B Ltd. A/c Dr ₹4,20,000; To 7% Debentures A/c ₹4,00,000; To Securities Premium A/c ₹20,000
- Goodwill A/c Dr ₹20,000; To Bank A/c ₹20,000 (liquidation expenses of B Ltd. reimbursed)
Journal entries in the books of B Ltd.
- Realisation A/c Dr ₹32,40,000; To Land & Building ₹8,00,000; To Plant & Machinery ₹12,00,000; To Goodwill ₹4,80,000; To Patents ₹1,00,000; To Inventories ₹3,00,000; To Trade Receivables ₹3,60,000 (assets other than cash transferred)
- 6% Debentures A/c Dr ₹4,00,000; Trade Payables A/c Dr ₹2,40,000; To Realisation A/c ₹6,40,000 (liabilities taken over)
- Workmen Compensation Reserve A/c Dr ₹16,000; To Realisation A/c ₹10,000 (liability taken over); To Equity Shareholders A/c ₹6,000 (surplus)
- A Ltd. A/c Dr ₹34,40,000; To Realisation A/c ₹34,40,000 (purchase consideration)
- Interest Payable on Debentures A/c Dr ₹24,000; Realisation A/c Dr ₹25,000 (liquidation expenses); To Bank A/c ₹49,000
- Bank A/c Dr ₹20,000; To Realisation A/c ₹20,000 (expenses reimbursed by A Ltd.)
- Bank A/c Dr ₹4,00,000; 9% Preference Shares in A Ltd. A/c Dr ₹8,00,000; Equity Shares in A Ltd. A/c Dr ₹22,40,000; To A Ltd. A/c ₹34,40,000
- 6% Preference Share Capital A/c Dr ₹8,00,000; Realisation A/c Dr ₹80,000 (excess paid to preference shareholders); To Preference Shareholders A/c ₹8,80,000
- Preference Shareholders A/c Dr ₹8,80,000; To Bank A/c ₹80,000; To 9% Preference Shares in A Ltd. A/c ₹8,00,000
- Equity Share Capital A/c Dr ₹16,00,000; Capital Reserve A/c Dr ₹2,00,000; Profit & Loss A/c Dr ₹1,00,000; To Equity Shareholders A/c ₹19,00,000
- Realisation A/c Dr ₹7,65,000; To Equity Shareholders A/c ₹7,65,000 (profit on realisation)
- Equity Shareholders A/c Dr ₹26,71,000; To Bank A/c ₹4,31,000 (3,20,000 + 1,11,000); To Equity Shares in A Ltd. A/c ₹22,40,000
Checks
- Realisation profit: credits 6,40,000 + 10,000 + 34,40,000 + 20,000 = 41,10,000; debits 32,40,000 + 25,000 + 80,000 = 33,45,000; profit ₹7,65,000.
- B Ltd.'s cash: 1,40,000 − 49,000 + 20,000 + 4,00,000 − 80,000 − 4,31,000 = 0. The ₹5,000 of liquidation expenses not reimbursed is borne by the equity shareholders.
(b) Buy-back of equity shares by A Ltd. (figures in ₹ '000 unless stated)
Workings
- Shares bought back: 20% × 6,00,000 = 1,20,000 shares; consideration 1,20,000 × ₹15 = 1,800 (face value 1,200 + premium 600).
- Investments of 6,000 sold for 5,000, so the loss of 1,000 is charged to Profit and Loss (P&L falls from 3,600 to 2,600).
- Section 68 tests: buy-back (1,800) is within 25% of paid-up capital plus free reserves = 25% × (10,000 + 11,600) = 5,400 (free reserves = revenue reserve 8,000 + securities premium 1,000 + P&L 2,600; capital reserve is excluded); the shares bought back (20%) are within 25% of paid-up equity capital; after the buy-back, debt (800) is far below twice the capital and free reserves. The buy-back needs a special resolution because it exceeds 10%.
- The premium of 600 is charged to Securities Premium, and under Section 69 a sum equal to the nominal value bought back (1,200) is transferred from Revenue Reserve to Capital Redemption Reserve.
Journal entries (₹)
- Bank A/c Dr 50,00,000; Profit & Loss A/c Dr 10,00,000 (loss on sale); To Non-current Investments A/c 60,00,000
- Equity Share Capital A/c Dr 12,00,000; Securities Premium A/c Dr 6,00,000; To Equity Shareholders A/c 18,00,000 (1,20,000 shares at ₹15)
- Equity Shareholders A/c Dr 18,00,000; To Bank A/c 18,00,000
- Revenue Reserve A/c Dr 12,00,000; To Capital Redemption Reserve A/c 12,00,000
Balance Sheet of A Ltd. after buy-back (₹ '000)
I. Equity and Liabilities
- Share capital: 4,80,000 equity shares of ₹10 each = 4,800; 40,000 9% preference shares of ₹100 each = 4,000; total 8,800
- Reserves and surplus: Capital Reserve 20; Capital Redemption Reserve 1,200; Revenue Reserve 6,800; Securities Premium 400; Profit & Loss 2,600; total 11,020
- Non-current liabilities: 10% Debentures 800
- Current liabilities: Trade Payables 80
- Total 20,700
II. Assets
- Non-current assets: Property, plant and equipment 5,500; Non-current investments 4,000; total 9,500
- Current assets: Inventories 2,000; Trade receivables 4,000; Cash and cash equivalents 5,200; total 11,200
- Total 20,700
Check: cash 2,000 + 5,000 − 1,800 = 5,200; total 23,500 − 1,000 − 1,800 = 20,700.
(c) Capital gains under the Income-tax Act, 1961
(i) Methods of computing short-term and long-term capital gains
Classification (Section 2(42A)). For transfers on or after 23 July 2024, an asset is short-term if held for not more than 12 months (listed securities and equity-oriented fund units) or 24 months (all other assets); earlier the limits were 12, 24 or 36 months.
Short-term capital gain (Section 48) = full value of consideration − (cost of acquisition + cost of improvement + expenses on transfer), without indexation. STCG on STT-paid listed equity is taxed at 20% under Section 111A (15% for transfers before 23 July 2024); other STCG is taxed at normal slab rates.
Long-term capital gain uses the same formula, with these differences:
- Indexation (transfers before 23 July 2024): indexed cost = cost × CII of the year of transfer ÷ CII of the year of acquisition (or of 2001-02, where fair market value on 1 April 2001 may be taken as cost for older assets).
- From 23 July 2024: no indexation and tax at 12.5% under Section 112. Resident individuals and HUFs transferring land or buildings acquired before that date may choose 20% with indexation instead.
- Listed equity (Section 112A): 12.5% on gains above ₹1.25 lakh a year, with cost grandfathered to the value on 31 January 2018.
- Exemptions under Sections 54, 54B, 54EC and 54F are available for reinvested gains, and Section 49 takes the previous owner's cost for gifted or inherited assets.
(ii) Section 50: transfer of depreciable assets
For an asset forming part of a block of assets on which depreciation has been allowed, the written down value replaces the cost of acquisition:
- Block continues: if the consideration for assets transferred during the year exceeds the aggregate of (expenses on transfer + opening WDV of the block + actual cost of assets added during the year), the excess is deemed short-term capital gain.
- Block ceases to exist (all assets in it transferred): the consideration minus that aggregate is a short-term capital gain, or a short-term capital loss if negative.
- Otherwise no capital gain arises; the WDV of the block is reduced and depreciation continues on the balance.
Such a gain is always short-term, whatever the holding period, and indexation is not allowed, because depreciation has already given relief for the cost. Goodwill of a business is not a depreciable asset from AY 2021-22 and is dealt with outside the block.
How this answer will be evaluated
Framework: Amalgamation (Purchase Method) & Share Buyback
What earns full marks: Accurate journal entries with correct values; precise application of Section 50 and CRR rules.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Pass journal entries in the books of A Ltd. (transferee) and B Ltd. (transferor) for an amalgamation in the nature of purchase. 20 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Purchase consideration: preference 8,000 × ₹110 = ₹8,80,000 and equity 16,000 × ₹160 = ₹25,60,000, total ₹34,40,000 (debentures excluded)
- A Ltd.: assets at agreed values (L&B 11,00,000; P&M 13,00,000; Patents 40,000; stock 3,00,000; receivables 3,60,000), liabilities taken over (payables 2,40,000; WC claim 10,000; debentures 4,20,000) and goodwill ₹10,10,000
- A Ltd.: discharge of consideration (9% preference 8,00,000; equity 16,00,000 + premium 6,40,000; cash 4,00,000), debentures at ₹105 (premium 20,000) and ₹20,000 liquidation expenses debited to goodwill
- B Ltd.: Realisation account entries, interest and expenses paid, reimbursement received, shareholders' accounts closed; realisation profit ₹7,65,000
Loses marks
- Carrying B Ltd.'s goodwill or reserves into A Ltd.'s books
- Including debentures in purchase consideration without comment, or ignoring agreed asset values
Earns more
- States why this is purchase (cash paid to equity holders) under AS 14
- Treats the ₹6,000 surplus of workmen compensation reserve and the ₹5,000 unreimbursed expenses correctly
Extra mark
- Shows that B Ltd.'s cash account closes at zero
- (b) Pass journal entries for the buy-back of 20% equity at ₹15 and prepare the Balance Sheet after buy-back. 15 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- Sale of investments (6,000 for 5,000, ₹ '000) with loss of 1,000 charged to Profit and Loss
- Buy-back of 1,20,000 shares: capital 1,200 + premium 600 = 1,800 paid to shareholders
- Transfer of 1,200 (nominal value) from free reserves to Capital Redemption Reserve under Section 69
- Balance Sheet after buy-back: share capital 8,800, reserves 11,020, total 20,700; Section 68 limits checked
Loses marks
- Not creating Capital Redemption Reserve
- Omitting the loss on sale of investments
Earns more
- Correct free reserves (capital reserve excluded) for the 25% limit
- Special resolution needed as buy-back exceeds 10%
Extra mark
- Debt-equity ratio test after buy-back shown
- (c) State the computation of short-term and long-term capital gains and the Section 50 rules for depreciable assets. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Holding periods under Section 2(42A): 12 months for listed securities, 24 months for others (transfers from 23 July 2024)
- Computation (Section 48): full value of consideration less cost of acquisition, cost of improvement and transfer expenses; indexation only for pre-23 July 2024 LTCG (and the land/building option)
- Rates: Section 111A 20%, Section 112 12.5%, Section 112A 12.5% above ₹1.25 lakh; exemptions under Sections 54/54EC/54F
- Section 50: WDV replaces cost; excess over opening WDV plus additions and transfer expenses is deemed STCG; block ceasing gives STCG/STCL; always short-term, no indexation
Loses marks
- Old holding periods/rates without noting the 2024 changes
- Treating Section 50 gain as long-term
Earns more
- Cost of acquisition for gifted/inherited assets (Section 49) or FMV on 1 April 2001
- Goodwill of business excluded from the block from AY 2021-22
Extra mark
- Numerical illustration of Section 50
What "Solve" is asking you to do
Choose the method, then carry it through to a final answer. Identifying what kind of problem this is and why that method applies is the first thing marked; a correct figure arrived at invisibly earns almost nothing.
Structure that answers it
Given data and what is required → method chosen, with the reason it applies → set-up (equation, circuit, free body, trial balance) → working, step by step → answer with units and any condition of validity
Where marks are lost
Doing the middle steps mentally and writing only the result. In mathematics papers, a further loss comes from giving a decimal where the exact value in surds or fractions was wanted, or from skipping the justification a part explicitly asks for.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q1 Answer the following questions in about 150 words each : (10×5=50) (a) Briefly explain th…
- Q2 (a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 202…
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…
- Q5 Answer the following questions in about 150 words each : (10×5=50) (a) Define corporate r…