Paper I — Q1
(a) Briefly explain the significance of Accounting Standard-7 (AS-7). (10 marks) (b) Explain why the companies issue right…
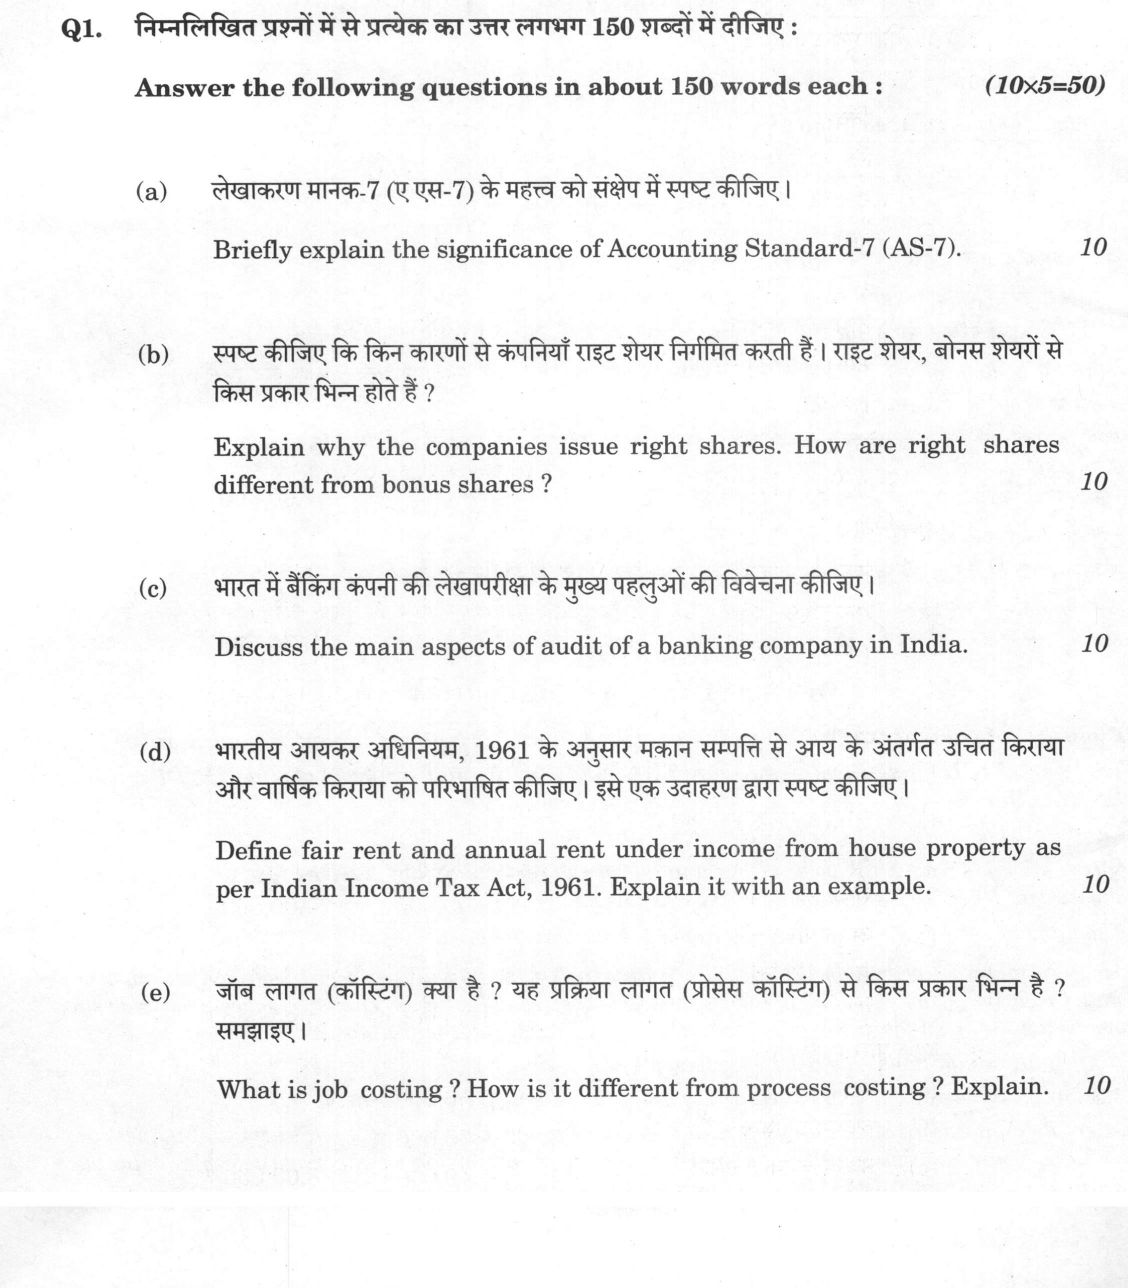
Answer the following questions in about 150 words each : (10×5=50)
Briefly explain the significance of Accounting Standard-7 (AS-7). 10 marks
Explain why the companies issue right shares. How are right shares different from bonus shares ? 10 marks
Discuss the main aspects of audit of a banking company in India. 10 marks
Define fair rent and annual rent under income from house property as per Indian Income Tax Act, 1961. Explain it with an example. 10 marks
What is job costing ? How is it different from process costing ? Explain. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए : (10×5=50)
(क) लेखाकरण मानक-7 (ए एस-7) के महत्व को संक्षेप में स्पष्ट कीजिए। (10 अंक)
(ख) स्पष्ट कीजिए कि किन कारणों से कंपनियाँ राइट शेयर निर्गमित करती हैं। राइट शेयर, बोनस शेयरों से किस प्रकार भिन्न होते हैं ? (10 अंक)
(ग) भारत में बैंकिंग कंपनी की लेखापरीक्षा के मुख्य पहलुओं की विवेचना कीजिए। (10 अंक)
(घ) भारतीय आयकर अधिनियम, 1961 के अनुसार मकान सम्पत्ति से आय के अंतर्गत उचित किराया और वार्षिक किराया को परिभाषित कीजिए। इसे एक उदाहरण द्वारा स्पष्ट कीजिए। (10 अंक)
(ङ) जॉब लागत (कॉस्टिंग) क्या है ? यह प्रक्रिया लागत (प्रोसेस कॉस्टिंग) से किस प्रकार भिन्न है ? समझाइए। (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Significance of Accounting Standard-7 (AS-7)
Accounting Standard-7 (revised), issued by the Institute of Chartered Accountants of India (ICAI), governs the accounting treatment for construction contracts in the financial statements of contractors. Because construction activities typically span across multiple accounting periods, the standard addresses the challenge of periodic allocation of contract revenue and contract costs.
AS-7 mandates the Percentage of Completion Method (PoCM) for revenue recognition when the outcome of a construction contract can be estimated reliably. Under PoCM, contract revenue and associated costs are recognized in the profit and loss statement in proportion to the stage of completion of the contract activity, strictly discarding the Completed Contract Method. The stage of completion is determined by contract costs incurred to date relative to estimated total costs, surveys of work performed, or physical completion. Furthermore, if total contract costs are expected to exceed total contract revenue, the anticipated loss must be recognized immediately as an expense. AS-7 mandates extensive disclosures, including aggregate costs incurred, recognized profits, advances received, and gross amounts due from or to customers, ensuring transparency and preventing revenue manipulation in long-term infrastructural and commercial projects. AS-7 applies to entities following the Companies (Accounting Standards) Rules; companies under Ind AS now account for such contracts under Ind AS 115, which likewise recognises revenue over time as performance obligations are satisfied.
(b) Right Shares: Objectives and Distinction from Bonus Shares
Under Section 62 of the Companies Act, 2013, a company issues right shares to raise fresh equity capital while preserving the pre-emptive rights of existing equity shareholders. Companies issue right shares because it enables capital mobilization without diluting the existing control, voting power, or proportionate shareholding of existing investors. Moreover, right shares are typically offered at a discount to the prevailing market price, reducing issue underwriting expenses and floatation costs.
Right shares fundamentally differ from bonus shares across key parameters:
Capital Infusion and Consideration: Right shares represent a fresh infusion of cash capital by existing shareholders at a specified price. Conversely, bonus shares under Section 63 involve no cash inflow, as they are issued free of cost through the capitalization of free reserves, securities premium, or the capital redemption reserve.
Shareholders' Discretion: A shareholder receiving a right offer can subscribe, reject, or renounce the right in favour of another person. Bonus shares are credited automatically to the demat account without any renunciation option.
Regulatory Governance: Right issues must comply with SEBI (Issue of Capital and Disclosure Requirements) Regulations concerning minimum subscription and pricing, whereas bonus issues are governed by strict prohibitions against issuing bonus shares in lieu of dividends.
(c) Main Aspects of Audit of a Banking Company in India
The statutory audit of a banking company in India is governed by the Banking Regulation Act, 1949, the Companies Act, 2013, and prudential guidelines issued by the Reserve Bank of India (RBI). The primary aspects comprise:
Appointment and Reporting: Under Sections 29–30 of the Banking Regulation Act, the auditor of a banking company is appointed with the prior approval of the RBI, and the audit covers the balance sheet and profit and loss account in the forms of the Third Schedule. Large banks are audited branch by branch (central and branch auditors).
Prudential Norms and Asset Classification: The auditor evaluates compliance with RBI’s Income Recognition and Asset Classification (IRAC) norms. Advances must be accurately classified into Standard, Sub-Standard, Doubtful, and Loss categories, verifying that adequate provisioning is computed against Non-Performing Assets (NPAs).
Income Recognition: The auditor verifies that income on performing assets is recognized on an accrual basis, whereas interest on NPAs is strictly accounted for on a cash realization basis, requiring reversal of unrealized accrued interest.
Statutory Liquidity Compliance: The auditor examines the periodic computation and maintenance of the Cash Reserve Ratio (CRR) under the RBI Act, 1934, and the Statutory Liquidity Ratio (SLR) under Section 24 of the Banking Regulation Act.
Verification of Cash, Gold and Investments: The auditor physically verifies cash balances and gold, and examines the valuation and classification of investments in line with RBI norms.
Internal Controls and Fraud Reporting: The auditor reviews the effectiveness of concurrent audit systems, treasury operations, and inter-branch reconciliation, and reports frauds noticed in the course of audit to the Central Government under Section 143(12) of the Companies Act, while the bank itself reports frauds to the RBI. Besides the main report, the auditor submits a Long Form Audit Report (LFAR) in the format prescribed by the RBI, covering advances, deposits, investments and internal controls.
(d) Fair Rent and Annual Rent under Income from House Property
Under Section 23(1) of the Income Tax Act, 1961, income from house property is assessed based on its Gross Annual Value (GAV).
Fair Rent (FR) is the reasonable rent that a similar property with similar specifications, size, and amenities can fetch in the same or similar locality. It serves as a benchmark to ensure actual rent is not understated.
Annual Rent (or Actual Rent Received/Receivable) is the actual consideration agreed upon and received or receivable by the owner from the tenant for letting out the property during the previous year, excluding unrealized rent.
To determine GAV: First, compute the Expected Rent (ER), which is the higher of Municipal Value (MV) and Fair Rent (FR), restricted to Standard Rent (SR) fixed under the Rent Control Act. Second, compare Expected Rent with Actual Rent Received/Receivable (AR). The higher of the two is the GAV (subject to adjustments for vacancy loss).
Illustration: Municipal Value = ₹1,20,000 Fair Rent = ₹1,40,000 Standard Rent = ₹1,30,000 Annual Rent Received = ₹1,50,000
Step 1: Higher of MV (₹1,20,000) and FR (₹1,40,000) is ₹1,40,000, but restricted to SR (₹1,30,000). Thus, Expected Rent = ₹1,30,000. Step 2: GAV is the higher of Expected Rent (₹1,30,000) and Annual Rent Received (₹1,50,000). Hence, GAV = ₹1,50,000. Step 3: If the owner pays municipal taxes of ₹10,000, Net Annual Value = ₹1,40,000. Standard deduction u/s 24(a) at 30% = ₹42,000, so income from house property = ₹98,000 (before interest on borrowed capital u/s 24(b)).
(e) Job Costing and its Distinction from Process Costing
Job costing is a specific order costing method applied where work is executed against individual customer specifications and orders. Under this method, each job is treated as a separate, identifiable cost unit. A dedicated Job Cost Sheet is maintained to accumulate direct materials, direct labour, and allocated production overheads from the commencement of the job until its final completion. It is applied in industries such as printing presses, machine tool manufacturing, interior decoration, and repair workshops.
Job costing differs from process costing in the following respects:
Nature of Production: Job costing applies to discontinuous, heterogeneous, and non-standardized production tailored to customer orders. Process costing is employed in continuous, large-scale mass production of standardized, homogeneous goods (e.g., chemical plants, oil refineries, cement, textiles).
Cost Accumulation: In job costing, costs are collected and traced to each individual job. In process costing, costs are accumulated by distinct processes or departments for a specific accounting period.
Unit Cost Determination: In job costing, unit cost is calculated upon completion of that specific job by dividing total job cost by units produced in that batch. In process costing, unit cost is an average periodic cost computed using the concept of Equivalent Production Units to value work-in-progress.
How this answer will be evaluated
Framework: UPSC Commerce Accountancy Paper 1
What earns full marks: Precise definitions, correct statutory references, and clear examples.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Explain the significance of AS-7 (Construction Contracts): revenue and cost recognition over several periods. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- AS-7 (revised) deals with Construction Contracts in the contractor's books (not segment reporting, which is AS-17)
- Percentage-of-completion method: revenue and costs recognised by stage of completion when the outcome can be estimated reliably
- Expected loss (total cost > total revenue) recognised immediately as an expense
- Disclosures (contract revenue, costs incurred, recognised profit, advances, retentions, amounts due) and the resulting comparability
Loses marks
- Describing AS-7 as segment reporting or cash flow statement
- Recommending the completed-contract method
Earns more
- Stage-of-completion measures: cost-to-cost, surveys, physical proportion
- Fixed-price vs cost-plus contracts, or Ind AS 115 now applies to Ind AS companies
Extra mark
- Short numerical illustration of profit recognised to date
- (b) Explain why companies issue right shares and how right shares differ from bonus shares. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Right issue raises fresh capital from existing shareholders in proportion to holdings (Section 62(1)(a))
- Preserves pre-emptive rights and control, avoids dilution, cheaper and quicker than a public issue
- Right shares bring cash; bonus shares (Section 63) are issued free by capitalising free reserves/securities premium/CRR
- Rights can be renounced and need not be taken up; bonus shares are allotted automatically and cannot be in lieu of dividend
Loses marks
- Claiming bonus shares raise fresh capital
- Omitting renunciation or the source of funds
Earns more
- Offer period 15–30 days and SEBI (ICDR) rules for listed companies
- Effect on share price/EPS: both increase share count, only rights add resources
Extra mark
- Theoretical ex-rights price illustration
- (c) Discuss the main aspects of the audit of a banking company in India. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Legal framework: Banking Regulation Act, 1949 (Sections 29–30; auditor appointed with RBI approval), Companies Act, 2013 and RBI directions
- Advances: IRAC norms, asset classification (standard, sub-standard, doubtful, loss) and NPA provisioning
- Income recognition on NPAs (no accrual), verification of cash, gold, investments and their valuation
- CRR/SLR compliance, internal and concurrent audit, IT systems, fraud reporting and the Long Form Audit Report (LFAR)
Loses marks
- Treating it as a generic company audit
- Omitting NPA/provisioning
Earns more
- Branch audit and consolidation of branch returns
- Off-balance-sheet items: guarantees, letters of credit, derivatives
Extra mark
- Mention of risk-based audit or Section 143(12) fraud reporting
- (d) Define fair rent and annual (actual) rent under income from house property and illustrate how gross annual value is computed. 10 marks · 150 words
define— precise definition → the distinguishing feature → one example
Must cover
- Fair rent: rent a similar property in the same or similar locality would fetch; with municipal value it forms expected rent under Section 23(1)(a)
- Annual/actual rent: rent actually received or receivable for the let-out period (Section 23(1)(b)), excluding unrealised rent
- GAV = higher of expected rent (higher of municipal value and fair rent, capped at standard rent) and actual rent, subject to vacancy allowance
- Worked example with each step (e.g., MV 1.2 lakh, FR 1.4 lakh, SR 1.3 lakh, actual 1.5 lakh gives GAV 1.5 lakh)
Loses marks
- Taking the lower of expected and actual rent
- Example without computation steps
Earns more
- Continues to NAV, 30% standard deduction u/s 24(a) and interest u/s 24(b)
- Mentions standard rent under the Rent Control Act as a ceiling
Extra mark
- Vacancy (Section 23(1)(c)) case illustrated
- (e) Explain job costing and distinguish it from process costing. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- Job costing: specific order costing where each job is a separate cost unit, costs collected on a job cost sheet
- Process costing: costs accumulated by process/department for continuous production of identical units
- Contrast: discrete, customer-specific jobs vs continuous, standardised output; identifiable vs identical units
- Contrast: cost per job on completion vs average cost per unit for the period; equivalent units, normal/abnormal loss and inter-process transfers only in process costing
Loses marks
- Not distinguishing the discrete vs continuous nature
- Confusing job costing with contract costing without comment
Earns more
- Examples: printing, repairs, construction vs cement, chemicals, textiles
- Mention of job/work order and treatment of WIP
Extra mark
- Mention of batch costing as a variant of job costing
What "Explain" is asking you to do
Make the working of something clear — what sets it off, what follows from what, and what it produces. Explain is the Commission's mechanism word: it dominates the technical papers and the “explain why” stems, where the marks sit in the causal chain and not in the label.
Structure that answers it
State what it is → the initiating condition → the chain of cause, step by step → an instance where it plays out → what the chain produces
Where marks are lost
Describing what something looks like instead of why it works that way. Naming the stages without linking them reads as description too.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q1 Answer the following questions in about 150 words each : (10×5=50) (a) Briefly explain th…
- Q2 (a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 202…
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…