Paper I — Q5
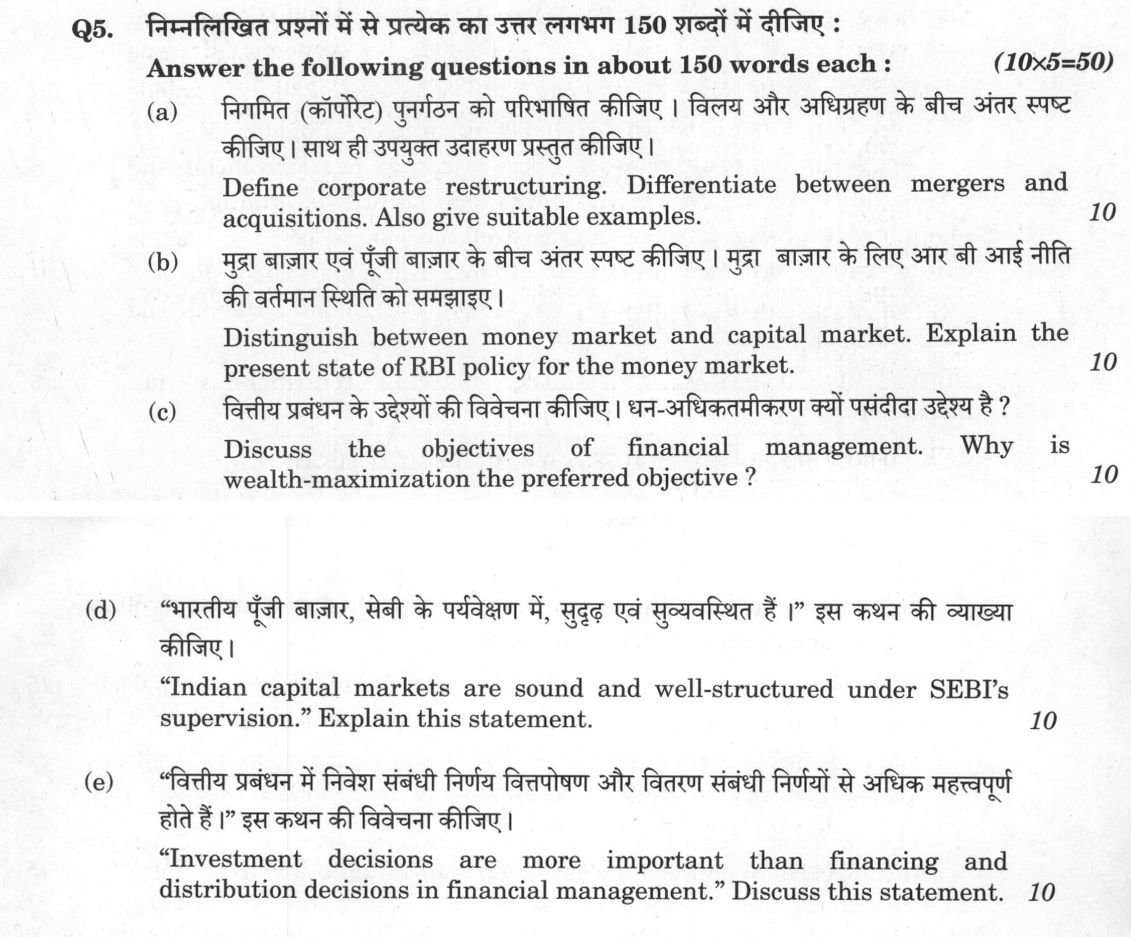
(a) Define corporate restructuring. Differentiate between mergers and acquisitions. Also give suitable examples. (10 marks) (b)…
Answer the following questions in about 150 words each : (10×5=50)
Define corporate restructuring. Differentiate between mergers and acquisitions. Also give suitable examples. 10 marks
Distinguish between money market and capital market. Explain the present state of RBI policy for the money market. 10 marks
Discuss the objectives of financial management. Why is wealth-maximization the preferred objective ? 10 marks
"Indian capital markets are sound and well-structured under SEBI's supervision." Explain this statement. 10 marks
"Investment decisions are more important than financing and distribution decisions in financial management." Discuss this statement. 10 marks
हिंदी में प्रश्न पढ़ें
निम्नलिखित प्रश्नों में से प्रत्येक का उत्तर लगभग 150 शब्दों में दीजिए :
(क) निगमित (कॉर्पोरेट) पुनर्गठन को परिभाषित कीजिए। विलय और अधिग्रहण के बीच अंतर स्पष्ट कीजिए। साथ ही उपयुक्त उदाहरण प्रस्तुत कीजिए। (10 अंक)
(ख) मुद्रा बाजार एवं पूँजी बाजार के बीच अंतर स्पष्ट कीजिए। मुद्रा बाजार के लिए आर बी आई नीति की वर्तमान स्थिति को समझाइए। (10 अंक)
(ग) वित्तीय प्रबंधन के उद्देश्यों की विवेचना कीजिए। धन-अधिकतमीकरण क्यों पसंदीदा उद्देश्य है ? (10 अंक)
(घ) "भारतीय पूँजी बाजार, सेबी के पर्यवेक्षण में, सुदृढ़ एवं सुव्यवस्थित है।" इस कथन की व्याख्या कीजिए। (10 अंक)
(ङ) "वित्तीय प्रबंधन में निवेश संबंधी निर्णय वित्तपोषण और वितरण संबंधी निर्णयों से अधिक महत्त्वपूर्ण होते हैं।" इस कथन की विवेचना कीजिए। (10 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the 150-word length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Corporate Restructuring: Mergers vs Acquisitions
Corporate restructuring is the process of significantly altering a company’s financial structure, operational framework, or ownership portfolio to resolve financial distress, achieve strategic synergies, or enhance shareholder value. It encompasses organizational restructuring (internal realignments, divisional spin-offs) and financial restructuring (debt-equity swaps, recapitalization).
A merger involves the mutual, friendly combination of two or more distinct business entities to form a unified enterprise, typically executed through a pooling-of-interests where assets and liabilities are aggregated. Conversely, an acquisition refers to the purchase of a controlling interest or operational assets of a target company by an acquiring entity, which may be negotiated or hostile, employing the purchase method of accounting.
For instance, the amalgamation of HDFC Limited with HDFC Bank represents a strategic mega-merger creating a unified financial conglomerate, whereas Tata Group’s takeover of state-run Air India exemplifies a complete strategic acquisition.
(b) Money Market vs Capital Market and RBI’s Money Market Policy
The money market deals with short-term, highly liquid debt instruments with maturities up to one year (such as Treasury Bills, Commercial Papers, and Certificates of Deposit), catering to working capital and liquidity requirements among institutional players like commercial banks, primary dealers, and the central bank. In contrast, the capital market facilitates medium-to-long-term capital mobilization exceeding one year through equity shares, preference shares, and debentures, connecting corporate issuers with retail and institutional investors for long-term capital formation.
The Reserve Bank of India manages the money market primarily through its Liquidity Adjustment Facility (LAF) corridor. The introduction of the Standing Deposit Facility (SDF) as the non-collateralized floor rate, alongside the marginal standing facility (MSF) ceiling, anchors the weighted average call rate (WACR) around the policy repo rate. RBI actively modulates systemic liquidity through fine-tuning Variable Rate Repo (VRR) and Reverse Repo (VRRR) auctions, supplemented historically by Operation Twist to manage yield curve dynamics, ensuring orderly monetary transmission while stabilizing short-term interest rates.
Present position (policy of 5 August 2026): the repo rate is 5.25% with a neutral stance, the SDF rate 5.00%, the MSF rate and Bank Rate 5.50%, CRR 3% and SLR 18%. This follows 125 basis points of rate cuts in 2025 (from 6.50%) and a CRR cut from 4% to 3%, which made system liquidity surplus; RBI now uses VRR/VRRR operations and open market operations to keep the WACR, its operating target, close to the repo rate.
(c) Objectives of Financial Management: Primacy of Wealth Maximization
Financial management traditionally alternates between two primary objectives: profit maximization and wealth maximization. Profit maximization focuses narrowly on maximizing short-term accounting earnings or Earnings Per Share (EPS). However, it suffers from severe limitations: it ignores the time value of money, overlooks business and financial risk, is ambiguous regarding the definition of profit (gross, net, or operational), and encourages myopic management practices prone to accounting manipulation.
Wealth maximization is universally preferred because it maximizes the net present value (NPV) of financial actions, thereby maximizing the intrinsic market value of the firm's equity shares. It explicitly integrates the timing and duration of expected cash flows through discount rates reflecting risk, aligns management incentives with long-term shareholder interests, and incorporates market perceptions of uncertainty. By evaluating cash flows rather than accounting profits, it ensures sustainable long-term value creation.
(d) Soundness of Indian Capital Markets under SEBI’s Supervision
The Securities and Exchange Board of India (SEBI) has transformed Indian capital markets into a transparent, resilient, and technologically advanced ecosystem through comprehensive structural reforms. In the primary market, SEBI institutionalized efficient price discovery via book-building processes and mitigated retail payment risks through the Application Supported by Blocked Amount (ASBA) and UPI integration. In secondary markets, mandatory dematerialization, nationwide electronic trading, and the migration to the T+1 settlement cycle—with phased implementation of T+0—have minimized counterparty and settlement risks. Investor protection is reinforced through the digital SCORES redressal portal and SMART ODR mechanism, supported by stringent Foreign Portfolio Investor (FPI) disclosure norms.
However, rapid financialization poses emerging challenges, including hyper-speculative retail trading in index derivatives (F&O), algorithmic trading disparities, and sophisticated front-running. SEBI's own studies found that about nine in ten individual F&O traders lose money, and from late 2024 it raised the minimum contract size, limited weekly index expiries to one benchmark per exchange and required upfront collection of option premium. A progressive regulatory architecture must continuously balance market innovation with systemic risk mitigation.
(e) Primacy of Investment Decisions in Financial Management
Investment decisions, specifically capital budgeting and asset allocation, form the cornerstone of financial management. They dictate the composition of a firm's operational asset base, business risk profile, and future revenue-generating capacity. Because capital expenditures involve massive resource commitments that are largely irreversible without substantial loss, an optimal investment decision is the primary creator of economic value added (EVA) and competitive advantage.
Nonetheless, financial management relies on an interdependent tripod of investment, financing, and dividend decisions. While investment generates operating cash flows, the financing decision minimizes the weighted average cost of capital (WACC) through optimal debt-equity leverage, providing the required funds at minimum risk. Concurrently, dividend decisions balance internal capital retention with market signaling to protect share valuations. Thus, while investment decisions serve as the primary engine of wealth generation, their ultimate success remains conditioned on sound financing and distribution strategies.
How this answer will be evaluated
What earns full marks: Precise definitions, clear distinctions, specific examples, and logical reasoning.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Define corporate restructuring and differentiate mergers from acquisitions with examples. 10 marks · 150 words
define— precise definition → the distinguishing feature → one example
Must cover
- Corporate restructuring: change in ownership, asset, capital or operating structure to improve value or resolve distress (merger, demerger, acquisition, buy-back, debt restructuring)
- Merger/amalgamation: two or more companies combine into one, with the transferor's shareholders becoming shareholders of the combined entity (Sections 230–232, Companies Act, 2013)
- Acquisition/takeover: one company buys control (shares or assets) of another, which may continue separately; may be friendly or hostile (SEBI SAST Regulations)
- Relevant Indian examples (e.g., HDFC Ltd with HDFC Bank as a merger; Tata Sons' acquisition of Air India)
Loses marks
- Using merger and acquisition interchangeably
- No examples
Earns more
- Types: horizontal, vertical, conglomerate
- Motives: synergy, market share, tax benefits
Extra mark
- Mentions CCI approval thresholds or fast-track mergers under Section 233
- (b) Distinguish money and capital markets and explain the present RBI policy for the money market. 10 marks · 150 words
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- Maturity: up to one year (money market) vs over one year (capital market)
- Instruments and participants: T-bills, CP, CD, call money, repo vs shares, debentures, bonds; regulators RBI vs SEBI
- RBI operating framework: LAF corridor with SDF floor, MSF ceiling, WACR as operating target, VRR/VRRR operations
- Current settings: repo 5.25%, SDF 5.00%, MSF 5.50%, CRR 3%, SLR 18%, neutral stance (August 2026), after the 2025 easing cycle
Loses marks
- Out-of-date or wrong policy rates presented as current
- Confusing money market with capital market instruments
Earns more
- Role of money market in monetary transmission
- Tri-party repo, CROMS or other market developments
Extra mark
- Mentions the liquidity surplus/deficit position and its effect on rates
- (c) Discuss the objectives of financial management and why wealth maximisation is preferred. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Objectives: profit maximisation, wealth (value) maximisation, liquidity, return and risk balance
- Limitations of profit maximisation: vague, ignores time value, risk and quality of earnings
- Wealth maximisation: maximising the market value of shares, i.e., NPV of future cash flows discounted at a risk-adjusted rate
- Why preferred: considers time value, risk and long-term interests of shareholders and stakeholders
Loses marks
- Only listing objectives without justification
- Treating profit and wealth maximisation as identical
Earns more
- Formula W = V − C or share price as the measure
- Agency problem and stakeholder view
Extra mark
- Critique: short-term market prices and ESG considerations
- (d) Explain how Indian capital markets have become sound and well-structured under SEBI's supervision. 10 marks · 150 words
explain— definition/context → points in order → small example → short close
Must cover
- SEBI's statutory role under the SEBI Act, 1992: protecting investors, developing and regulating markets
- Primary market reforms: disclosure (ICDR), book building, ASBA/UPI
- Secondary market: dematerialisation, electronic trading, T+1 settlement, surveillance, margins
- Balanced view: remaining challenges such as retail F&O losses, manipulation, and SEBI's responses
Loses marks
- One-sided praise without challenges
- No specific SEBI measures
Earns more
- Investor grievance redress (SCORES, ODR)
- Regulation of intermediaries, mutual funds, FPIs
Extra mark
- Data: rising demat accounts or market capitalisation
- (e) Discuss whether investment decisions are more important than financing and dividend decisions. 10 marks · 150 words
discuss— intro → 3-4 dimensions → example → balanced close
Must cover
- Investment decisions: capital budgeting and working capital; they determine asset base, risk and returns
- Financing decision: capital structure and cost of capital
- Dividend decision: payout vs retention; signalling
- Balanced conclusion: investment is primary for value creation, but the three decisions are interdependent
Loses marks
- Ignoring financing and dividend decisions
- No conclusion
Earns more
- Irreversibility and large outlays of capital projects
- MM view that financing/dividend are irrelevant in perfect markets
Extra mark
- Example of a firm whose poor investment destroyed value despite good financing
What "Discuss" is asking you to do
Lay the issue out from more than one side — how it arose, what is claimed for it, what is held against it, and where it now stands. UPSC attaches discuss to broad topics with several live dimensions, so coverage of the dimensions earns more than the strength of your opinion.
Structure that answers it
Set the issue up → the case as it is made → the case against → the dimension both sides leave out → where the balance now lies
Where marks are lost
Listing facts with no thread between them, or arguing one side throughout and calling it a discussion.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Commerce & Accountancy 2024 Paper I
- Q2 (a) A Ltd. has acquired the business of B Ltd., whose Balance Sheet as at 31st March, 202…
- Q3 (a) During the month of May 2024, total 2000 units were introduced into Process-I. The no…
- Q4 (a) Mrs. Y (59 years) receives ₹ 7,90,000 as basic pay and ₹ 1,18,000 as bonus during the…
- Q5 Answer the following questions in about 150 words each : (10×5=50) (a) Define corporate r…
- Q6 (a) Six years ago, a machine was purchased for ₹ 3,00,000. It has been depreciated to a b…
- Q7 (a) The Board of Directors of a company asks to prepare a statement showing working capit…
- Q8 (a) Explain the key classification of the Indian financial system. Make a diagram that de…