Paper I — Q8
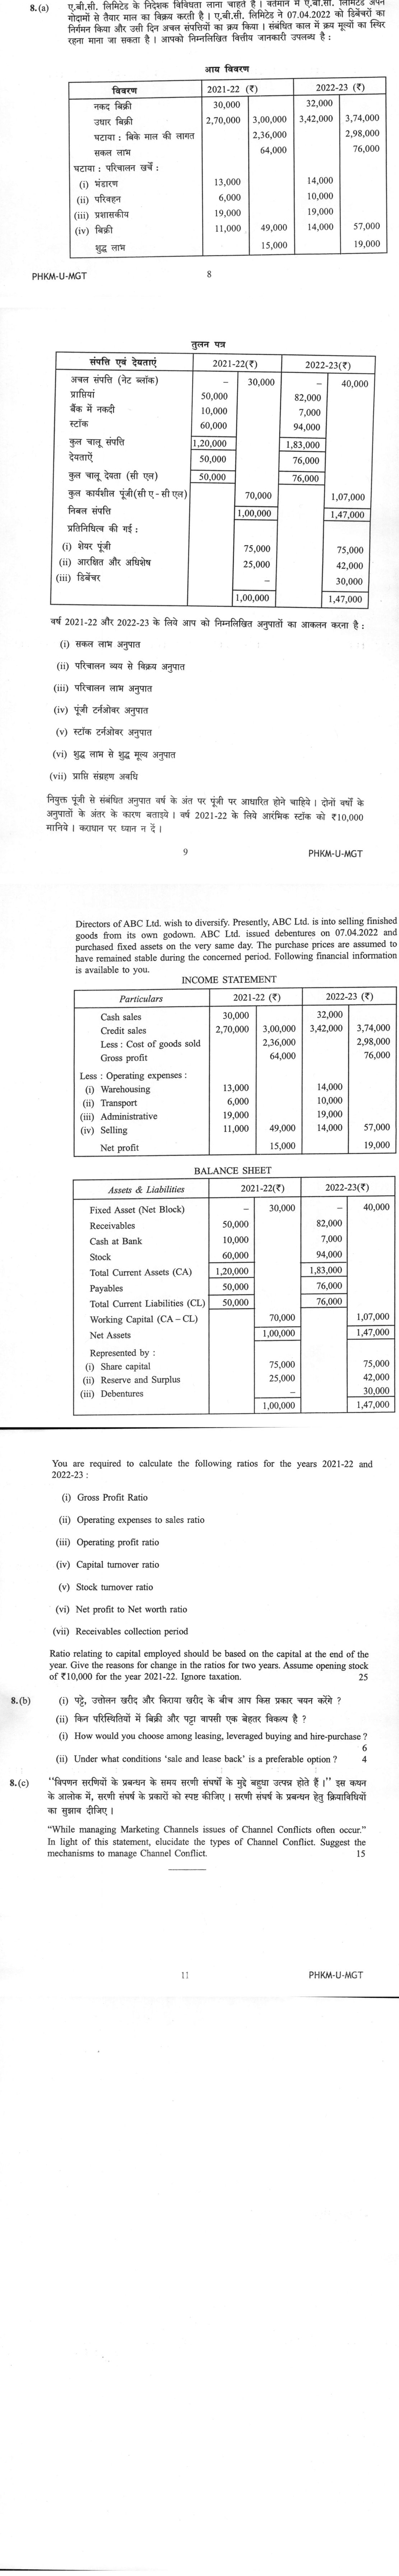
(a) Directors of ABC Ltd. wish to diversify. Presently, ABC Ltd. is into selling finished goods from its own godown. ABC Ltd…
Directors of ABC Ltd. wish to diversify. Presently, ABC Ltd. is into selling finished goods from its own godown. ABC Ltd. issued debentures on 07.04.2022 and purchased fixed assets on the very same day. The purchase prices are assumed to have remained stable during the concerned period. Following financial information is available to you. [INCOME STATEMENT and BALANCE SHEET data provided] You are required to calculate the following ratios for the years 2021-22 and 2022-23 : (i) Gross Profit Ratio (ii) Operating expenses to sales ratio (iii) Operating profit ratio (iv) Capital turnover ratio (v) Stock turnover ratio (vi) Net profit to Net worth ratio (vii) Receivables collection period. Ratio relating to capital employed should be based on the capital at the end of the year. Give the reasons for change in the ratios for two years. Assume opening stock of ₹10,000 for the year 2021-22. Ignore taxation. 25 marks
How would you choose among leasing, leveraged buying and hire-purchase ? 6 marks
Under what conditions 'sale and lease back' is a preferable option ? 4 marks
"While managing Marketing Channels issues of Channel Conflicts often occur." In light of this statement, elucidate the types of Channel Conflict. Suggest the mechanisms to manage Channel Conflict. 15 marks
हिंदी में प्रश्न पढ़ें
ए.बी.सी. लिमिटेड के निदेशक विविधता लाना चाहते हैं । वर्तमान में ए.बी.सी. लिमिटेड अपने गोदामों से तैयार माल का विक्रय करती है । ए.बी.सी. लिमिटेड ने 07.04.2022 को डिब्बों का निर्माण किया और उसी दिन अचल संपत्तियों का क्रय किया । संबंधित काल में क्रय मूल्यों का स्थिर रहना माना जा सकता है । आपको निम्नलिखित वित्तीय जानकारी उपलब्ध है । [आय विवरण और तुलन पत्र का विवरण दिया गया है] वर्ष 2021-22 और 2022-23 के लिये आप को निम्नलिखित अनुपातों का आकलन करना है : (i) सकल लाभ अनुपात (ii) परिचालन व्यय से विक्रय अनुपात (iii) परिचालन लाभ अनुपात (iv) पूंजी टर्नओवर अनुपात (v) स्टॉक टर्नओवर अनुपात (vi) शुद्ध लाभ से शुद्ध मूल्य अनुपात (vii) प्राप्ति संग्रहण अवधि । नियुक्त पूंजी से संबंधित अनुपात वर्ष के अंत पर पूंजी पर आधारित होने चाहिये। दोनों वर्षों के अनुपातों के अंतर के कारण बताइये। वर्ष 2021-22 के लिये आरंभिक स्टॉक को ₹10,000 मानिये। कराधान पर ध्यान न दें । (25 अंक)
पट्टे, उत्तोलन खरीद और किराया खरीद के बीच आप किस प्रकार चयन करेंगे ? (6 अंक)
किन परिस्थितियों में बिक्री और पट्टा वापसी एक बेहतर विकल्प है ? (4 अंक)
"विपणन सरनियों के प्रबंधन के समय सरनी संघर्ष के मुद्दे बहुधा उत्पन्न होते हैं।" इस कथन के आलोक में, सरनी संघर्ष के प्रकारों को स्पष्ट कीजिए । सरनी संघर्ष के प्रबंधन हेतु क्रियाविधियों का सुझाव दीजिए । (15 अंक)
Model answer
Drafted with AI by UPSC Answer Check against this question's marking rubric, to the expected length. UPSC does not publish answers for Mains — this is one way to score well, not an official key. How we build rubrics and answers.
(a) Ratio analysis of ABC Ltd.
Basis. Total sales are used (₹3,00,000; ₹3,74,000). Capital employed is closing net assets (₹1,00,000; ₹1,47,000) and net worth is capital plus reserves (₹1,00,000; ₹1,17,000). Average stock uses the assumed ₹10,000 opening stock. The collection period uses credit sales and 365 days.
- (i) Gross profit ratio (GP ÷ Sales × 100): 2021-22: 64,000/3,00,000 = 21.33%; 2022-23: 76,000/3,74,000 = 20.32%.
- (ii) Operating expenses to sales (Opex ÷ Sales × 100): 2021-22: 49,000/3,00,000 = 16.33%; 2022-23: 57,000/3,74,000 = 15.24%.
- (iii) Operating profit ratio ((GP − Opex) ÷ Sales × 100): 2021-22: 15,000/3,00,000 = 5.00%; 2022-23: 19,000/3,74,000 = 5.08%.
- (iv) Capital turnover (Sales ÷ closing capital employed): 2021-22: 3,00,000/1,00,000 = 3.00 times; 2022-23: 3,74,000/1,47,000 = 2.54 times.
- (v) Stock turnover (COGS ÷ average stock): 2021-22: 2,36,000/35,000 = 6.74 times; 2022-23: 2,98,000/77,000 = 3.87 times.
- (vi) Net profit to net worth (NP ÷ Net worth × 100): 2021-22: 15,000/1,00,000 = 15.00%; 2022-23: 19,000/1,17,000 = 16.24%.
- (vii) Receivables collection period (Receivables ÷ Credit sales × 365): 2021-22: 50,000/2,70,000 × 365 = 67.6 days; 2022-23: 82,000/3,42,000 × 365 = 87.5 days.
Reasons for the changes
- Gross profit ratio fell. Sales grew 24.7% but cost of goods sold grew 26.3%. With stable purchase prices, this points to price cuts, discounts or a changed sales mix to push volume.
- Operating expenses fell as a share of sales. Fixed administrative (₹19,000) and warehousing costs were spread over higher sales, though transport (+67%) and selling (+27%) costs rose with volume.
- Operating profit ratio edged up to 5.08%, as cost savings slightly outweighed the lower margin.
- Capital turnover fell from 3.00 to 2.54. Capital employed rose 47% (₹30,000 debentures issued on 7 April 2022) against 24.7% sales growth; the funds went into fixed assets (+₹10,000) and mainly working capital (+₹37,000), not yet yielding proportionate sales.
- Stock turnover fell sharply from 6.74 to 3.87. Stock rose from ₹60,000 to ₹94,000 (stock-piling, perhaps for diversification, or slow-moving goods); 2021-22 is also flattered by the low assumed opening stock.
- Return on net worth rose from 15% to 16.24%. Profit grew 26.7% while net worth grew only 17%, because part of the expansion was financed by debentures (trading on equity). Reserves rose only ₹17,000 against ₹19,000 profit (about ₹2,000 appropriated), and no debenture interest is shown, so the return may be overstated.
- Collection period lengthened from about 68 to 88 days (liberal credit to boost sales, weaker collection); cash fell to ₹7,000.
Conclusion. Growth has been bought with thinner gross margins, heavier inventory and slower collections. Before diversifying, ABC Ltd. should tighten its stock and credit control.
(b)(i) Choosing among leasing, leveraged buying and hire-purchase
The right choice is the option with the lowest present value of after-tax cash outflows, weighed against the need for ownership and flexibility.
- Ownership: under leasing it stays with the lessor; under leveraged buying the buyer owns from day one; under hire-purchase it passes after the last instalment.
- Tax shield: leasing gives it on lease rentals; leveraged buying on depreciation and loan interest; hire-purchase on depreciation and the interest element.
- Residual value: belongs to the lessor under leasing, and to the buyer under leveraged buying and hire-purchase.
- Balance sheet and flexibility: leasing shifts obsolescence risk and carries no borrowing covenants; leveraged buying raises gearing and brings loan covenants; hire-purchase needs a down payment and the asset can be repossessed.
Decision rule. Discount after-tax lease rentals, and loan or hire-purchase instalments net of interest and depreciation tax shields and salvage value, at the after-tax cost of debt; choose the cheapest (the comparison is a discounted-cash-flow one, not a merely accounting one). Qualitatively, leasing suits technologically obsolescent assets. Leveraged buying suits long-lived core assets when the firm has unused debt capacity. Hire-purchase suits firms that want eventual ownership with staggered payments.
(b)(ii) When sale and lease-back is preferable
Under a sale and lease-back, the firm sells an asset it owns, usually property or plant, and leases it back so that it can keep using it. It is preferable when:
- the firm needs immediate liquidity for expansion, working capital or debt repayment, and fresh borrowing is costly or restricted by covenants;
- the asset is non-core, appreciated in value or under-utilised as capital, so selling it unlocks value while its use continues;
- the lease rentals are fully tax-deductible and give a better tax shield than depreciation on a largely depreciated asset;
- the firm wants to lower gearing, shift the risks of maintenance and ownership, and focus its capital on its core business.
(c) Channel conflict: types and management
Channel conflict arises when one channel member's actions prevent the channel from achieving its goals. Its sources include incompatible goals, unclear roles and territories, and differing perceptions.
Types of channel conflict
- Vertical conflict: between different levels of the same channel. For example, a manufacturer and distributors disputing margins, credit terms or service levels.
- Horizontal conflict: between members at the same level. For example, dealers of one brand poaching customers across territories or undercutting prices.
- Multichannel conflict: when the producer sells through two or more channels that serve the same market. A common case is e-commerce or direct sales undercutting traditional dealers.
Mechanisms to manage conflict
- Superordinate goals: persuade members that the channel competes as a whole against rival channels.
- Clear channel design: exclusive or clearly defined territories, role charters, and different products, brands or price bands for each channel.
- Pricing discipline: uniform or minimum advertised prices and fair margins for each channel.
- Communication and co-optation: dealer councils, joint planning, and exchange of people between levels.
- Incentives and power: reward-based and expert power, such as training, credit support and performance bonuses, in preference to coercion.
- Dispute resolution: diplomacy, mediation, arbitration; litigation last.
- Channel integration: vertical marketing systems (corporate, contractual or administered) led by a channel captain. Omnichannel models can credit local dealers for online orders in their area.
How this answer will be evaluated
Framework: Financial Ratio Analysis (Profitability, Liquidity, Activity, Leverage)
What earns full marks: Accurate calculations with clear reasoning; comprehensive comparison of financing options; detailed analysis of channel conflicts with practical solutions.
Evaluation rubric
Each sub-part is marked on its own, against the marks and word limit printed on the paper.
- (a) Compute seven ratios for 2021-22 and 2022-23 and give reasons for changes. 25 marks
calculate— given → formula → substitution → result with units → interpretation
Must cover
- GP ratio 21.33% → 20.32%; opex to sales 16.33% → 15.24%; operating profit ratio 5.00% → 5.08%
- Capital turnover 3.00 → 2.54 (closing capital employed ₹1,00,000; ₹1,47,000 incl. debentures); stock turnover 6.74 → 3.87 (average stock with ₹10,000 opening)
- NP to net worth 15.00% → 16.24% (net worth ₹1,17,000); collection period ≈ 67.6 → 87.5 days on credit sales
- Reasons: margin squeeze, spreading of fixed costs, debenture-funded expansion, stock build-up, slower collections, trading on equity
Loses marks
- Using closing stock only for stock turnover without stating it
- Including debentures in net worth
Earns more
- Stated bases and assumptions
- Note on missing debenture interest / appropriation
Extra mark
- Recommendation before diversification
- (b)(i) How to choose among leasing, leveraged buying and hire-purchase. 6 marks
compare— paired headings or point-wise contrast → key differences → significance → conclusion
Must cover
- Features of each: ownership, tax shields, residual value, obsolescence risk
- Evaluation by present value of after-tax cash outflows at after-tax cost of debt
- Qualitative factors: flexibility, covenants, gearing, asset life, technology risk
- Decision guidance for each option
Loses marks
- Only definitions
- No decision criterion
Earns more
- Down payment and repossession risk in hire-purchase
- Accounting treatment (Ind AS 116) effect
Extra mark
- Numerical sketch of the comparison
- (b)(ii) Conditions under which sale and lease-back is preferable. 4 marks
explain— definition/context → points in order → small example → short close
Must cover
- Meaning: sell an owned asset and lease it back to keep using it
- Need for liquidity when borrowing is costly or restricted
- Unlocking value of appreciated or non-core assets; tax advantages of rentals
- Shifting ownership risks, focusing capital on core business; costs and loss of residual value noted
Loses marks
- Confusing with ordinary leasing
- No conditions stated
Earns more
- Real-estate examples
- Effect on gearing ratios
Extra mark
- Ind AS 116 sale-and-leaseback treatment
- (c) Types of channel conflict and mechanisms to manage it. 15 marks
explain— definition/context → points in order → small example → short close
Must cover
- Meaning and causes of channel conflict (goal incompatibility, unclear roles, differing perceptions, dependence)
- Types: vertical, horizontal, multichannel (with examples such as online vs dealers)
- Management mechanisms: superordinate goals, clear territories and roles, pricing discipline, communication/co-optation, incentives and power, dispute resolution
- Vertical marketing systems and channel captain; omnichannel crediting
Loses marks
- Listing types without examples
- No resolution mechanisms
Earns more
- Functional vs dysfunctional conflict
- Indian FMCG/e-commerce examples
Extra mark
- Channel power bases
What "Calculate" is asking you to do
Apply the standard formula or schedule to data the question has already supplied — a table of readings, cost records, a balance sheet — and produce the number. The method is rarely in doubt; the marks sit in the named intermediate quantities, each of which has to appear as a labelled line.
Structure that answers it
Data as given → formula or standard treatment, named → substitution → each intermediate, labelled → result with units
Where marks are lost
Omitting an intermediate the marking scheme pays for separately, or rounding at an intermediate line so the final figure drifts. In commerce and accountancy, any figure in a statement that no numbered working note supports is treated as unearned.
Practice this exact question
Write your answer and it is marked point by point against the model answer above — what you covered, what you missed, what you got wrong.
Evaluate my answer →More from Management 2024 Paper I
- Q5 (a) How can Cost-Volume-Profit (CVP) analysis be used to assess the effect of changes in…
- Q6 (a) A proforma cost sheet of a company provides the following data : | Cost per unit | ₹…
- Q7 (a) Sunder Ltd. is planning an expansion programme which will require ₹30 crores and can…
- Q8 (a) Directors of ABC Ltd. wish to diversify. Presently, ABC Ltd. is into selling finished…